
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Hexcel Holders Saw Early
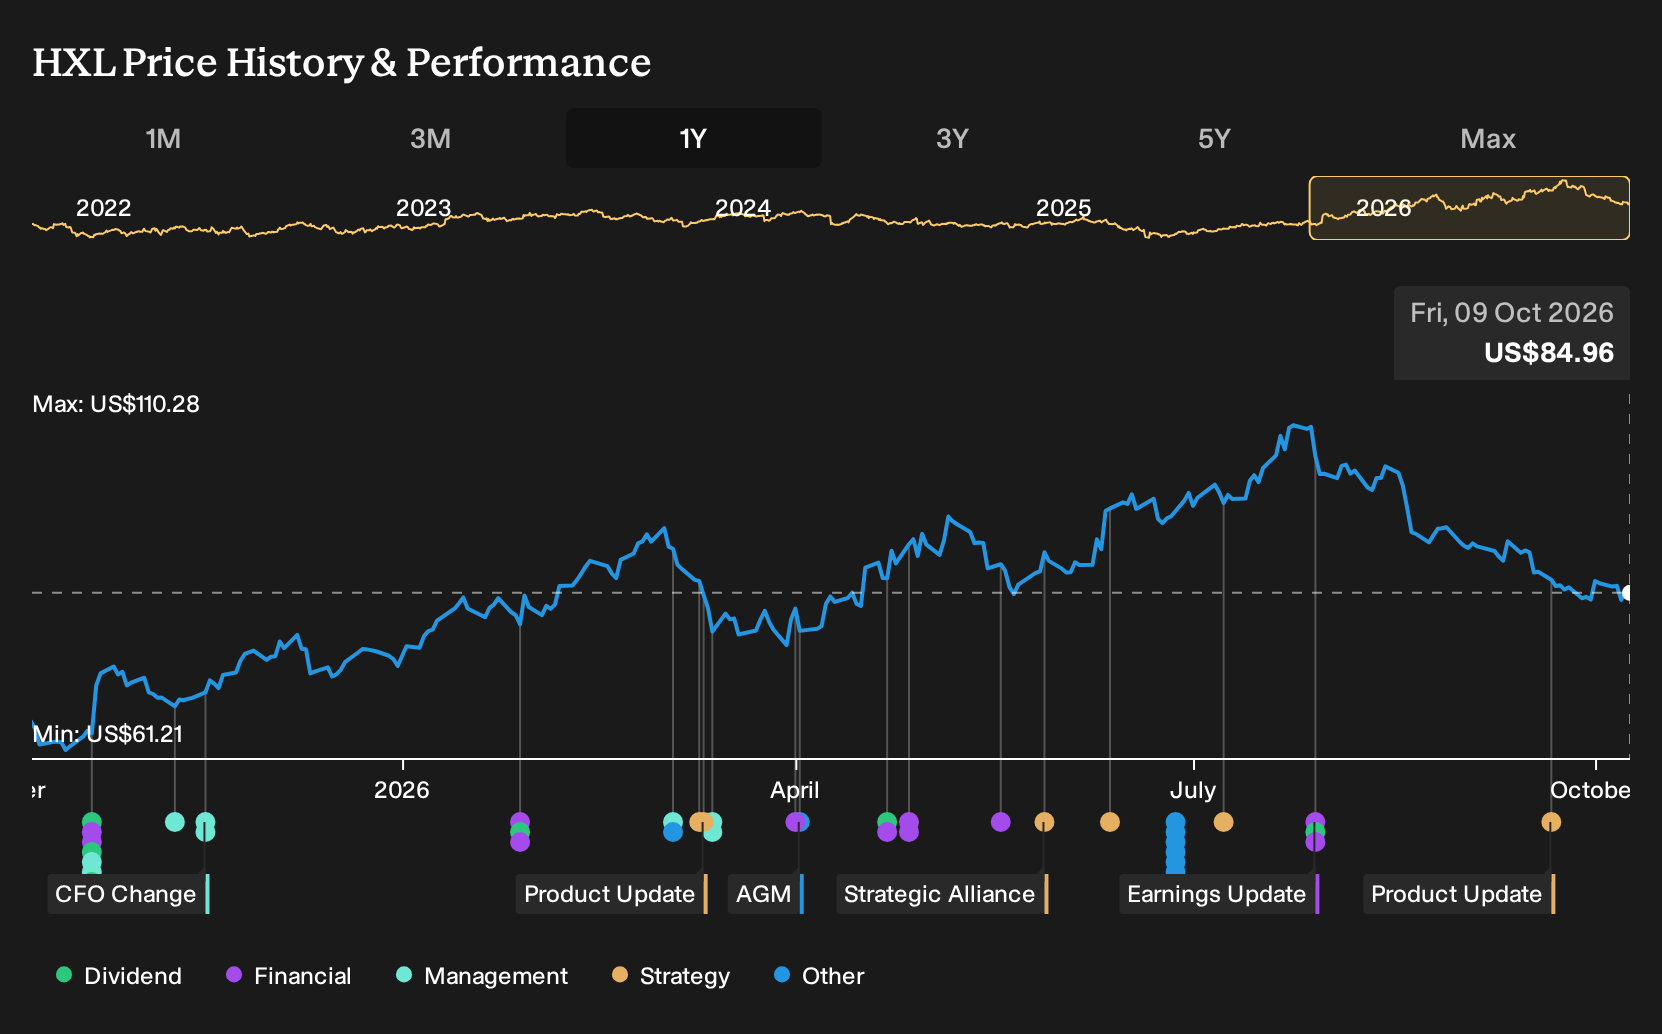
If Hexcel sat on your watchlist instead of in your brokerage account, the past year may feel like a missed shot. For Hexcel shareholders, the return over the past year was 38.1%, including dividends. That outcome landed after a period when analysts were split between a bullish composite demand story and worries about supply chain delays and weaker aircraft production rates. If you rewind to October 2025, how could you have weighed Hexcel’s dependence on Airbus and Boeing against its life of program contracts and capacity already in place?
If the move has made Hexcel harder to judge, start where the gap is still open and scan 28 high quality undervalued stocks.
Two Hexcel Stories Investors Had To Hold In Their Heads
The shares cost US$64.47 at the start of the period, and Hexcel sat between two competing stories that both sounded plausible.
On the bullish side, the narrative pointed to a Fair Value of US$71, a price implied by expectations for a multiyear ramp in composite demand as Airbus A350 output increased. Fuel efficiency and decarbonization needs were also expected to support higher composite content.
The more cautious view anchored to a Fair Value of US$55. This reflected worries that supply chain delays, slower Airbus and Boeing production, and tariff costs of US$3 million to US$4 million per quarter could keep margins under pressure.
What The Results Changed In The Hexcel Debate
Rising commercial aerospace demand showed up in Hexcel’s numbers. Q2 2026 revenue was US$529.3 million versus US$489.9 million a year earlier, and net income moved from US$13.5 million to US$49.3 million, with net margin lifting from 2.8% to 9.3%. That profitability shift supported the optimistic case that stronger volumes could make existing capacity more rewarding.
The useful takeaway is how that argument hinged on operating leverage. When judging another supplier tied to big OEM production ramps, track whether higher sales are turning into a meaningfully higher net margin, not just a bigger top line.
What Hexcel’s Price Already Bakes In
Hexcel now trades at US$84.96, with the selected Narrative’s Fair Value placed above that level. The gap rests on the idea that existing plants and long contracts can support richer margins as commercial and defense volumes move through those facilities.
For anyone assessing Hexcel today, the key question is whether the extra revenue the Narrative describes can realistically pass through existing capacity into the margin and cash flow profile it assumes.
"Key Takeaways: Analysts expect Hexcel to convert the commercial aerospace and defense production ramp, along with rising composite content in new platforms, into multi year revenue growth and stronger free cash flow. The main condition is that Hexcel turns the planned roughly $700 million of incremental commercial and defense revenue and its existing capacity into the higher margin profile management is targeting, while containing inflation and start up costs."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Hexcel And A Different Flight Path
Hexcel puts advanced materials into aircraft. You could also track who is sending hardware into orbit.
Space-focused engineers aim to build a cheaper, repeatable launch routine. Instead of crewed flights, they focus on reliable rockets and the equipment riding on them.
The same customers that need lighter jets also want affordable access to orbit. One business is working across both launch vehicles and the payloads they lift.
If that model works, more satellites and services could lean on it. The unresolved issue is how dependable that combined launch and hardware engine becomes.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 43% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com