
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Xiaomi (SEHK:1810) Lands 70,000 EV Orders, Is The Upside Already Priced In?
Xiaomi (SEHK:1810) drew fresh attention after its new SkyNomad electric vehicle line secured 70,000 orders in the first month, with more than 10,000 cars delivered in September, indicating strong interest in its auto push.
The sharp 9.72% 1 day share price return, taking Xiaomi to HK$25.96, contrasts with a weaker year-to-date share price return of a 35.55% decline and a 1 year total shareholder return of a 50.12% decline. The 3 year total shareholder return of 106.03% suggests earlier momentum that recent trading has not yet fully recaptured.
Compare Xiaomi's EV-fueled momentum with other hand-picked plays in the sector by scanning the 91 robotics and automation stocks that could benefit from similar shifts toward smart hardware and automation.
After a sharp one day jump and a long stretch of weaker returns, Xiaomi now sits at a crossroads. Is this EV driven spark the start of more upside, or has most of the easy gain already passed?
Most Popular Narrative: 37% Undervalued
Xiaomi's most followed valuation story currently points to a fair value of HK$41.16 against the latest close at HK$25.96, a sizeable gap that puts the EV push and broader ecosystem strategy under a brighter spotlight. According to kapirey, the narrative leans heavily on Xiaomi evolving beyond phones into a tightly linked mix of hardware, vehicles, and software services.
Xiaomi is no longer just:
It is evolving into: 👉 A multi-sector, deep-tech ecosystem company with capabilities in AI, EVs, robotics, and advanced manufacturing
See why 12 investors see Xiaomi as 37% undervalued.
Result: Fair Value of HK$41.16 (UNDERVALUED)
Still, Xiaomi’s story could be knocked off course if smartphone profitability stays under pressure or if heavy EV and AI investment keeps weighing on overall margins.
Find out about the key risks to this Xiaomi narrative.
Another View On Xiaomi’s Valuation
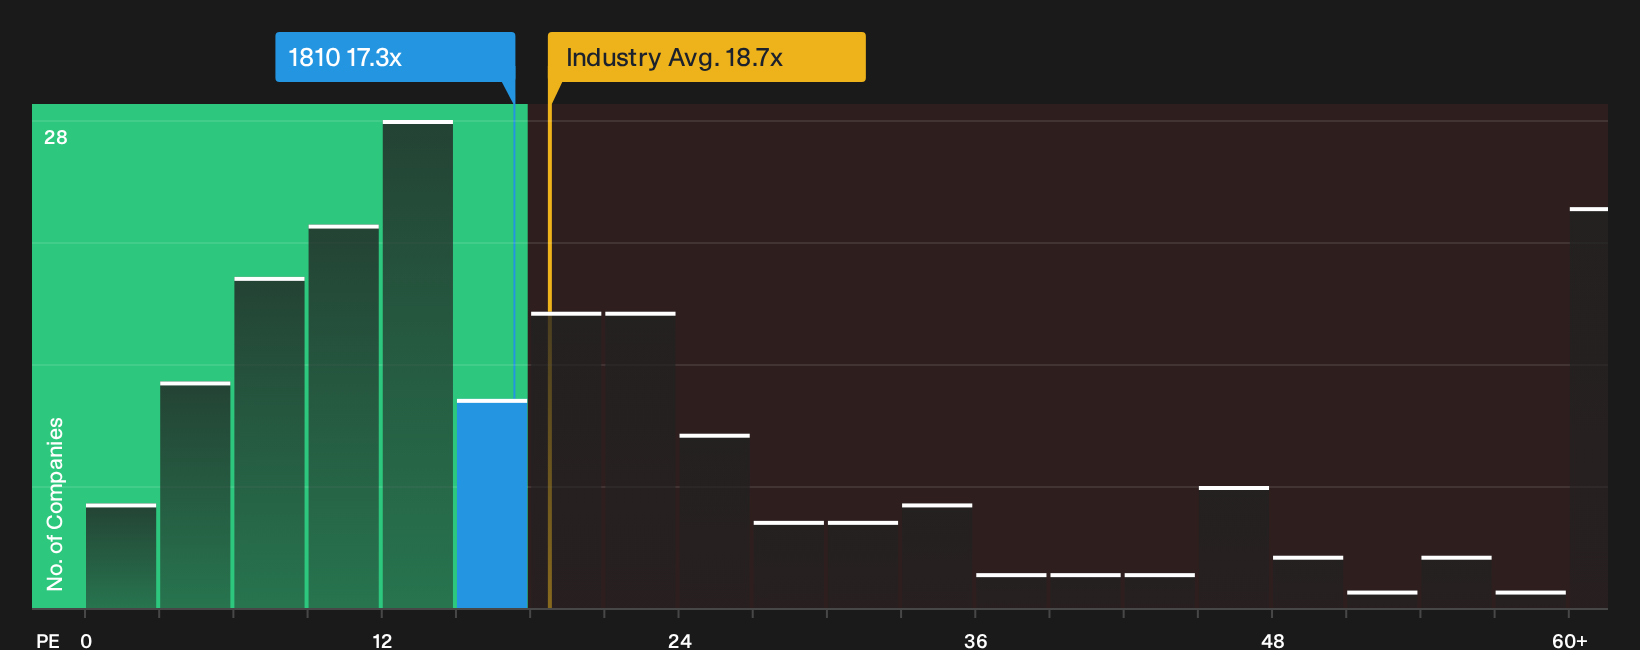
The fair value of HK$41.16 comes from narrative-driven modelling and user assumptions. A second lens is simple earnings pricing. Xiaomi trades on a P/E of 17.3x, compared with a fair ratio of 15.2x and an Asian tech average of 18.7x. That mix hints at both upside optionality and the risk of the market re-pricing toward the fair ratio. Which possibility are you more comfortable underwriting?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Xiaomi story today, with both concerns and bright spots on the table, mean the real edge comes from reading the details yourself and moving decisively. To weigh those cross currents directly, start with Xiaomi's 2 key rewards and 1 important warning sign.
Looking for more Xiaomi investment ideas?
If Xiaomi has your attention, do not stop here. Broader context from other opportunities can sharpen your judgement and help you act with more conviction.
- Target potential mispricings by scanning a curated set of companies that look cheap on quality and fundamentals through the 174 high quality undervalued stocks.
- Strengthen your income plan by reviewing a focused group of high yield candidates in the 223 dividend fortresses.
- Dial down portfolio stress by filtering for resilient businesses using the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com