
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is 3SBio (SEHK:1530) Cheap On Its MindRank AI Obesity Drug Deal?
3SBio (SEHK:1530) is back in focus after subsidiaries Zhejiang Sunshine Mandi and Zhejiang Wansheng signed a commercialization deal with MindRank AI for MDR-001, an oral GLP-1 obesity drug currently in pivotal Phase 3 trials.
Despite the MDR-001 announcement putting 3SBio back in the headlines, the share price has been weak over a longer stretch, with the stock down about 38.7% on a year-to-date share price basis, even as the three-year total shareholder return is more than double.
Scan beyond 3SBio and this GLP-1 headline by lining up other potential biotech movers through our curated list of 618 high quality undiscovered gems.
3SBio has a fresh obesity deal, a weak recent share price and a three year return that is already strong. How much of the valuation case is still in front of you, rather than behind you?
Price-to-Earnings of 3.9x: Is it justified for 3SBio?
On a simple yardstick, 3SBio looks inexpensive, with a P/E of 3.9x at a last close of HK$15.07, while analysts and models both point to higher values. The SWS DCF model estimates a future cash flow value of HK$33.62 per share and the stock is also flagged as trading at a 55.2% discount to that internal fair value measure.
The P/E ratio compares the current share price to earnings per share and acts as a shorthand for how much investors pay for each unit of profit. For a biotech-focused business like 3SBio, which reports a net profit of CN¥8,270.6m and a high return on equity of 29%, this metric gives a quick read on how the market is weighing those earnings against its concerns about future revenue and profit trends.
3SBio screens as good value on several fronts, with its 3.9x P/E described as good value versus the estimated fair P/E of 8.2x and also versus both peer averages and the broader Hong Kong Biotechs industry. The current multiple is far below the peer average of 36.2x and well under the sector’s 17.3x level, which signals a very steep discount that the market may be applying to forecasts that call for annual revenue contraction of 17.8% and an average earnings decline of 42.7% over the next three years.
Result: Price-to-Earnings of 3.9x (UNDERVALUED)
Explore the SWS fair ratio for 3SBio.
Still, the sharp annual revenue and net income declines, along with recent share price weakness, could suggest deeper issues that may keep 3SBio’s valuation compressed.
Find out about the key risks to this 3SBio narrative.
Another view on 3SBio’s valuation
There is a second lens to stress test that 3.9x P/E. The SWS DCF model values 3SBio at HK$33.62 per share, which is well above the current HK$15.07 level and implies the stock trades at a large discount. If cash flows are this strong, is the market leaning too hard into those forecast revenue and earnings declines?
Look into how the SWS DCF model arrives at its fair value.
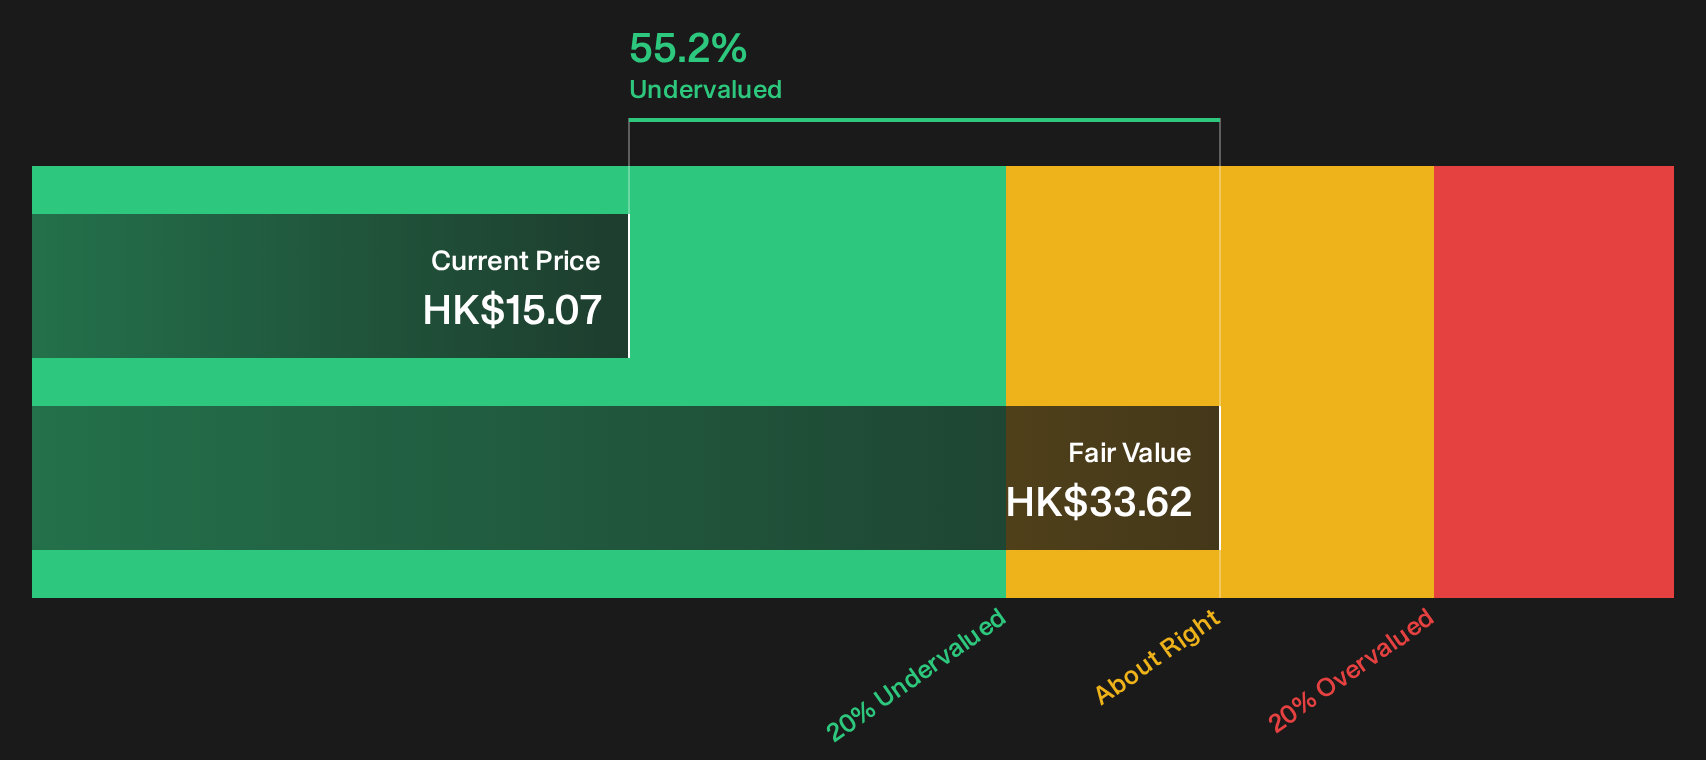
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 3SBio for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
See a disconnect between the MDR-001 story and how 3SBio is priced today. Act while the data is fresh, and weigh both the upside and the downside using the full picture in 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond 3SBio?
Do not stop with 3SBio. Broaden your watchlist by lining up fresh ideas that match your style before the next wave of opportunities gets crowded.
- Target potential mispricing and focus on quality by scanning our current pool of 174 high quality undervalued stocks that combine strong fundamentals with discounted valuations.
- Build a steadier portfolio anchor and stress test your income plan using a curated set of 223 dividend fortresses that aim for higher yields with resilience.
- Prioritise capital protection and support more stable outcomes by reviewing a hand picked group of 222 resilient stocks with low risk scores designed to keep volatility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com