
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Micron Technology (MU) Settles Netlist Patent Fight, Is The Stock Still Cheap?
Micron Technology (MU) just rewrote a long running legal story, signing a five year patent license and settlement deal with Netlist that clears all litigation tied to key memory technologies.
Recent price action shows Micron Technology giving back some ground in the last week, with a 7 day share price return of down 4.3% after legal headlines. The 90 day share price return of 5.1% sits against a very strong 1 year total shareholder return of more than 7x. This points to powerful longer term momentum, even as shorter term swings reflect profit taking and fresh attention on legal settlements, labor risks in Taiwan and record earnings tied to AI driven memory demand.
Scan how other AI infrastructure plays are reacting to the same crosswinds by reviewing the hand picked 92 AI infrastructure stocks alongside Micron Technology.
Micron Technology looks like a powerhouse on the business side after its legal reset and record results. The open question is whether the current share price already reflects that strength or still leaves a margin of safety.
Most Popular Micron Technology Narrative: 49% Undervalued
On the most widely followed view of Micron Technology, the narrative fair value of $2,018 sits far above the last close at $1,029. This puts that storyline firmly in undervalued territory and raises the question of whether the market is still treating this as a cyclical rather than an infrastructure stock.
Micron’s long-term profitability has shifted from a volume-driven commodity model to a value-driven enterprise model. The company''s primary profit pools are concentrated in its high-margin server, enterprise cloud, and data center memory divisions. By prioritizing fabrication capacity for advanced server DDR5, high-capacity solid-state storage, and specialized HBM3E modules, Micron can leverage its operating structures to achieve consolidated gross margins exceeding 70% during tight market cycles, isolating its financial performance from historical client PC volatility.
See why 132 investors see Micron Technology as 49% undervalued.
Result: Fair Value of $2,018 (UNDERVALUED)
Still, Micron Technology’s narrative leans heavily on flawless HBM4 execution and concentrated hyperscaler demand. Any packaging stumble or capex driven oversupply could flip sentiment fast.
Find out about the key risks to this Micron Technology narrative.
Another View: What The Cash Flows Say About Micron Technology
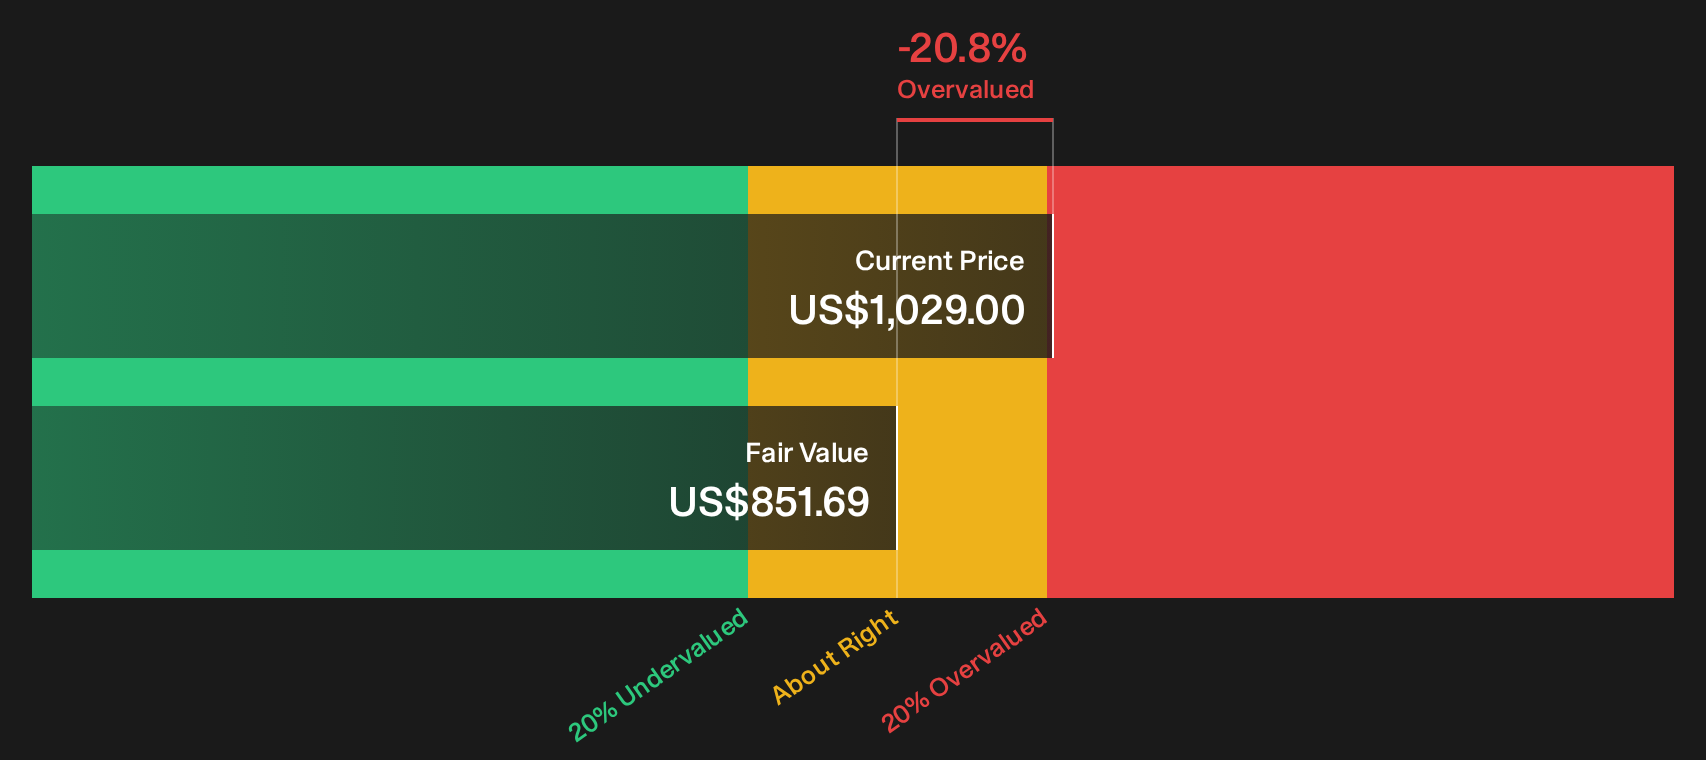
That popular Micron Technology narrative leans hard on a $2,018 fair value, but the SWS DCF model tells a cooler story. On those projected cash flows, fair value sits at $851.69, below the last close at $1,029. It frames less of a bargain and more of a debate. Which lens do you trust more: story or spreadsheet?
For investors who want to see exactly how that cash flow driven estimate is built, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Micron Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Micron Technology feels familiar, consider reviewing and testing the thesis using the detailed 4 key rewards and 3 important warning signs
Looking for more Micron Technology style investment ideas?
If Micron Technology has your attention, do not stop here. Broaden your watchlist with a fresh set of ideas built from powerful screeners.
- Target quality at a discount by scanning companies that pass strict valuation and fundamentals checks through the 28 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with strong finances and low risk profiles using the 31 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd by reviewing the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com