
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
2G Energy (XTRA:2GB) Lifted Guidance, Is The Stock Now Too Expensive?
2G Energy (XTRA:2GB) grabbed investor attention after management lifted its 2027 earnings outlook and, for the first time, laid out a revenue corridor for 2028, anchored by planned capacity expansion.
The raised guidance appears to have reset expectations. Despite a 7 day share price return that is down 6.78% and a 90 day share price return that is down 9.27%, 2G Energy still shows strong momentum, with a year-to-date share price return of 60.19% and a 1 year total shareholder return of 67.04%.
Compare 2G Energy's guidance-driven momentum with handpicked infrastructure-focused peers by scanning the 43 power grid technology and infrastructure stocks that could also benefit from rising demand for reliable energy systems.
The guidance reset is fresh, the share price has already risen sharply, and short term sentiment has just cooled. So does it make more sense to commit to 2G Energy now, or wait for a cleaner entry after the excitement fades?
Preferred P/E of 61.8x for 2G Energy: Is it justified?
The valuation bar for 2G Energy is set high. The stock trades on a P/E of 61.8x, while Simply Wall St's fair P/E estimate sits at 29.1x and the shares last closed at €57.75.
P/E compares what investors are paying today to the earnings the business is generating. For a manufacturer of decentralized energy systems like 2G Energy, a higher multiple often reflects confidence in forecast profit growth, especially when analysts expect earnings to grow 30.2% per year and revenue to expand 21.7% annually.
The question for you is whether that growth profile and the forecast Return on Equity of 26.8% in three years justify paying almost triple the peer group average P/E of 21.6x and more than double the European electrical industry average of 25.9x. The current valuation is well above the 29.1x fair ratio level the market could move toward if sentiment cools.
Explore the SWS fair ratio for 2G Energy.
Result: Price-to-earnings of 61.8x (OVERVALUED)
Still, the whole 2G Energy story can wobble if growth expectations ease or if competitors compress margins in decentralized power solutions.
Find out about the key risks to this 2G Energy narrative.
Another view on 2G Energy's value
The headline P/E of 61.8x paints 2G Energy as expensive, yet the SWS DCF model points the other way. On that cash flow view, the share price of €57.75 sits about 45.7% below an estimated value of €106.43, which is a sizeable gap. So which story do you trust more: the earnings multiple or the cash flows?
Look into how the SWS DCF model arrives at its fair value.
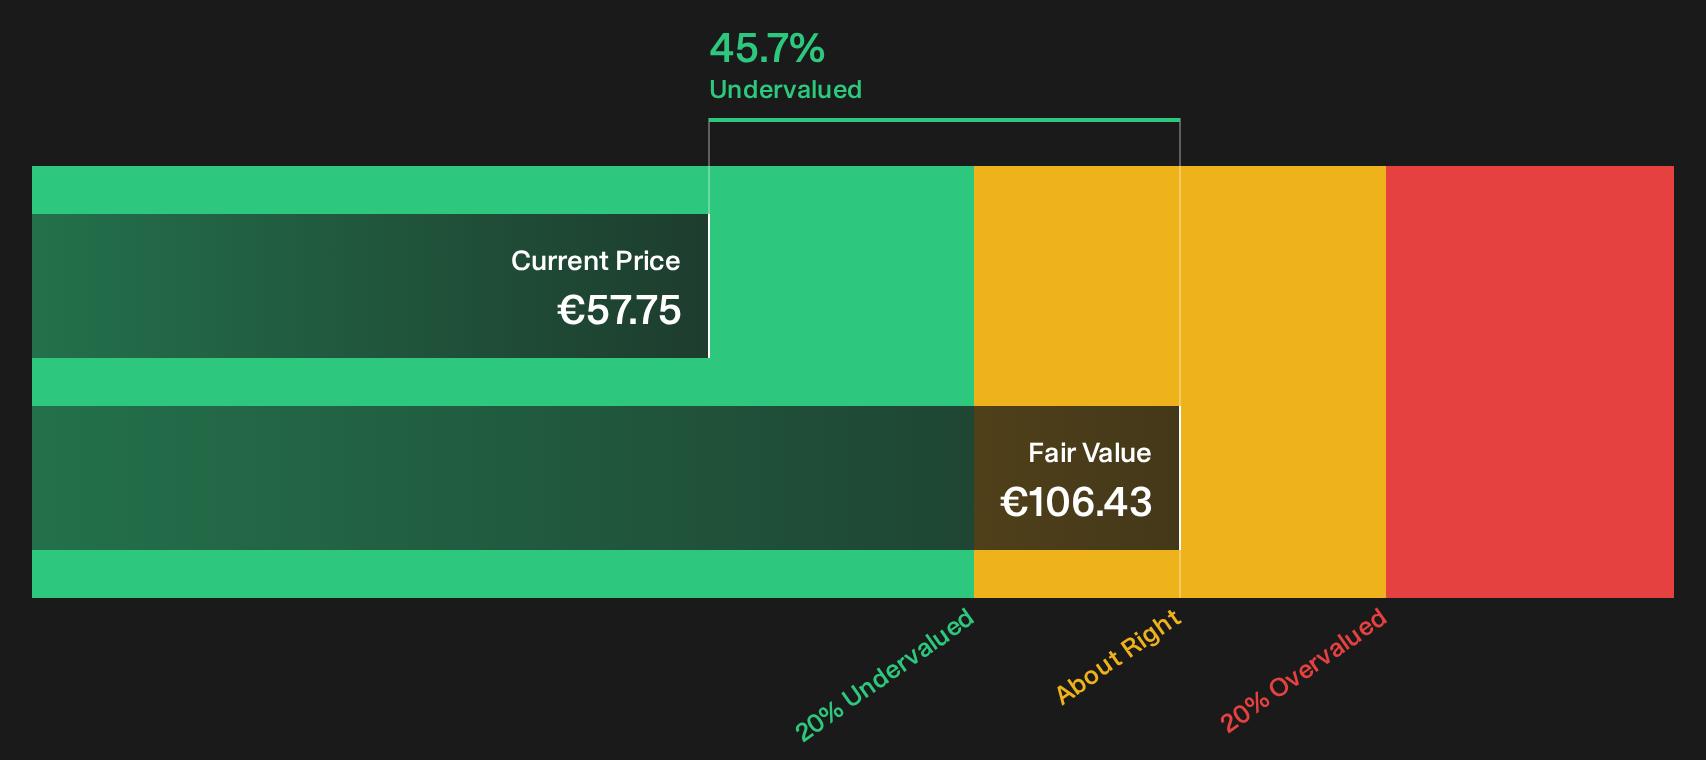
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 2G Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around 2G Energy is split, which is exactly why it helps to move fast, check the numbers yourself and decide where you land. To see both sides of the story in one place, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond 2G Energy?
If 2G Energy has sharpened your focus on quality and timing, do not stop here. Broaden your watchlist now and give yourself better options.
- Target resilient balance sheets and steady fundamentals by scanning a focused list of solid balance sheet and fundamentals (204 results), which can help you stress test ideas before committing capital.
- Hunt for potential value opportunities by reviewing the 174 high quality undervalued stocks, which narrows in on strong cash flows and quality metrics at more modest price tags.
- Build a shortlist of income candidates by checking the 223 dividend fortresses, which highlights higher yielding payouts supported by more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com