
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Texas Power Limits Might Change The Case For Investing In Prologis Stock
- Prologis recently faced uncertainty around its Hutto, Texas, data center project after state-level limits on new large power grid hookups raised questions about how and when the site can access electricity.
- The power constraint directly affects the timing and scale of potential rental income from this data center, which matters for how investors think about Prologis’s development spending, capital needs, and future cash flows from its broader logistics and infrastructure platform.
- This article examines how Prologis’s investment narrative is tested by the Texas data center power restrictions and the related timing of cash flows.
Prologis Investment Narrative Recap
To own Prologis, you need to believe its logistics and infrastructure platform can keep converting record leasing activity and a 17% mark to market opportunity into durable rent, while layering in data center and energy projects. The Hutto power cap tests that belief at the margin but does not change the core warehouse leasing story that still underpins most revenue.
The more immediate swing factor is how quickly signed leases and development deliveries show up in cash flow at a time when earnings are expected to edge lower and equity funding has recently been used. The biggest risk remains execution on growth that relies on capital intensive projects and potential dilution, not this single Texas constraint.
The most relevant recent thread is the cluster of institutional disclosures around Prologis in early October, including positions from Charles Schwab Investment Management, TIAA and Millennium. These filings show that a range of long only and hedge fund investors are actively sizing exposure while the SEGRO proposal, Hutto data center project and broader development pipeline remain in focus.
For you, the takeaway is less about who owns 1% and more about why institutional capital cares about timing of cash flows. Hutto highlights grid and permitting risk for the 5.8 GW data center pipeline. The SEGRO deal and record leasing volumes highlight the chance for higher rent and fee income. Execution on both sides will likely shape the next leg of the Prologis story.
What The Consensus Numbers Say About Prologis
Analysts are effectively telling you that the Prologis story only fully works if moderate revenue expansion and lower profitability can still justify a richer multiple on future earnings. The base case in the stock reports points to revenue increasing at 2.5% a year, with profit margins stepping down from 43.5% today to 35.0% within about three years. That combination means the business is modeled to get slightly bigger on the top line while earning less on each dollar of rent and fee income.
On earnings, the consensus pins Prologis at $4.2b today and $3.6b by 2029, which is a decline of $0.6b rather than an increase. Forecasts cluster between $4.1b on the high side and $2.9b on the low side, so there is real disagreement on how efficiently the development and acquisition machine converts into profit. For the Texas data center story, that uncertainty matters because any delay in grid access or lease-up feeds back into whether the lower margin profile ends up closer to the bullish or bearish end of that spread.
At the same time, the valuation framework in those reports leans on ambitious earnings multiples. To hit the consensus price target, Prologis would need to trade on a P/E of 52.8x those 2029 earnings, compared with 30.7x today and 25.9x for the broader US Industrial REITs group. In plain terms, investors paying up here are not just underwriting the Hutto site or even the 5.8 GW data center pipeline. They are also paying for the idea that this logistics and infrastructure platform can support a premium multiple even while modeled earnings drift lower.
For the capital structure, small but steady share issuance is baked into the spreadsheets. Analysts are using 0.45% annual growth in the share count over the next three years, on top of the already completed US$2.1b common stock raise in August 2026. For you, that means any cash flows from Hutto and other projects have to work harder just to offset dilution before they add anything to earnings per share.
Bring those numbers back to the data center power story in Texas and the broader grid exposure. A firm that is expected to see margins fall and profits shrink still carries a model that assumes $10.4b of revenue and $3.6b of earnings by 2029, supported by an 8.7% discount rate and a consensus price target of $158.23 versus a recent share price around $135.82. If power constraints slow how quickly data center rent comes through, the risk is not only timing on cash flow. It is also whether the market continues to accept a premium multiple on a business where the earnings trend in the spreadsheets already points lower.
Prologis' current consensus profile ties the Hutto project and wider data center push directly into this valuation bridge. The more grid and permitting frictions delay those cash flows, the more investors need conviction that logistics leasing, European expansion and fee income can still support the revenue growth, margin path and P/E expansion implied in the forecasts.
Prologis' narrative projects $10.4b revenue and $3.6b earnings by 2029. This assumes 2.5% yearly revenue growth and a $0.6b earnings decline from $4.2b today.
Uncover how Prologis' fair value indicates a 22% potential upside to its current price, which could narrow quickly if sentiment swings back toward logistics alone.
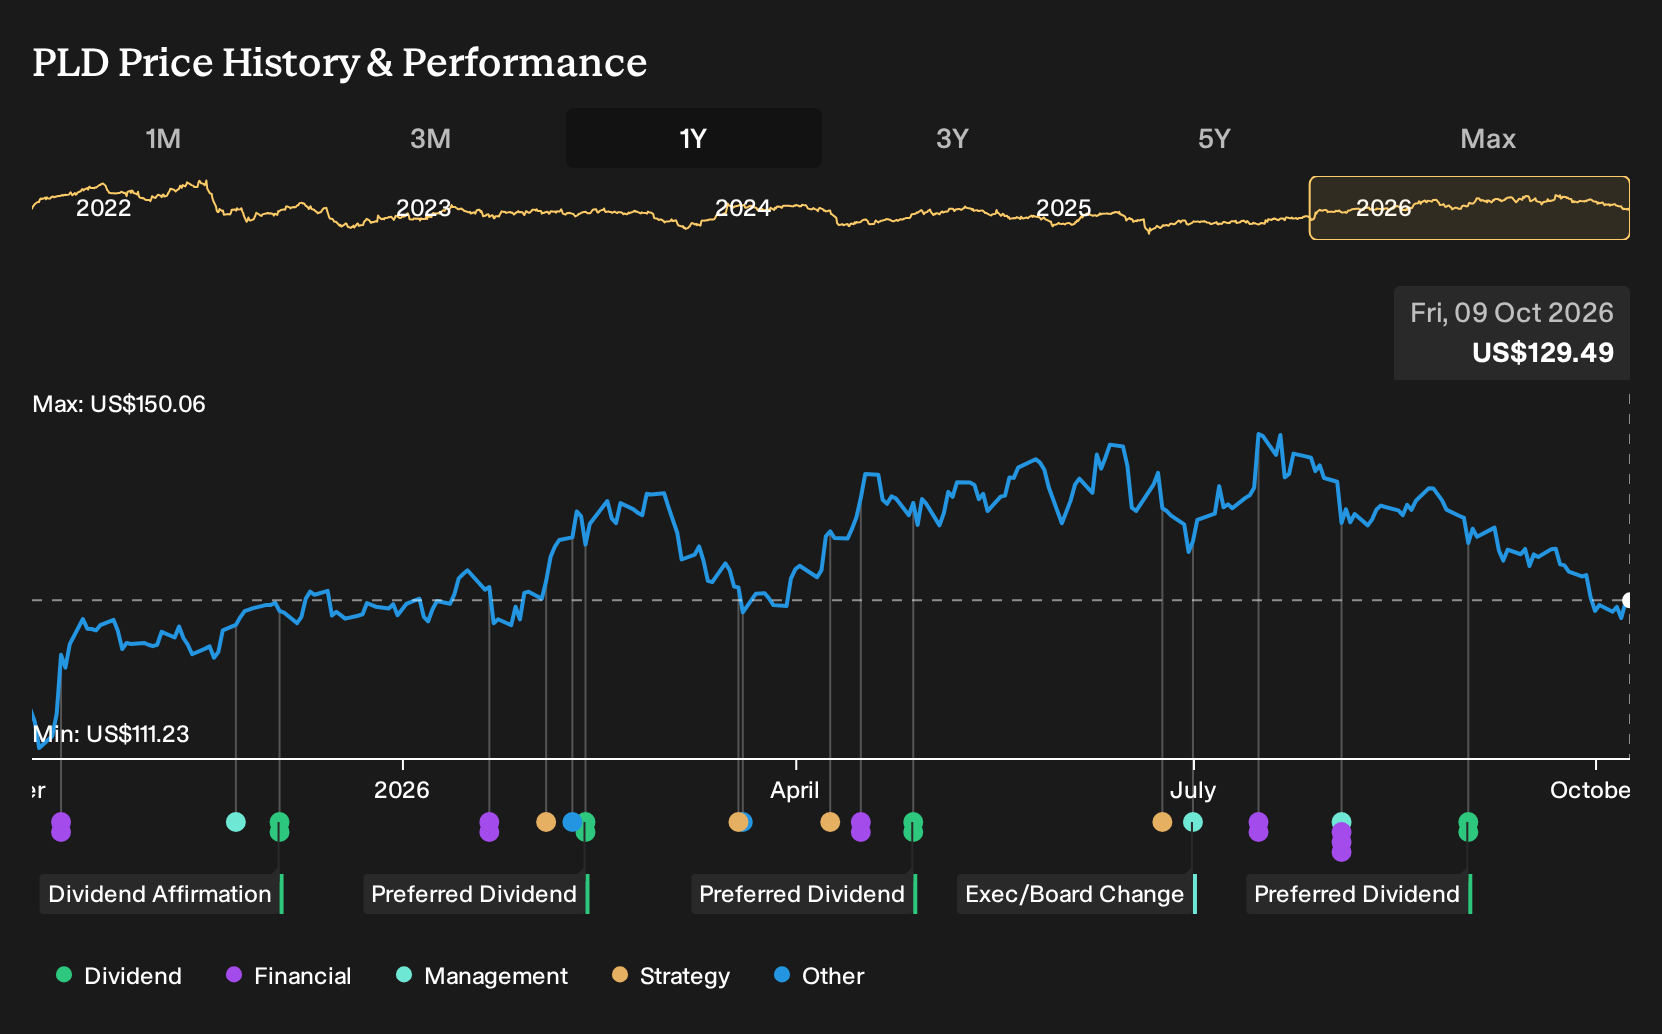
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$127 and US$158, with one view sitting close to the current analyst target for Prologis. Those opinions pre date the Texas power cap and SEGRO process. Use them as a reference point, then compare against your own read on grid risk, equity issuance and data center execution.
Explore 2 other Prologis fair value estimates, including one that suggests it could be worth just $126.95.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Prologis research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Prologis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prologis' overall financial health at a glance.
Looking For More Ideas Beyond Prologis?
If the Prologis story has you thinking about how different business models convert assets into long term cash flows, it can help to line it up against a wider watchlist built around clear, rules based filters.
- For income that aims to be both high and resilient, scan a set of companies with strong yields through 8 dividend fortresses and see which ones match your risk tolerance and payout preferences.
- If capital preservation is your priority, focus on resilience by working through 31 resilient stocks with low risk scores where the emphasis is on steadier balance sheets and lower risk scores.
- To look for future leaders before they are widely followed, review 20 high quality undiscovered gems and compare their fundamentals with the characteristics you like in Prologis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com