
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Trupanion (TRUP) Teams With Simon Cowell On Brand Push While Undervalued Narrative Faces A Test
Trupanion (TRUP) has teamed up with television personality Simon Cowell in a new awareness campaign around pet insurance. This marketing move could influence how investors think about the company’s long term growth prospects.
Recent trading has been choppy. Trupanion’s share price has climbed 10.52% over the past week and 5.08% over the past month to US$26.06; however, the year-to-date share price return is still down 29.95% and the 1-year total shareholder return has fallen 36.92%, hinting at improving short-term momentum against a weaker longer-run record.
Scan how Trupanion compares with other potential breakouts in pet and insurance related plays by reviewing the hand picked 20 high quality undiscovered gems that may still be under the radar.
After a sharp short term rebound, Trupanion now trades at US$26.06, while the average analyst target sits at US$33.25. How much of that gap looks like genuine upside versus misplaced optimism?
Most Popular Narrative: 24% Undervalued
Trupanion’s most followed narrative pegs fair value at $34.25, well above the last close at $26.06, which raises a simple question. Are investors being paid enough for the execution risks that sit between those two numbers?
Improved underwriting discipline, focus on higher lifetime value pets, and optimization of acquisition channels are driving higher-quality book growth and supporting strong free cash flow, setting up for scalable and more profitable expansion in coming years.
The moderation in veterinary care inflation, with Trupanion's pricing now catching up and a value proposition restored to target, should lead to more modest premium increases, aiding retention and lowering churn, thereby increasing customer lifetime value and supporting both revenue and earnings stability.
See why 6 investors see Trupanion as 24% undervalued.
Result: Fair Value of $34.25 (UNDERVALUED)
Still, the Trupanion narrative can crack if subscriber additions stay sluggish while competitors gain share, or if veterinary cost trends accelerate again and squeeze margins.
Find out about the key risks to this Trupanion narrative.
Another View: Trupanion Looks Expensive On Earnings
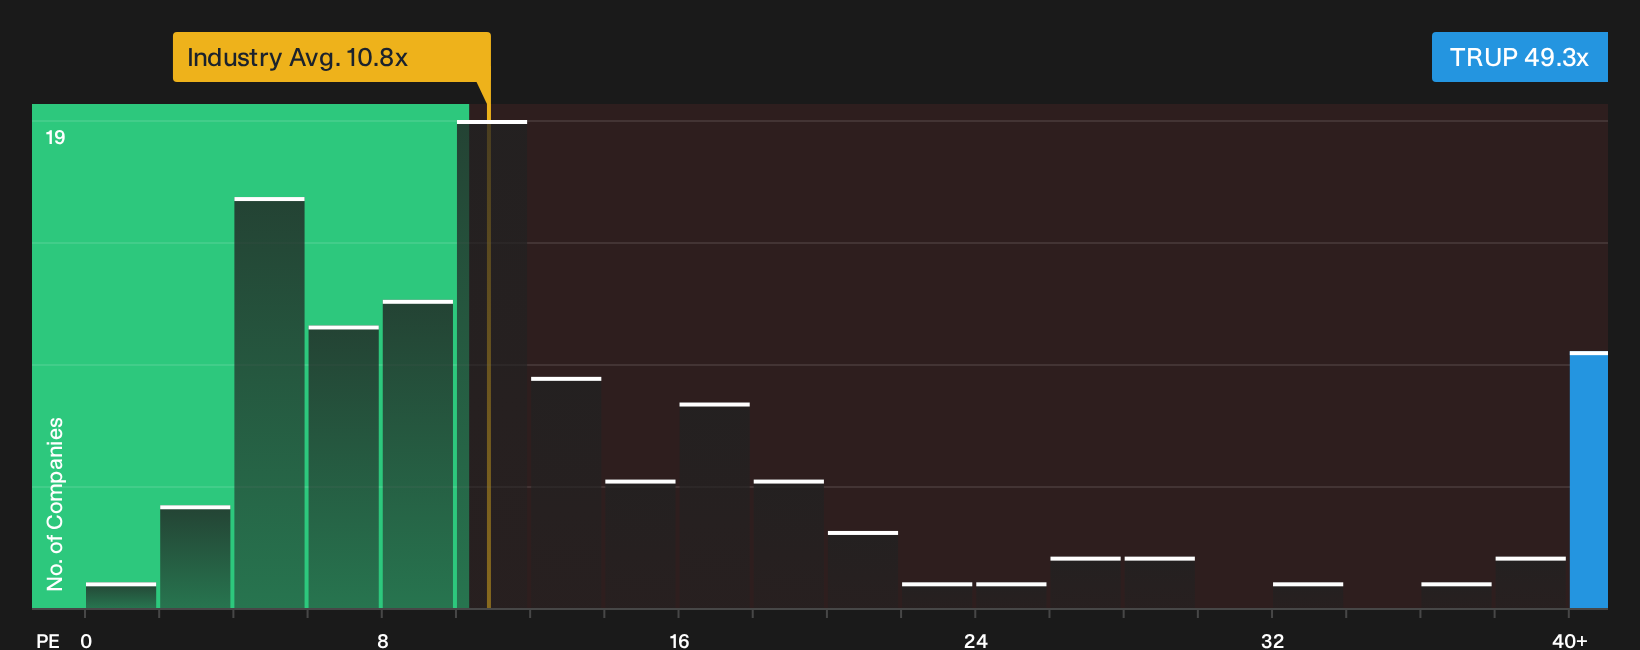
That $34.25 fair value narrative clashes with how the market currently prices Trupanion on simple earnings math. The stock trades on a P/E of 49.3x, compared with 10.7x for the wider US Insurance sector and 7.5x across its peer group. The fair ratio sits at 12.7x, which is less than one third of the present multiple and points to meaningful valuation risk if sentiment cools or growth expectations ease.
For anyone trying to square that gap between rich current multiples and a higher implied fair value, it is worth checking how the underlying assumptions stack up in the full valuation breakdown, including the fair ratio and peer comparisons in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Conflicted about whether Trupanion’s story represents more risk or opportunity right now? Consider acting promptly, review the underlying factors, then weigh the upside in 2 key rewards.
Looking For More Investing Ideas Beyond Trupanion?
If Trupanion has you thinking harder about valuation, do not stop here. Fresh ideas often come from comparing it with very different opportunities.
- Target higher upside potential in smaller companies by scanning the 14 elite penny stocks with strong financials that already show stronger financial underpinnings than typical micro caps.
- Hunt for quality at a reasonable price by reviewing the 28 high quality undervalued stocks that combine healthier balance sheets with cash flows supporting their current tags.
- Prioritize resilience first and excitement second by filtering for the 31 resilient stocks with low risk scores that score well on fundamentals and may help steady a concentrated portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com