
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OR Royalties (TSX:OR) Q3 Update Puts Its Undervalued Narrative Back In Focus
OR Royalties (TSX:OR) moved into focus after releasing preliminary third quarter figures, reporting $90.2 million in royalty and streaming revenue and 20,327 attributable gold equivalent ounces. This has drawn fresh attention to its earnings potential.
The preliminary third quarter update landed after a strong run in the share price. OR Royalties is now at CA$49.67, with a 90 day share price return of 19.74%, while the 1 year total shareholder return has declined 5.12% and the 5 year total shareholder return is up more than 3x.
Scan how OR Royalties compares to other miners showing strong fundamentals and recent momentum by reviewing the hand picked 36 elite gold producer stocks in one place.
For OR Royalties, the share price surge following those preliminary third quarter figures could signal that investors are warming to the underlying royalty portfolio, or reflect a shift in sentiment after a softer one year return. The valuation now needs a closer look.
Most Popular Narrative: 20% Undervalued
On the most followed view, OR Royalties carries a fair value estimate of CA$62.23 against a last close of CA$49.67. This frames the recent rally as investors moving toward, not away from, that narrative anchor. The key question is whether the royalty portfolio and balance sheet can support the cash flow story embedded in that gap.
Peer leading cash margins near 97% combined with a debt free balance sheet and roughly $1 billion of available liquidity enable disciplined capital deployment into high returning royalty and stream acquisitions, which can compound cash flow per share and underpin continued dividend growth.
See why 9 investors see OR Royalties as 20% undervalued.
The fair value estimate in that storyline uses a discount rate of about 7.99%, which is on the lower side of what many investors use for precious metals royalty businesses. It also leans on revenue growing around 15.7% each year and profit margins close to 68.9%, which is a high bar for any miner linked enterprise even with a royalty model.
Analysts behind this outlook are also baking in earnings of about $386.8 million by 2029 and a future P/E of roughly 26.5x on those profits. That multiple is above the 17.3x cited for the broader US metals and mining group, so the thesis depends on OR Royalties sustaining a richer valuation because of its portfolio structure and cash profile.
Earnings growth over the past five years of around 20.1% a year and a very large jump over the last twelve months give some context for why such a premium might be under discussion. At the same time, forecasts on this platform point to earnings expanding around 6.4% per year from here, which is slower than the Canadian market at 11.7% a year, so the long term story is not purely about rapid growth.
There are also moving parts around quality and risk that readers may want to weigh against that CA$62.23 figure. The business is flagged as having a high level of non cash earnings and all liabilities classed as higher risk funding, while the recorded return on equity of 19.1% is described as low under a 20% hurdle and is projected to be about 15.3% in three years.
Investors who place more emphasis on cash based metrics may prefer to focus on the SWS DCF model output instead, which suggests OR Royalties is trading at roughly a 38.2% discount to an estimated future cash flow value of CA$80.32 at the current CA$49.67 share price. That is materially lower than both the narrative fair value and the analyst consensus target and would represent a different way to frame upside and risk around the same business.
Result: Fair Value of CA$62.23 (UNDERVALUED)
Still, the OR Royalties story leans heavily on partner execution at assets like Canadian Malartic and on currently elevated precious metal prices, so setbacks in either area could quickly challenge the narrative that the shares are currently trading at a roughly 20% discount to estimated fair value.
Find out about the key risks to this OR Royalties narrative.
Another View: OR Royalties On Earnings Multiples
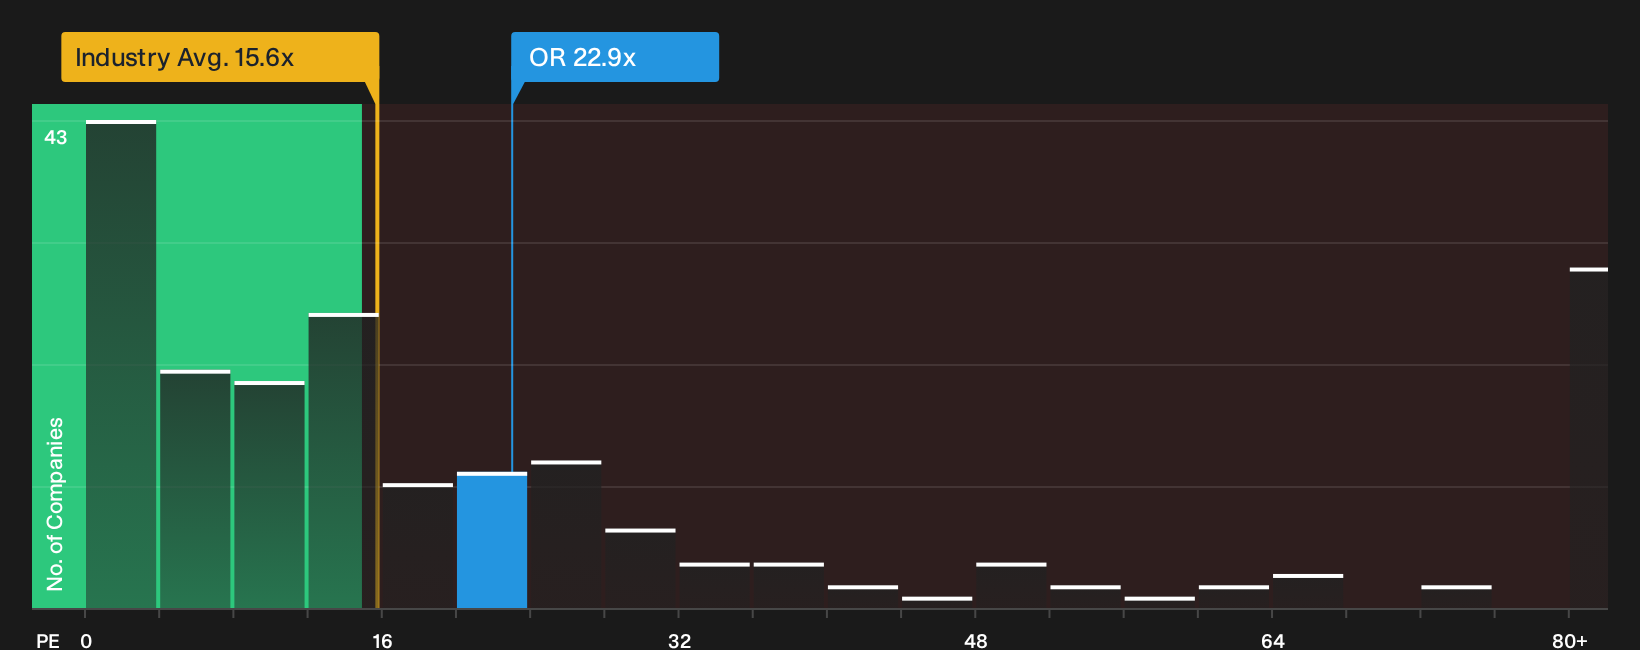
There is a different message when OR Royalties is viewed through its P/E ratio. The shares trade on 22.9x earnings, compared with 15.3x for the Canadian metals and mining group and 11x for peers, while the fair ratio sits near 14.6x, which points to a richer valuation that could compress if expectations cool.
That kind of gap can work either way in practice, since a premium multiple can shrink toward the fair ratio or the sector could move closer to OR Royalties instead. Investors need to decide which direction feels more realistic for their own playbook before leaning on this signal too heavily. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on OR Royalties so far. If the story feels incomplete, move quickly, review the underlying numbers and consider 3 key rewards and 1 important warning sign
Looking For More Ideas Beyond OR Royalties?
If OR Royalties has sharpened your focus, do not stop here. Broaden your watchlist now so you are not chasing opportunities after they move.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (7 results) that pair financial strength with underlying fundamentals.
- Hunt for potential mispricings through the 9 high quality undervalued stocks that highlight companies with strong cash flows and room for a re rating.
- Build a watchlist of potential outperformers early by checking the 9 high quality undiscovered gems that focus on quality businesses still off most investors radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com