
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Growth Stocks To Own In October 2026
AI related giants plan to pour more than $700b into new infrastructure this year and healthcare is one of the big testing grounds. That kind of spending shines a light on growth, not just size. For UK investors, it puts faster growing, financially solid companies on the radar. This article picks out three stocks from a high growth, financially healthy screener that analysts think can benefit from that focus on expansion.
The three stocks below are just a small sample, and the full screen surfaced 22 more companies with similarly strong growth stories that are not covered here. To identify and analyze those extra opportunities, head straight into the Healthy high growth potential screener.
Crimson Tide (AIM:TIDE)
Crimson Tide is a small UK software group built around mpro5, a field service management platform that helps service organisations digitise scheduling, inspections and compliance in real time, with a market cap of about £6.4 million.
Crimson Tide fits the Healthy high growth potential theme because analysts see very strong earnings expansion alongside a newly profitable SaaS platform, backed by fresh multi year public sector and APCOA contracts that support recurring revenue. There is one unresolved governance question that could influence how efficiently that growth is converted into margins.
That governance uncertainty is exactly why reading the analysis report for Crimson Tide can help you see whether Crimson Tide's earnings story is accelerating or stalling at the boardroom level.

ActiveOps (AIM:AOM)
ActiveOps sells cloud software that helps large banks, insurers and healthcare groups run back office teams more efficiently, with around £38 million from SaaS subscriptions and £7 million from training and implementation, and the stock is valued at roughly £161 million.
ActiveOps fits the Healthy high growth potential theme because its WorkiQ and ControliQ tools aim to increase output from existing staff. This is the kind of operational lift that can support earnings growth. The quote below describes how the link to AI driven decision tools could matter.
"ActiveOps is well-positioned to capitalize on the growing demand for AI-driven operational solutions, which could significantly drive revenue growth as organizations seek better decision intelligence tools."
What really moves the story from promise to outcome is how one pressure on future margins and profit conversion ultimately resolves.
That unresolved pressure is exactly what the full narrative for ActiveOps unpacks, separating short term noise from the areas where ActiveOps earnings momentum could realistically accelerate next.

RentGuarantor Holdings (AIM:RGG)
RentGuarantor Holdings runs an online rent guarantee platform for long term private rentals, charging subscription and transaction fees that tie directly into the Healthy high growth potential theme. It generated about £4.8 million from internet information services in the UK and carries a market cap of roughly £178 million.
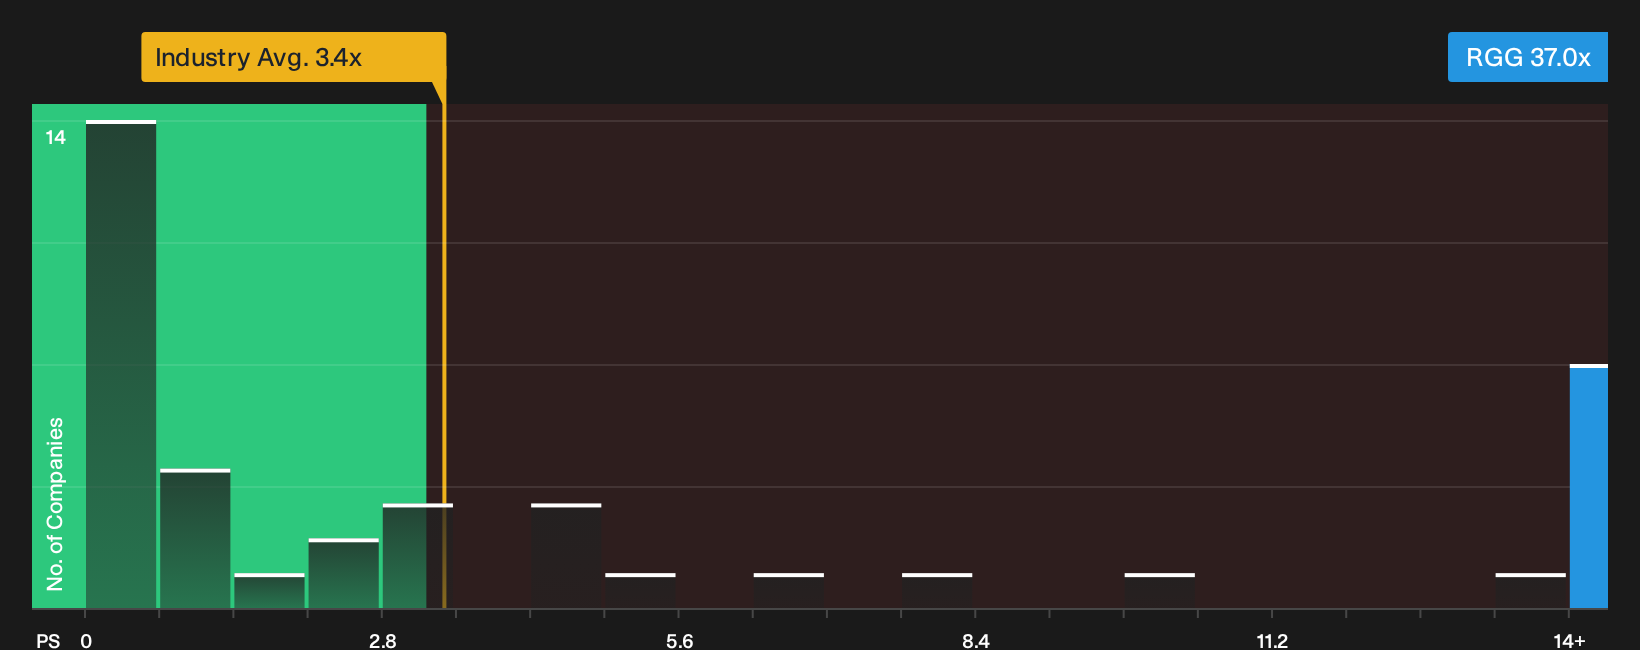
RentGuarantor Holdings lines up cleanly with the screener brief, with analysts expecting earnings to rise about 40.2% a year and revenue about 41.1% a year over the next three years from its scalable rent guarantee platform. Interest hinges on whether that rapid top line expansion can translate into the kind of margin profile that justifies such a rich P/S multiple if any unseen pressure on profitability were to shift at the wrong moment.
If that margin profile has you curious, go straight to the 3 key rewards and 3 important warning signs (1 is major!) to see what might be masking or accelerating RentGuarantor Holdings earnings power next.
Seeking Alternatives Before The Crowd
Fresh breakouts rarely stay quiet for long. Momentum builds, prices move, and late entries can end up chasing. Review curated ideas that may be under the radar for now and consider them before attention broadens.
- Look for potential income workhorses before yields are affected by additional capital flowing in with the 1 dividend fortresses.
- Track companies involved in AI infrastructure while prices are still adjusting and data centers are scaling through the 92 AI infrastructure stocks.
- Explore metals producers that could be positioned to respond if demand changes and supply remains constrained using the 33 best rare earth metal stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com