
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UK Germany Tech Corridor Could Matter For Siemens Stock (XTRA:SIE)
- Siemens has joined Allianz, Bosch and RWE in the recently agreed UK Germany Industrial Tech Corridor, which links fast growing technology firms with large industrial groups and government backed programmes for critical technologies, including new joint quantum computing and sensor research funding.
- By tying Siemens into cross border quantum and industrial tech partnerships with both governments involved, the corridor directly relates to its focus on digital automation and advanced infrastructure solutions.
- We will now look at how Siemens' role in the UK Germany Industrial Tech Corridor could reshape the existing investment narrative.
Siemens Investment Narrative Recap
To own Siemens, you need to believe its push into automation, digital software and critical infrastructure turns a large order book into steadier earnings despite uneven demand in areas such as China and Germany. The UK Germany Industrial Tech Corridor aligns with that thesis but does not suddenly change it.
In the near term, the key swing factor is whether Digital Industries and Smart Infrastructure can convert the €117b backlog into solid revenue and margins while integrating acquisitions and SaaS moves cleanly. The biggest risk remains soft capital spending and intense automation competition, which could keep pricing tight and order intake patchy.
The corridor news is closest to Siemens' broader pivot toward digital and software driven automation, including earlier moves into SaaS and industrial AI. That direction matters for investors tracking how much of future profit comes from higher margin, recurring software and services rather than lumpier equipment cycles.
Participation in UK Germany quantum and sensor programmes links back to that same operational question. Execution around complex projects, integration of new technologies into the Digital Industries stack and disciplined use of a high debt load will shape how effectively Siemens converts these partnerships into durable demand rather than just headline announcements.
Siemens' current analyst script points to revenues of €96.4b and earnings of €12.1b by 2029. That path assumes revenue growth of 5.9% per year and an earnings increase of about €4.2b from €7.9b today.
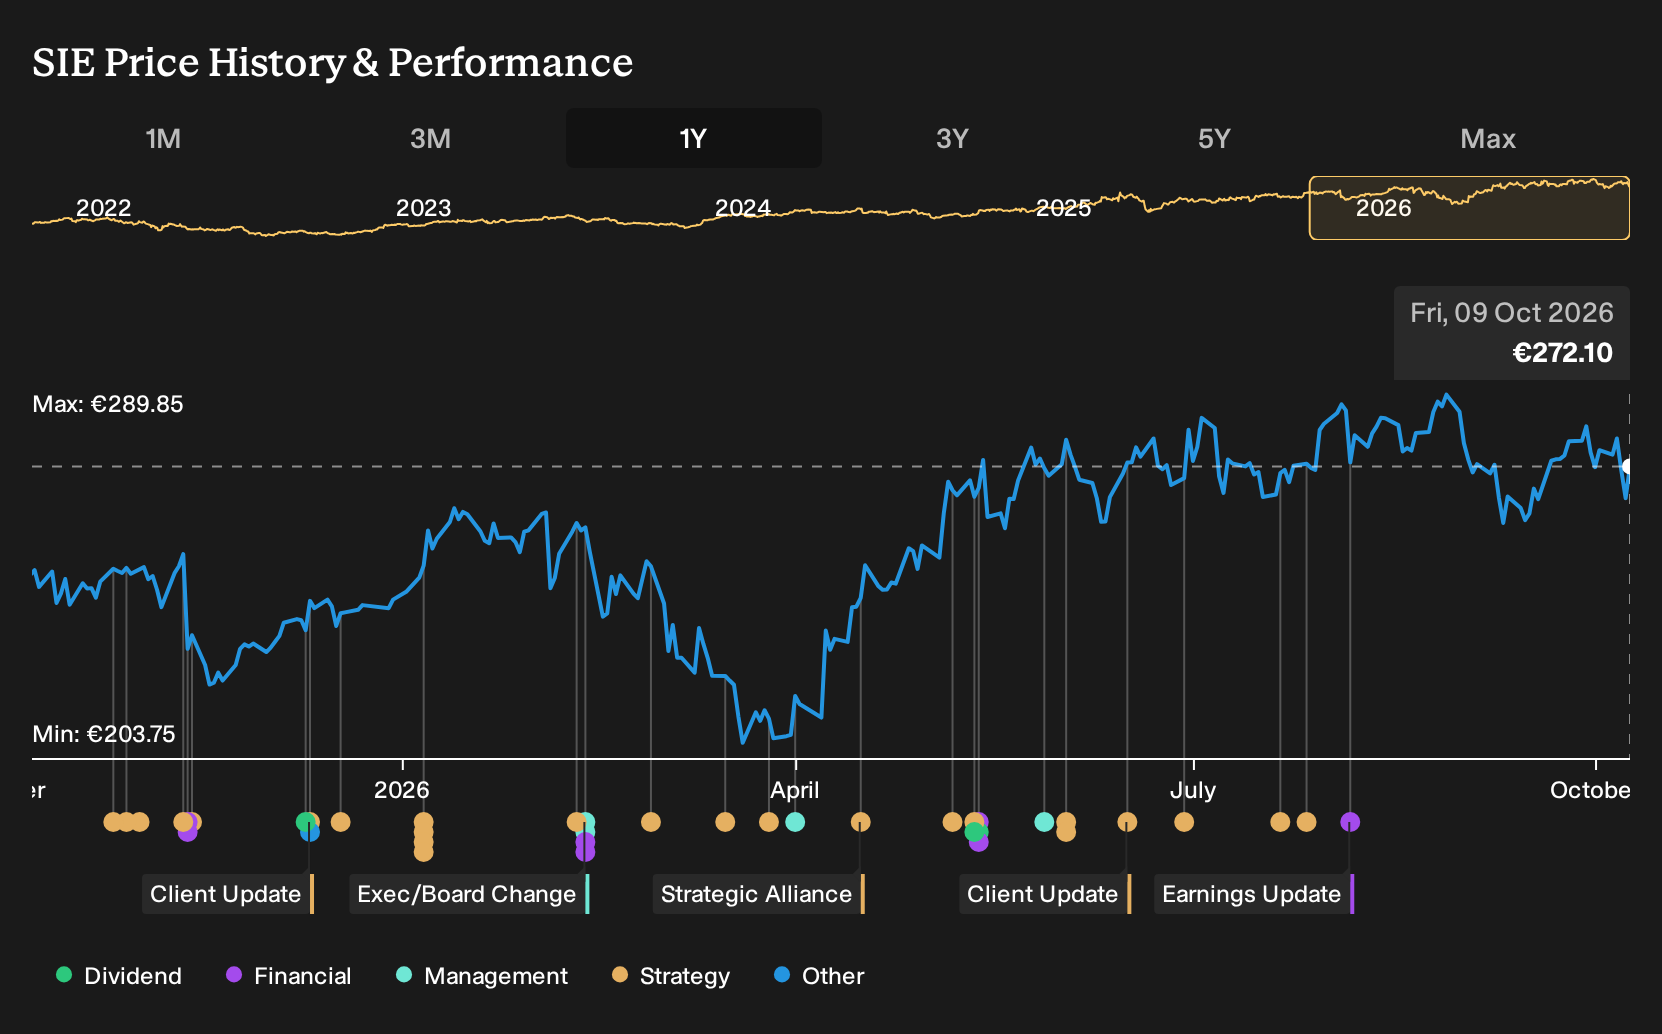
Uncover why Siemens' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view treats Siemens' push into data centers and AI projects as the key catalyst. The most optimistic analysts already pencilled in revenue of €111.1b and earnings of €13.2b by 2029 before this corridor news. You can read that as a much more upbeat story that might shift again as quantum partnerships evolve.
Explore 4 other Siemens fair value estimates, including one that suggests as much as 46% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own independent view.
- A great starting point for your Siemens research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siemens. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siemens' overall financial health at a glance.
Looking for more Siemens style investment ideas?
If Siemens joining the UK Germany Industrial Tech Corridor has you thinking about broader opportunities in related areas, it makes sense to widen the search using focused screeners that surface stocks with similar quality, balance sheet strength or income potential.
- If resilience matters most to you, start with companies that screen well on stability and risk using the 222 resilient stocks with low risk scores.
- For investors who want quality at a sensible entry point, review the 174 high quality undervalued stocks that combine fundamentals with a discount to intrinsic value estimates.
- If reliable income is on your checklist, focus on payout strength and consistency through the 223 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com