
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Paycom Software (PAYC) Is Getting Attention Today
Recent Price Move Puts Paycom Software In Focus
Paycom Software (PAYC) has caught fresh attention after recent trading left the shares at US$232.22. The move follows a strong past 3 months and a solid month, prompting investors to reassess what they are paying for its payroll focused platform.
The recent 1-day share price return of 1.01% and 7-day gain of 5.08% fit into a stronger trend for Paycom Software, with a 30-day share price return of 7.72% and a sharp 90-day move of 66.97%. This suggests that momentum has been building, even as the 1-year total shareholder return of 17.31% contrasts with weaker 3- and 5-year total shareholder returns, which remain in decline.
Explore other payroll and HCM companies showing similar momentum to Paycom Software by checking the curated 20 high quality undiscovered gems, which may still be flying under most investors' radar.
After Paycom Software’s sharp rebound, the share price now sits just above the average analyst target and far below one fair value estimate. Does the latest move leave the stock stretched or still discounted?
Most Popular Narrative: 7% Overvalued
Compared with the last close at $232.22, the most followed narrative pegs Paycom Software’s fair value at about $217.76. This frames the recent rally as running ahead of that model.
Automation and AI-driven product innovation, combined with Paycom's unified single database architecture, are driving salesforce productivity gains, increased client satisfaction, and higher client retention rates, which should meaningfully strengthen long-term net margins and future earnings stability.
See why 82 investors see Paycom Software as 7% overvalued.
Result: Fair Value of $217.76 (OVERVALUED)
Still, two weak spots could unsettle the Paycom Software story. Heavy AI and infrastructure spending that lingers, along with easier switching via open APIs, could both squeeze future profitability.
Find out about the key risks to this Paycom Software narrative.
Another View: Cash Flows Paint A Different Picture
The analyst narrative tags Paycom Software as about 7% overvalued at a fair value of $217.76, using earnings based assumptions. A different lens tells another story. Our DCF model estimates future cash flows point to a value near $457.03 per share, which implies the recent price could be materially lower than that cash flow based mark. Which anchor you trust more depends on how much weight you place on long term cash generation versus today’s earnings multiples.
For a closer look at how this cash flow view is built, including the moving parts behind that gap, Look into how the SWS DCF model arrives at its fair value.
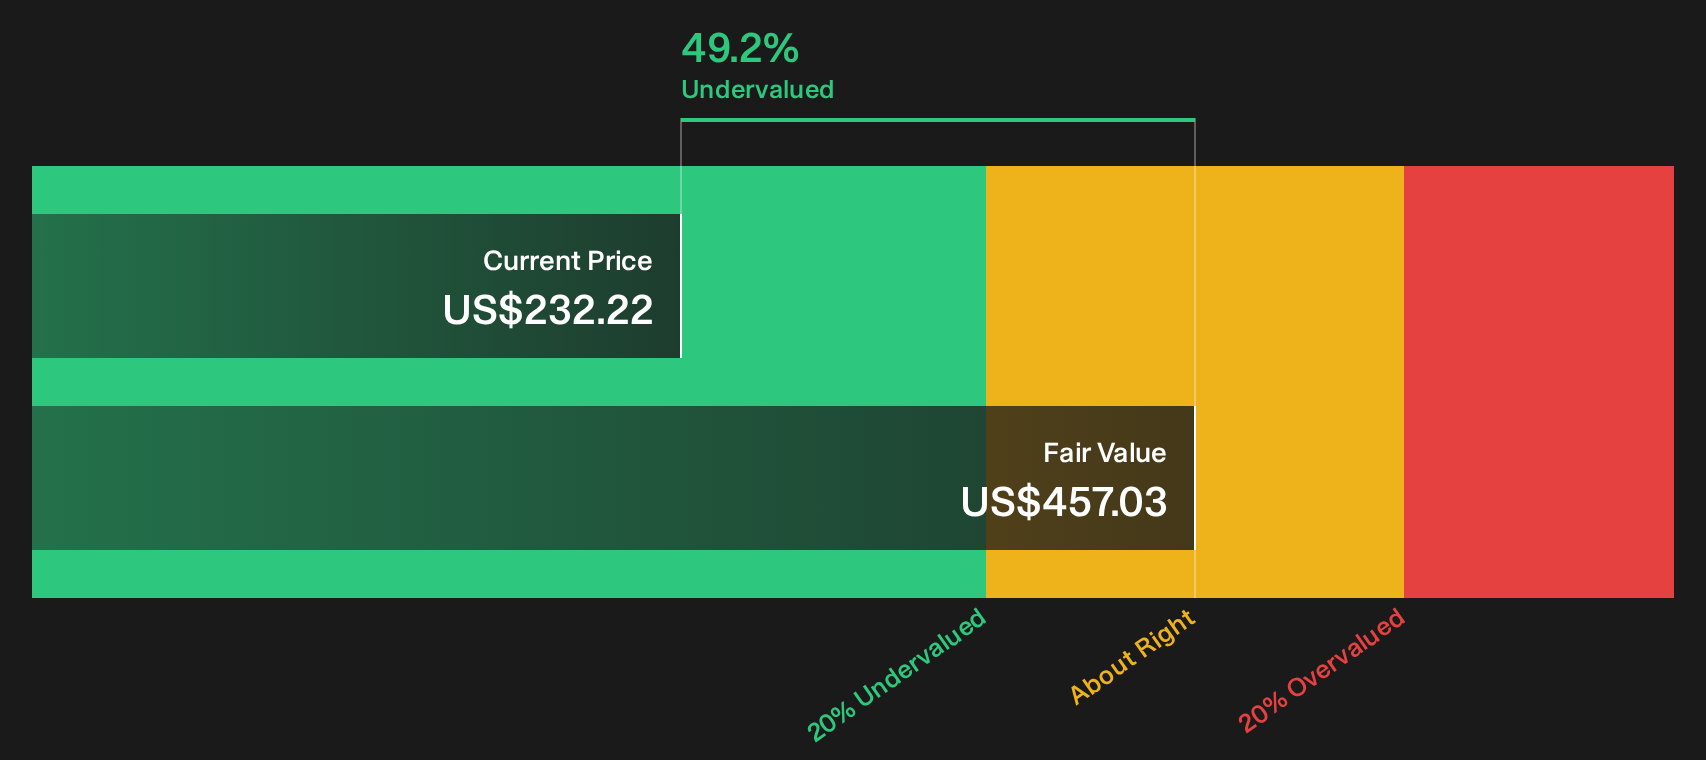
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paycom Software for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Paycom Software so far. Momentum, valuation models, and sentiment are all pointing in different directions, so move quickly and pressure test the assumptions that matter most to you with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Paycom Software?
If Paycom Software has sharpened your focus, do not stop here. Broaden your watchlist now with data driven shortlists that could reshape your next move.
- Spot potential mispricing early by reviewing a carefully filtered pool of quality opportunities through the 28 high quality undervalued stocks.
- Lock in income focused ideas by scanning companies that feature resilient payouts inside the 8 dividend fortresses.
- Sleep easier at night by concentrating on financially robust businesses surfaced in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com