
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Mitsubishi Materials Stock Sales Unit Merger
- Mitsubishi Materials has approved the creation of a new subsidiary to absorb the domestic cutting tools sales operations of both the parent company and its wholly owned unit MOLDINO Tool Engineering, with business succession and commencement planned for April 1, 2027.
- The move concentrates Japan cutting tools sales, related assets, and obligations into a single entity, targeting quicker decisions, tighter cost control, and more tailored proposals for local manufacturers.
- The focus now shifts to how Mitsubishi Materials' investment narrative could be reshaped by consolidating its domestic cutting tools sales decision making.
Scan how Mitsubishi Materials fits into the broader reshaping of industrial supply chains by reviewing a curated set of 43 power grid technology and infrastructure stocks that are also reworking their domestic sales models.
What Is Mitsubishi Materials' Investment Narrative?
Mitsubishi Materials asks you to believe in a fairly simple story. A diversified metals and materials group, with high quality earnings and a P/E of 6.6x compared with an estimated fair P/E of 14.8x, trying to squeeze more value from its industrial tooling and recycling footprint. The integration of domestic cutting tools sales into a single subsidiary fits that logic. Tighter sales execution, clearer accountability and quicker pricing decisions can matter a lot in a product set where volumes, mix and service support drive returns.
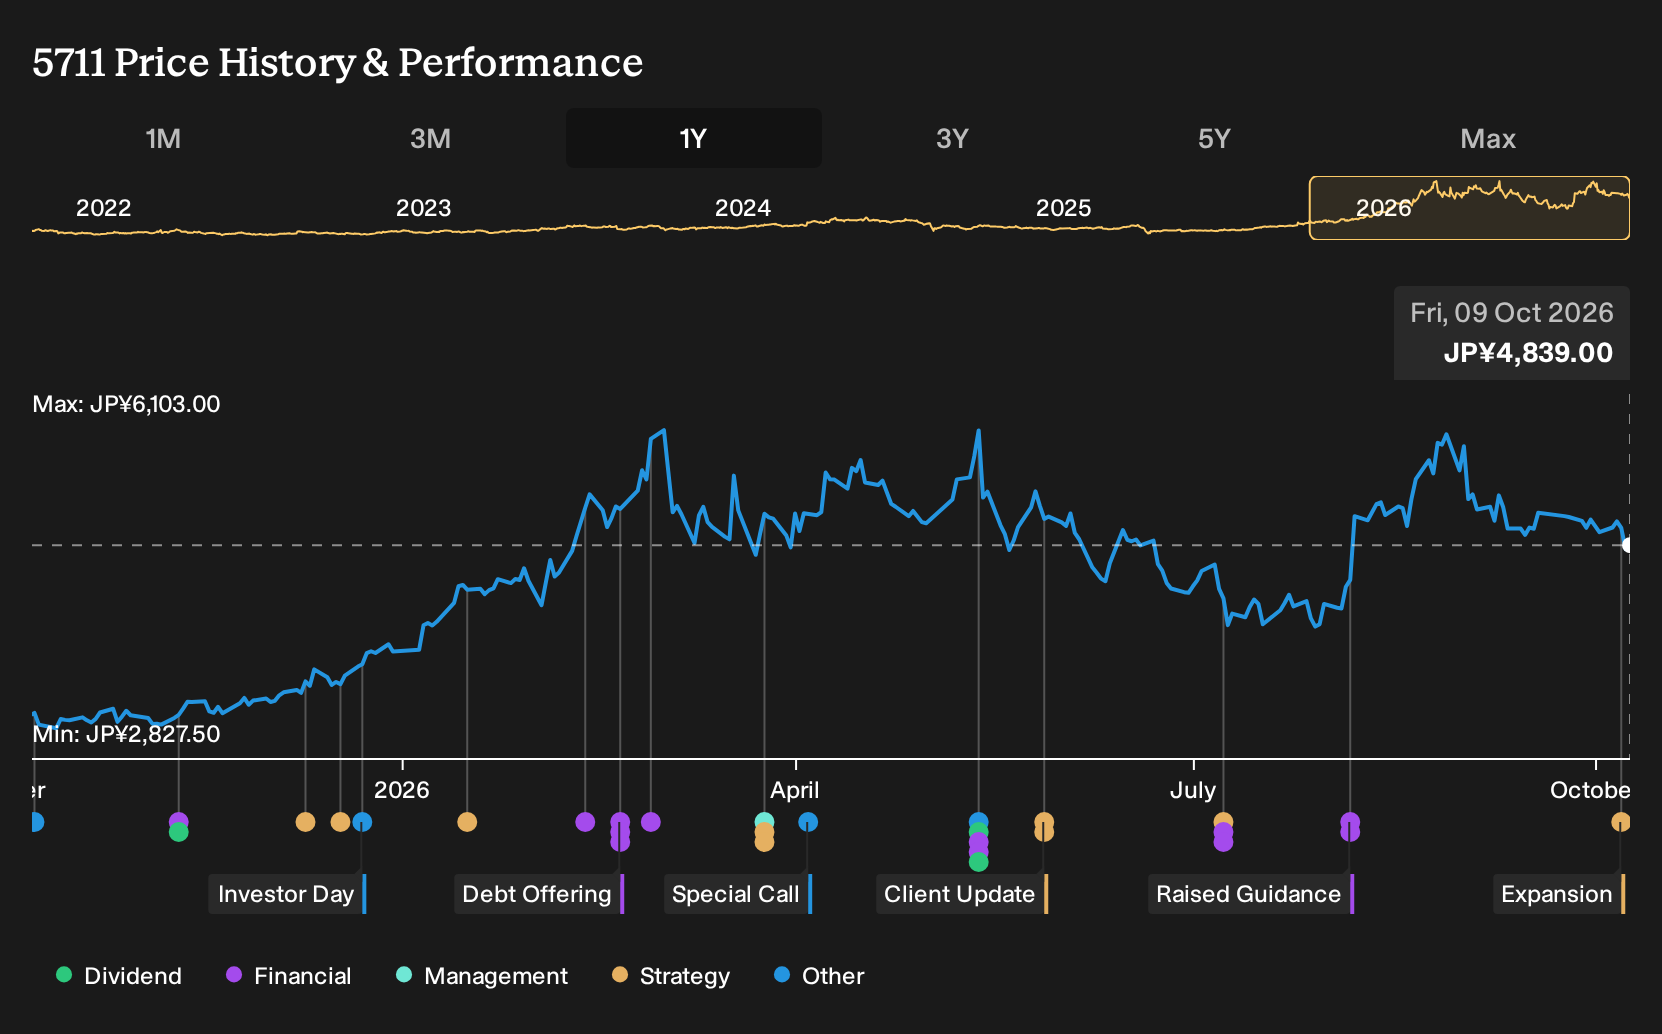
The near term swing factors still sit in execution and balance sheet discipline. Earnings have been very strong recently and the share price has climbed 72.4% over the past year, yet the stock remains flagged as highly volatile with debt not well covered by operating cash flow and a dividend that free cash flow does not fully support. The new subsidiary adds another layer of reorganization that could pay off in Japan, but also tests a relatively new management team and board that are still bedding in governance and capital allocation choices.
Even so, there is a specific pressure point in Mitsubishi Materials' story that could quickly matter a lot if conditions shift just a little too far...
There's only one way to know the right time to buy, sell or hold Mitsubishi Materials. Head to Simply Wall St's company report for the latest analysis of Mitsubishi Materials's Fair Value.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsubishi Materials research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mitsubishi Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond Mitsubishi Materials?
If Mitsubishi Materials has sharpened your interest in industrial and materials businesses, it can be worth widening the lens and seeing how other stocks stack up on different fundamentals using the Simply Wall St Screener.
- If you are hunting for quality at a reasonable entry point, scan for companies that combine stronger fundamentals with appealing valuations through the 12 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, filter for businesses with cleaner finances and sturdier capital structures using the list of solid balance sheet and fundamentals (23 results).
- If you are comfortable with higher risk in pursuit of outsized potential, sift through a curated group of smaller, higher octane opportunities with the 1 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com