
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oracle And 2 More Undervalued Stocks
Bond markets are stealing the show right now. The US 10 year Treasury yield recently moved near a 24 year high, which lifts borrowing costs and makes many investors wary of expensive growth stories. That kind of rate backdrop can leave some cash rich businesses trading for less than their long term cash potential. This article breaks down three such undervalued cash flow stocks from our screener.
The three stocks highlighted below are only a first cut from this idea, and the full screen surfaced 104 more businesses with equally compelling cash flow stories that are not covered here. To identify and analyze your own high conviction opportunities from this group, head straight into the Undervalued Stocks Based On Cash Flows screener.
Wintrust Financial (WTFC)
Overview: Wintrust Financial is a regional banking group centered on community lending and deposits, using those recurring cash flows to support specialty finance and wealth management services.
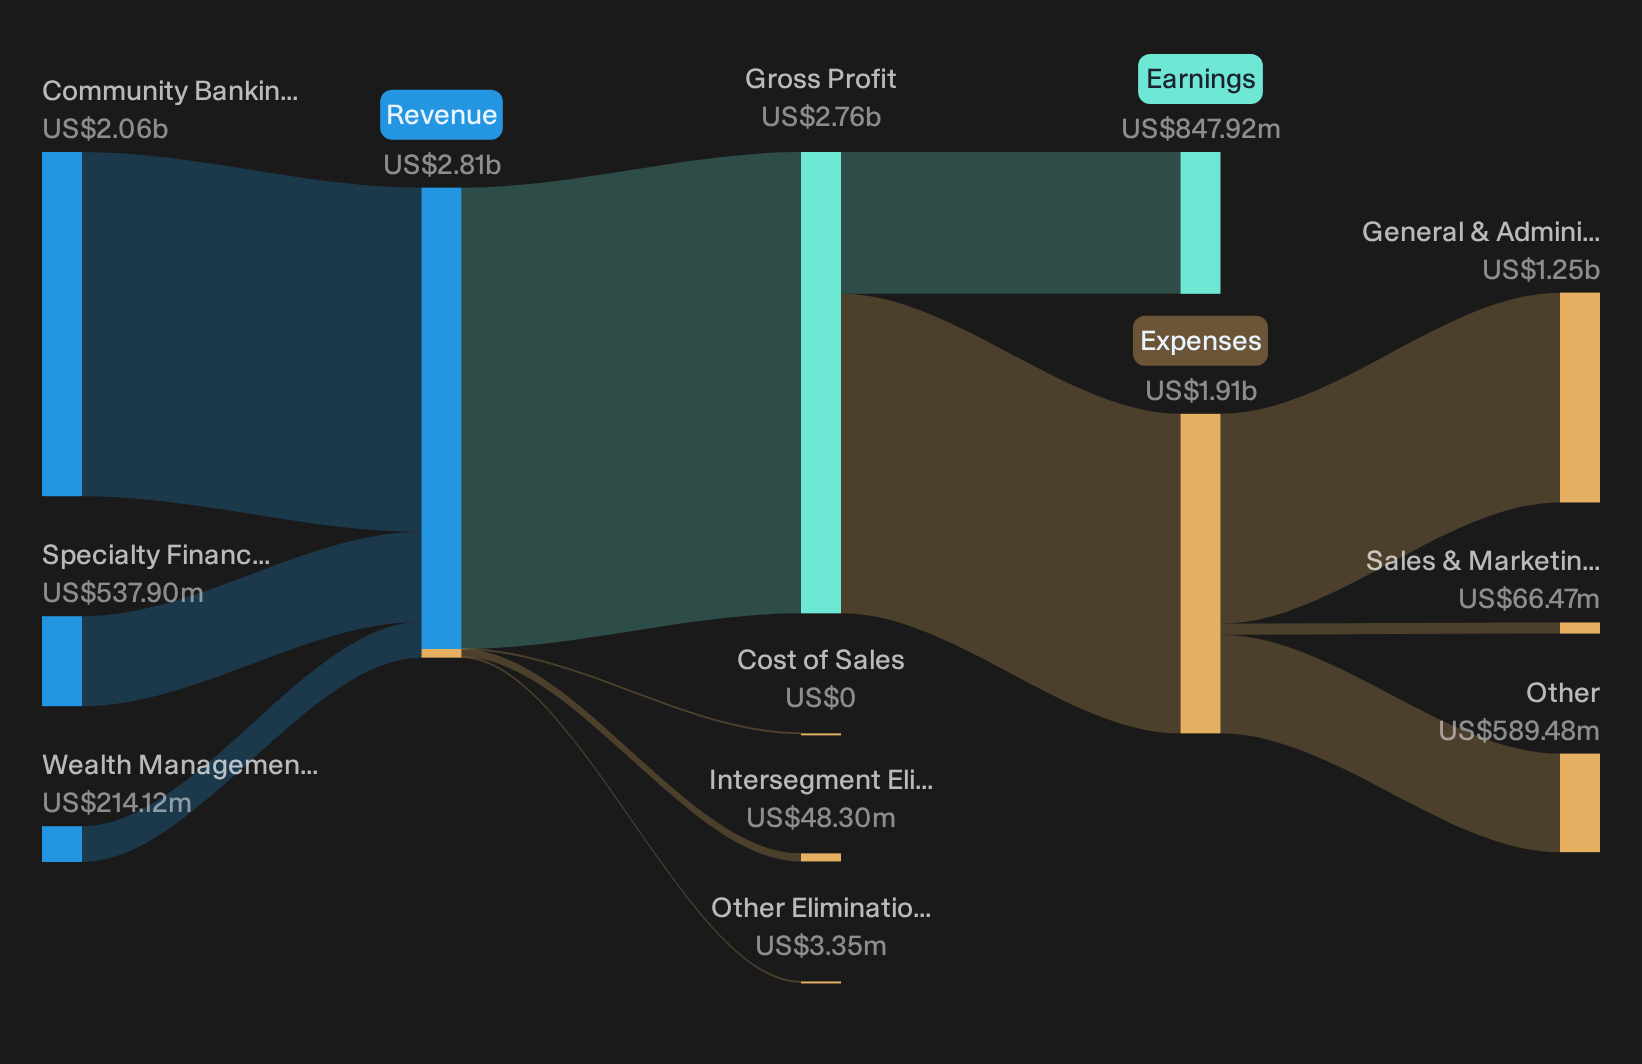
Operations: Wintrust generates about $2.1b from Community Banking, $538 million from Specialty Finance and $214 million from Wealth Management, primarily in the United States.
Market Cap: $9.7b
Wintrust Financial matters for this cash flow screen because its community banking engine produces recurring interest income that can be incorporated into discounted cash flow models.
"Organic loan and deposit growth across commercial, premium finance, mortgage and specialty lending segments is building a larger base of earning assets, which directly supports revenue and earnings."
The key variable is how ongoing pressure on funding costs and lending spreads ultimately shapes the cash flows that investors are pricing.
How that funding squeeze reshapes Wintrust Financial’s earning assets is at the center of the full narrative for Wintrust Financial, including how management is thinking about deposit competition and capital deployment.
Oracle (ORCL)
Overview: Oracle runs a broad suite of cloud software, databases and infrastructure that helps large organisations manage data, applications and recurring IT workloads worldwide.
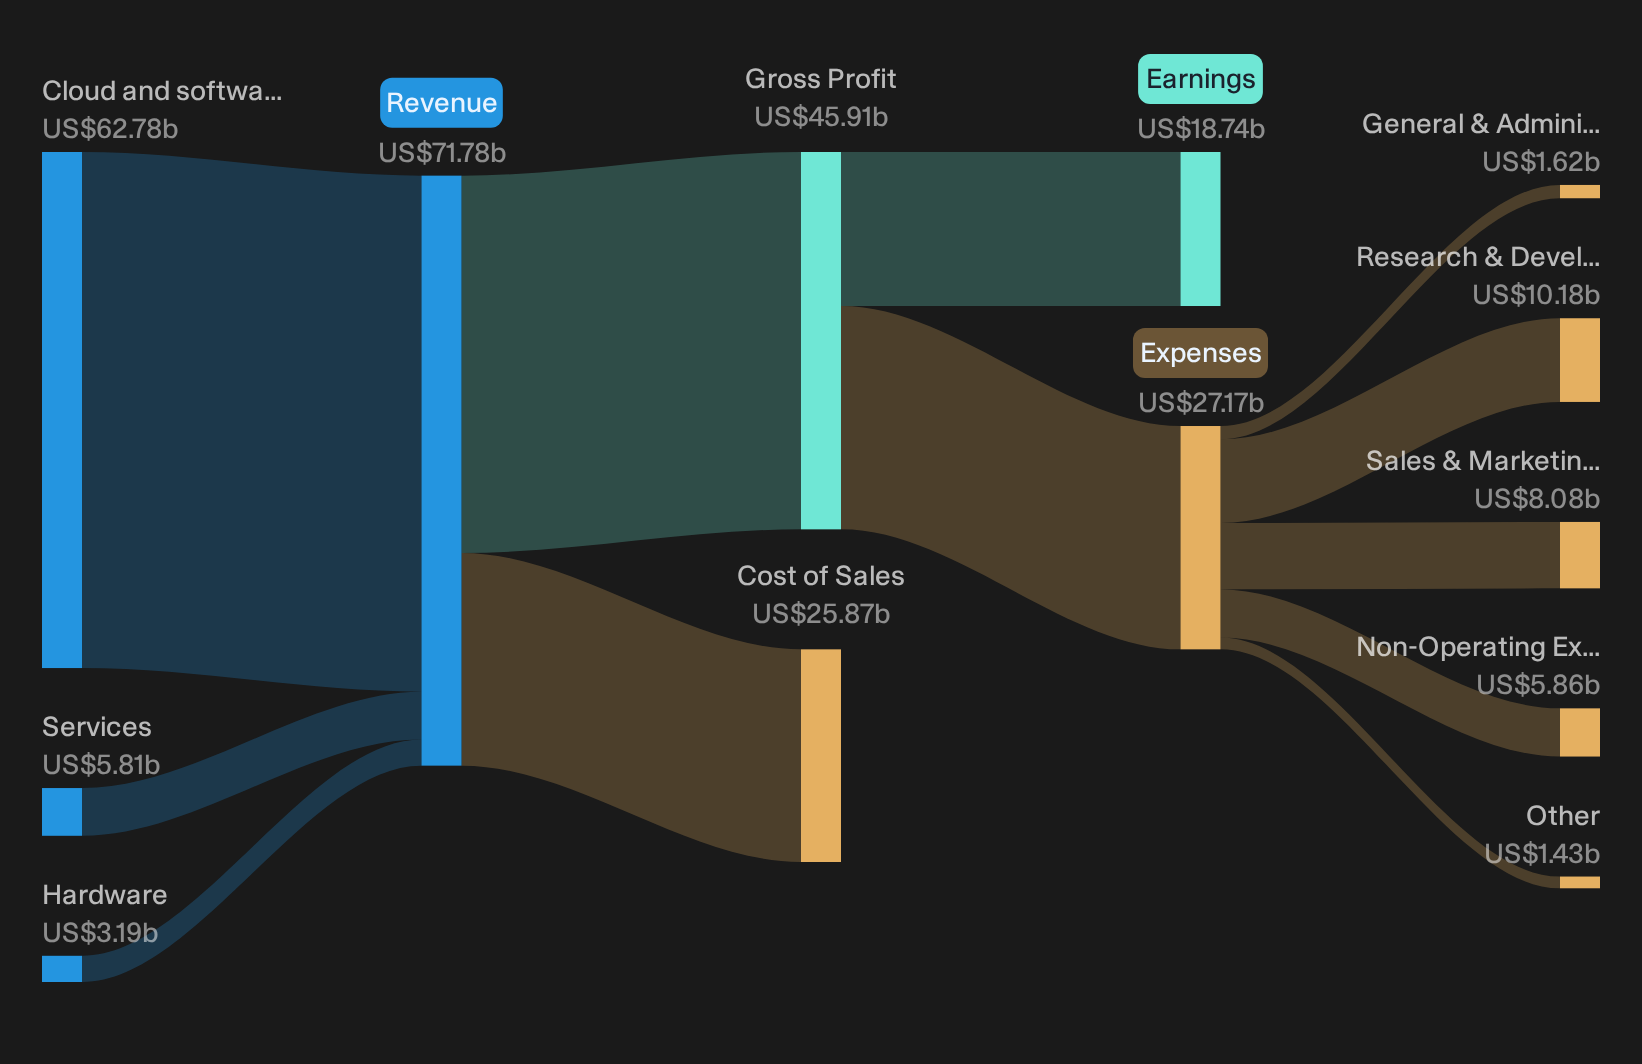
Operations: Oracle generates about US$62.8b from Cloud and software, US$5.8b from Services and US$3.2b from Hardware.
Market Cap: US$411.3b
Oracle matters here because its cloud subscriptions and Oracle Cloud Infrastructure turn long contracts into steady cash, which is exactly what this cash flow focused screen is built to surface.
"In 2024, OpenAI expanded its cloud footprint to include Oracle Cloud Infrastructure (OCI). This positioned OCI as a key extension of the Microsoft Azure AI platform and indicated that its Gen2 AI infrastructure could compete head to head with some of the largest hyperscalers on both performance and cost-effectiveness."
What happens to Oracle’s cash rich cloud story if one unseen pressure on funding that build out shifts direction?
If that funding backdrop really is the hidden swing factor, the full narrative for Oracle lays out how Oracle’s cash engine might accelerate or stall from here.
Netflix (NFLX)
Overview: Netflix runs a global subscription streaming platform for series, films, games, and live events, with recurring memberships driving its cash flow story.
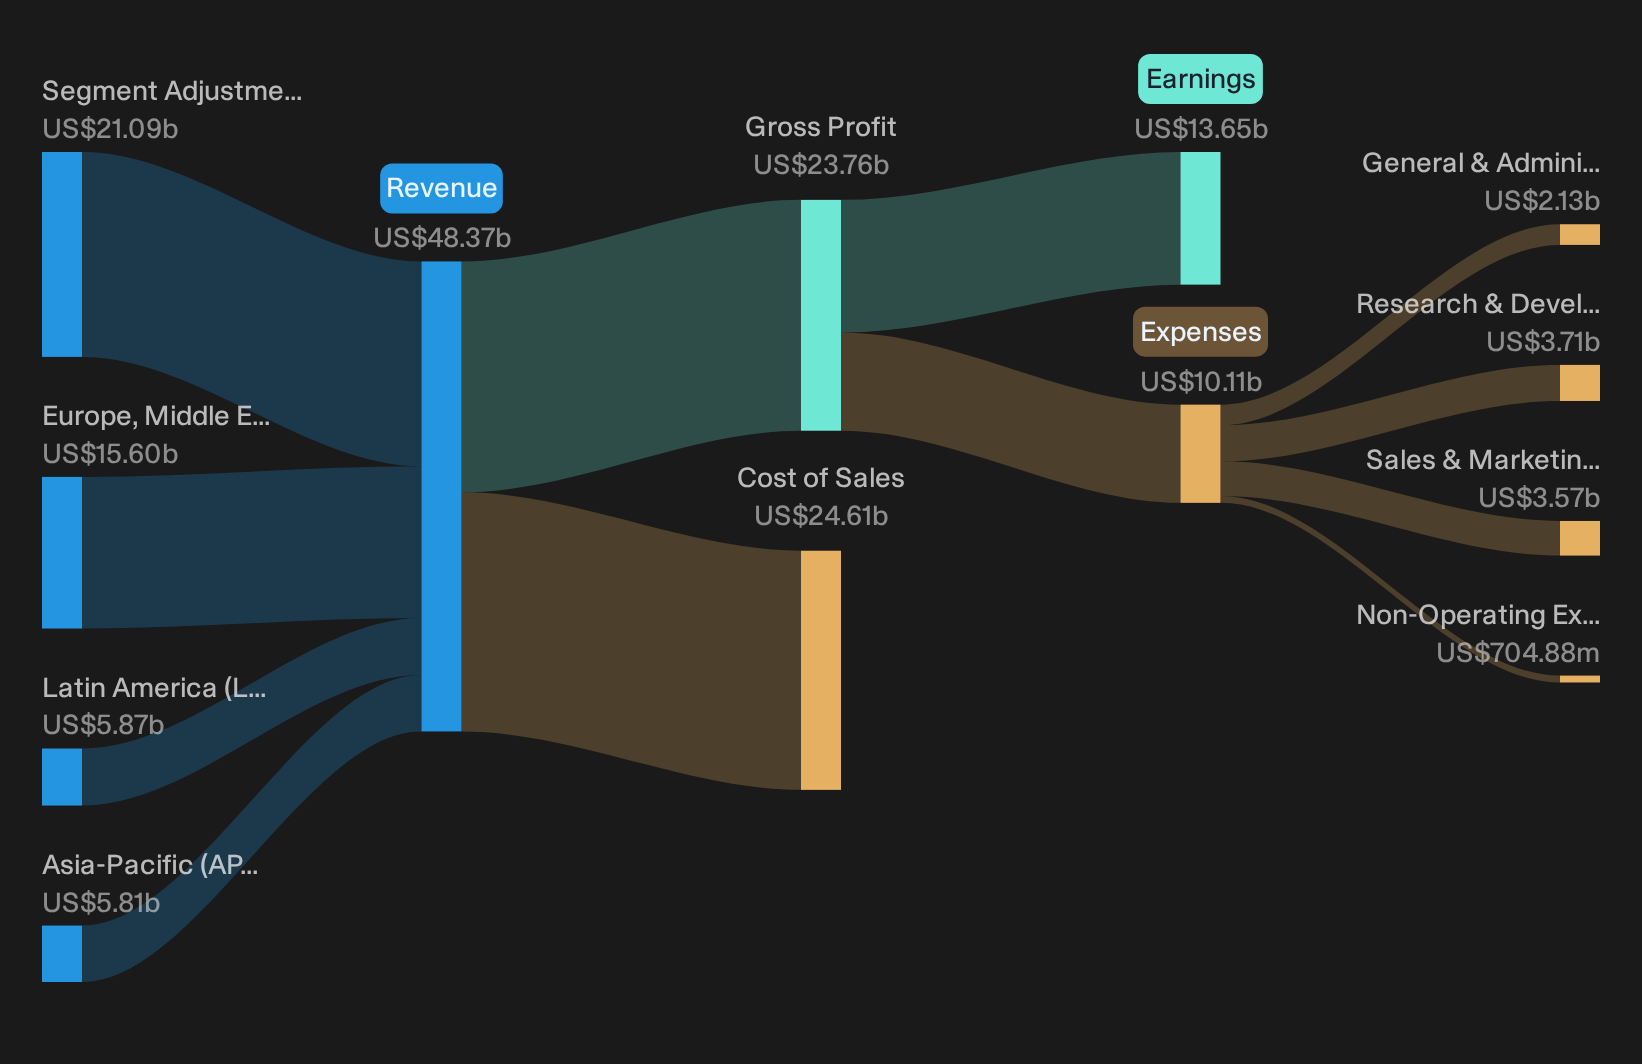
Operations: Netflix generates about US$48.4b from its streaming entertainment service, serving members across APAC, LATAM, EMEA and other regions.
Market Cap: US$298.0b
Netflix matters for this cash flow screen because paid memberships bring in predictable subscription money that can be fed into discounted cash flow models and tested against what the market is currently willing to pay for that stream of income.
"The bull case is still very real, but it needs more than a good quarter. It needs proof that ads become economically meaningful, that pricing remains sticky, and that margin expansion can continue without damaging engagement."
What happens if one quiet shift in how viewers actually use Netflix ends up deciding whether those future margins truly hold up.
That quiet shift is exactly what the full narrative for Netflix unpacks, highlighting where Netflix’s cash engine could accelerate and where engagement risk might still be masking potential areas of upside.
Seeking Fresh Alternatives Beyond These Three
Fresh ideas move first. Breakout stories can be caught early while momentum builds and prices are still dropping in quietly under the radar for now, so act now.
- Spot dependable income plays with real momentum and use the 8 dividend fortresses to see which yields might still be flying under most investors' radar.
- Track next wave automation winners before the crowd and scan the curated 91 robotics and automation stocks that could benefit from rising demand for smarter factories and logistics.
- Ride potential growth in resilient operators and review the hand picked 31 resilient stocks with low risk scores that balance steady balance sheets with room for upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com