
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is International Seaways (INSW) Fully Valued Following Its Zacks Upgrade?
Why International Seaways Just Hit Investors’ Radar
International Seaways (INSW) has moved into the spotlight after a Zacks upgrade to Rank #1, driven by higher earnings estimates and a stronger consensus view over the past 3 months.
Over the past year, International Seaways has delivered a very strong 1-year total shareholder return of 221.14%, supported by a 35.42% 3-month share price return and a 14.53% 1-month share price move, even though the latest session saw the share price slip 1.64% to US$119.82.
Scan the tanker space for other stocks with strong momentum and upgraded earnings expectations using our curated list of 28 high quality undervalued stocks that share some of International Seaways' appeal.
International Seaways has been a powerful performer, and the Zacks upgrade underlines that strength. Yet the latest price surge near the analyst target raises a simple issue: Are you paying up too far for that quality today?
Most Popular Narrative: 12% Overvalued
Against International Seaways' last close at $119.82, the most followed narrative fair value of $107.17 points to a premium that investors need to weigh carefully.
The analysts have a consensus price target of $107.17 for International Seaways based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of $110.24, the analyst price target of $107.17 is 2.9% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 57 investors see International Seaways as 12% overvalued.
Result: Fair Value of $107.17 (OVERVALUED)
Still, the narrative can unravel if global fossil fuel demand weakens faster than expected, or if tighter environmental rules push International Seaways' compliance and fleet costs higher.
Find out about the key risks to this International Seaways narrative.
Another View: What Multiples Say About International Seaways
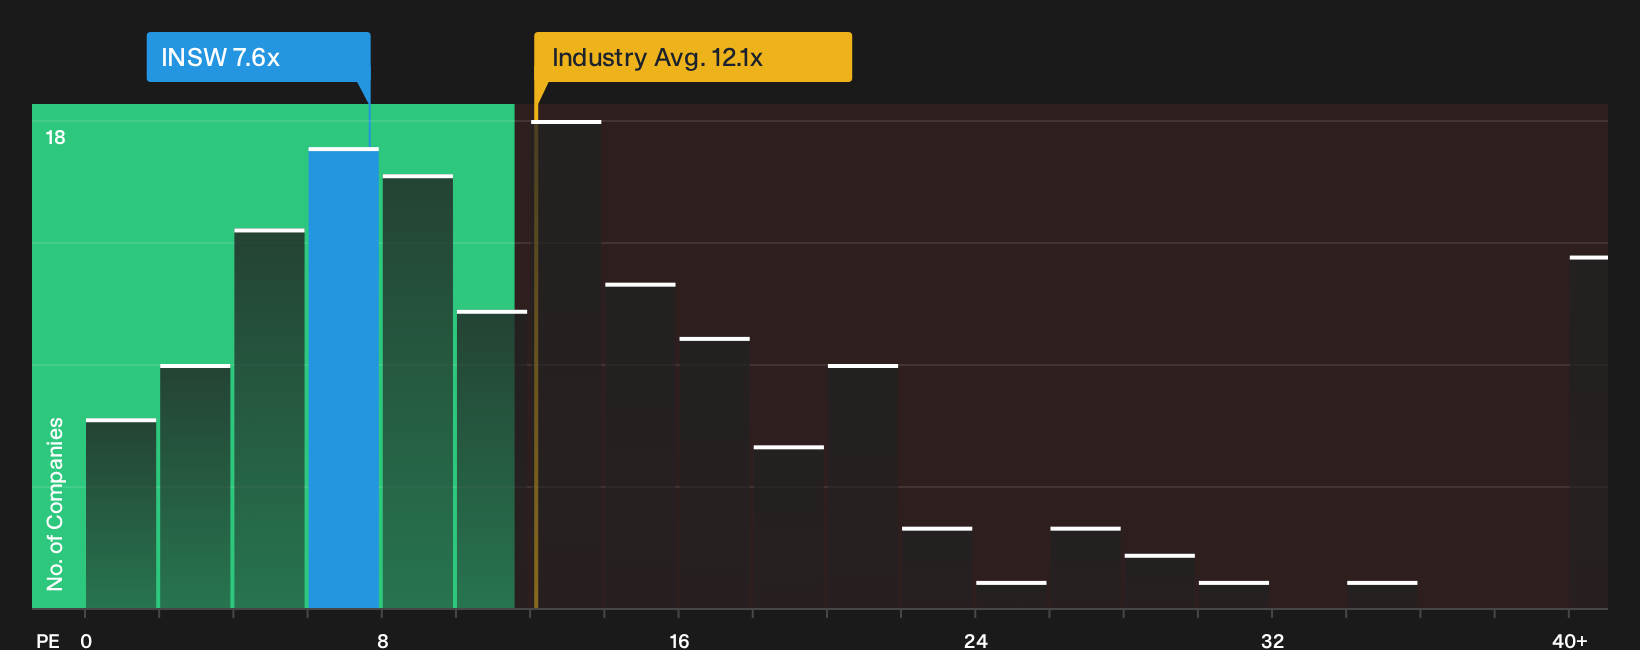
The analyst narrative pegs International Seaways as 12% overvalued at $119.82 versus fair value of $107.17. Yet on simple earnings terms the picture looks different. INSW trades on a P/E of 7.6x, while peers average 11.8x and the fair ratio points to 6.9x.
This mix of cheaper-than-industry but slightly richer-than-fair-ratio pricing suggests limited margin of safety if earnings fade and some upside if sentiment shifts back toward peer levels. Which side of that trade do you want to be on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on International Seaways so far. If you want to move quickly yet stay grounded in the facts, start with the balance between upside and downside in its 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond International Seaways?
If International Seaways has your attention, do not stop here. Broaden your watchlist now and give yourself more options when the next move comes.
- Target dependable income streams by zeroing in on payouts that look built to last using our 8 dividend fortresses.
- Hunt for quality on sale and line up potential bargains with strong fundamentals through the focused 28 high quality undervalued stocks.
- Prioritise sleep-at-night resilience by filtering for sturdier balance sheets and healthier metrics with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com