
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did AI And Space Launches Just Shift TD SYNNEX (SNX) Stock Narrative?
- TD SYNNEX has recently rolled out several major offerings, including a North America Space Tech Initiative, FinOps Fusion for AI cost management, and expanded AI driven PartnerFirst tools for resellers.
- These launches push TD SYNNEX deeper into higher value services around AI infrastructure and the space economy, shifting its role from pure distribution toward more data, software and training led engagement with partners.
- The focus now turns to how TD SYNNEX's AI and space tech initiatives could reshape its investment narrative and risk profile.
TD SYNNEX Investment Narrative Recap
To own TD SYNNEX, you need to believe its AI infrastructure and digital distribution engines can keep compounding while Hyve’s heavy working capital use and thinner AI server margins gradually become more manageable. The near term swing factor still sits in cash generation and margin quality, not just headline billings or EPS trends.
The new space and AI tools matter only if they translate into a richer service mix, better pricing power and steadier recurring revenue. If these initiatives scale slowly or remain niche, the biggest risk stays the same: strong reported growth paired with stretched cash flow and lower margin Hyve contracts.
The Space Tech Initiative is the clearest link between this week’s news and TD SYNNEX’s existing catalysts. It ties the company’s AI ready infrastructure, cybersecurity and SaaS catalog into a new vertical where partners often need bespoke integration, lifecycle services and training. That aligns with the push toward higher value engagement.
For investors, the key question is execution depth. Can TD SYNNEX and its partners turn training, Florida Tech ties and Space Prep visibility into repeatable IT workloads that support margins rather than just top line volume? If the answer is yes, this space push could complement Hyve driven AI demand with a differentiated, service heavy revenue stream.
What The Current Forecasts Assume For TD SYNNEX
Analysts sketch a fairly specific path for TD SYNNEX in the background of this AI and space push. Revenue is assumed to climb by 11.7% a year over the next three years, with profit margins moving from 1.7% today to 2.1% by 2029. On that view, earnings would rise from US$1.3b to US$2.2b by the 2029 forecast point, an increase of about 69%, while the share count edges lower as buybacks shrink outstanding stock by a little over 2% a year.
The same playbook underpins the current price targets. For the consensus to hold, TD SYNNEX would be generating about US$105.4b of revenue and US$2.2b of profit in 2029, trading on a P/E of 15.3x that is below today’s multiple and below the US Electronic industry average of 30.3x. That gap matters because it suggests the market is not baking in a premium for AI or space exposure, even though the analyst models already assume a richer margin profile and a steadier earnings base than the Hyve cash flow picture currently shows.
TD SYNNEX's narrative projects US$105.4b revenue and US$2.2b earnings by 2029. This requires 11.7% yearly revenue growth and roughly a US$0.9b earnings increase from US$1.3b today.
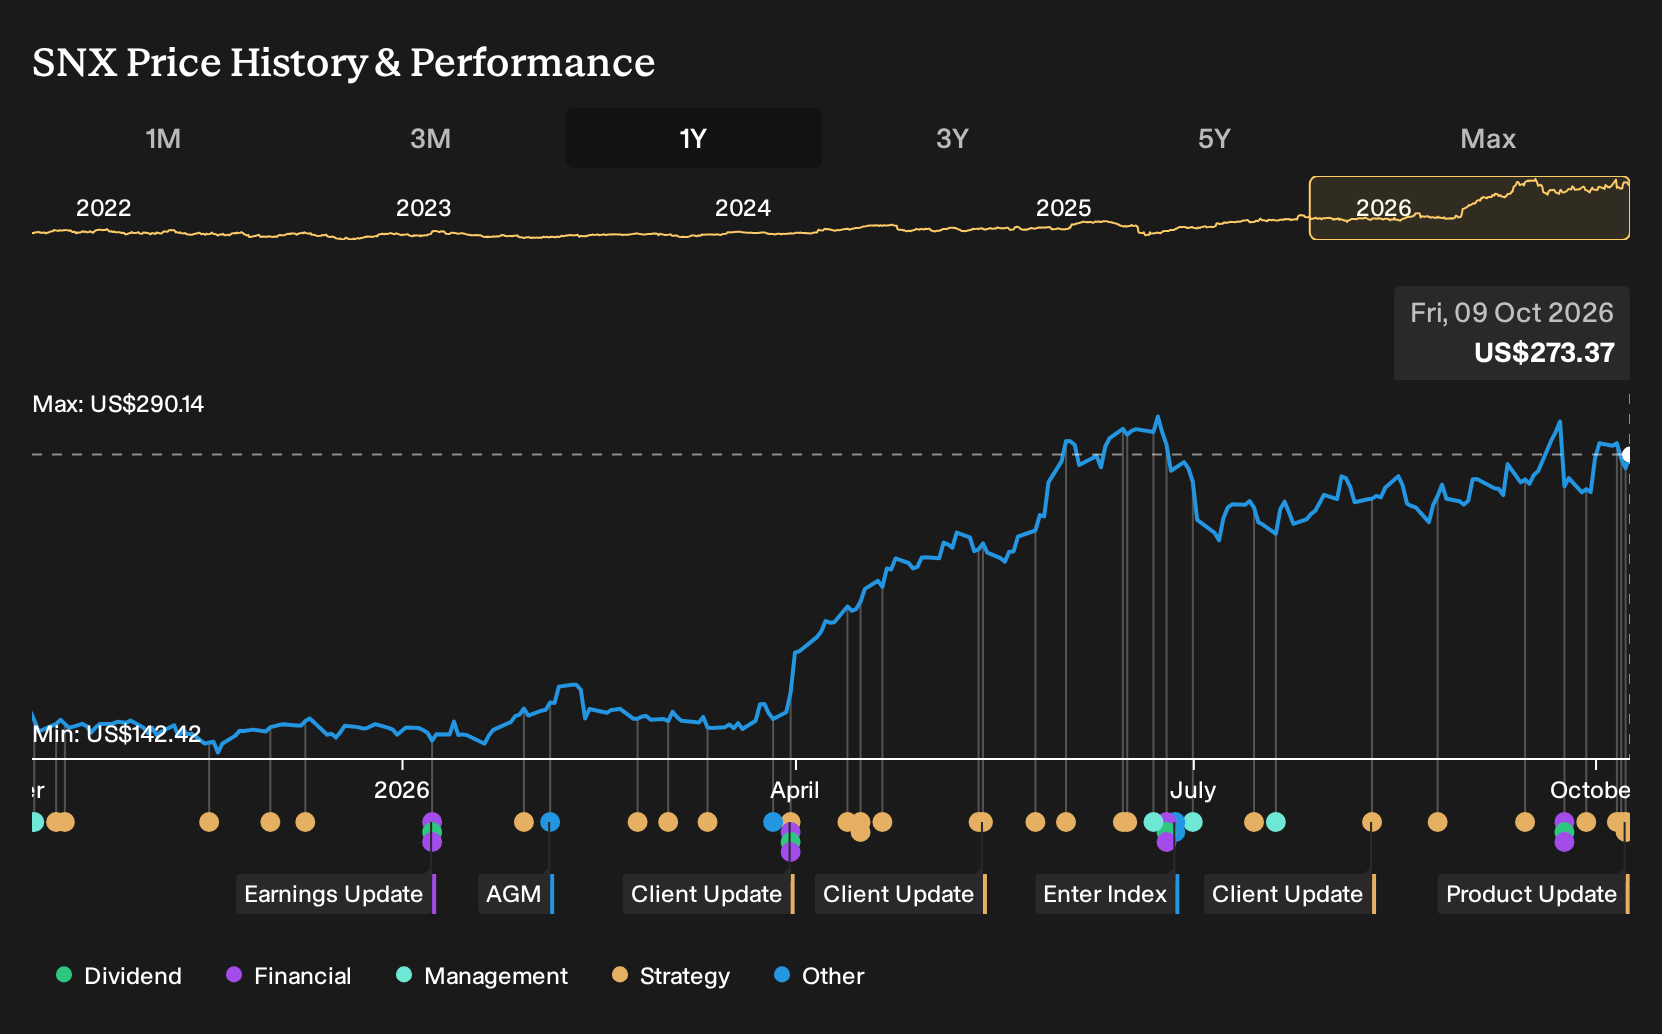
Uncover why TD SYNNEX's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Hyve concentration risk front and center for TD SYNNEX. The most bullish analysts still flagged reliance on two hyperscalers as a swing factor, even while pencilling in revenue of about US$97.9b and earnings near US$1.7b by 2029. Those figures were set before this week’s space and AI launches, so opinions may evolve.
Explore 2 other TD SYNNEX fair value estimates, including one that suggests as much as 92% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your TD SYNNEX research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TD SYNNEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TD SYNNEX's overall financial health at a glance.
Looking For More TD SYNNEX Investment Ideas?
If TD SYNNEX has sharpened your thinking around AI, infrastructure and cash flow quality, it can be useful to test that framework against a wider watchlist using the Simply Wall St Screener.
- For investors hunting for value with quality fundamentals, consider starting with a 28 high quality undervalued stocks that already clear a cash flow and balance sheet bar.
- If income is a priority and you care about stability as much as yield, scan through a curated set of 8 dividend fortresses that focus on high payouts and balance sheet support.
- For a steadier ride through different cycles, filter for 31 resilient stocks with low risk scores that score well on financial health and business risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com