
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aker BP (OB:AKRBP) Could Be 7% Overvalued Following Its Management Shake Up
Management shake up puts Aker BP in focus
Aker BP (OB:AKRBP) has announced a new executive team and operating model, centred on its exploration to production value chain. The structure is scheduled to take effect from January 2027.
The group plans to redesign how projects move through the organisation during 2026. It aims for fewer internal handoffs and broader use of its industrial data and artificial intelligence tools built over the past decade.
Recent trading has been strong for Aker BP, with the share price at NOK353.7 and a 1 day share price return of 2.20% adding to a 36.09% share price return year to date. The 1 year total shareholder return of 50.52% points to momentum that has built over time as investors weigh this management reset against execution risks and future project delivery.
Scan 174 high quality undervalued stocks that, like Aker BP, pairs established operations with clear projects and data driven execution plans across the energy and infrastructure space.
Aker BP has already delivered a strong run over the past year, yet the new operating model appears to be ahead of the current price rather than behind it. How much of the potential is still on the table at NOK353.7?
Most Popular Narrative: 7% Overvalued
Aker BP closed at NOK353.7 against a widely followed narrative fair value of NOK329.25, so the current price sits above that reference point as investors weigh execution on large projects against a richer valuation.
The Yggdrasil project is designed to be technologically advanced and low-emission, powered by renewable electricity from shore, ensuring efficient and cost-effective operations that will likely improve net margins by reducing operational costs and environmental compliance expenses. Aker BP’s commitment to digitalization, including developments like Agile Asset Management and the ACE toolkit, aims to optimize operations and enhance efficiency, potentially leading to improved net margins and higher earnings through reduced downtime and streamlined processes.
See why 42 investors see Aker BP as 7% overvalued.
Result: Fair Value of NOK329.25 (OVERVALUED)
Still, the Aker BP narrative could be challenged if emissions costs climb faster than expected, or if delays and overruns on projects like Yggdrasil pressure cash flows.
Find out about the key risks to this Aker BP narrative.
Another View on Aker BP’s Valuation
Analyst targets put Aker BP at NOK329.25, which implies the current NOK353.7 price is about 7% above that reference point. A different lens tells a very different story. The SWS DCF model points to a future cash flow value of NOK638.07, which is much higher than today’s market level and frames the stock as trading at a heavy discount. Which set of assumptions do you find more convincing?
Look into how the SWS DCF model arrives at its fair value.
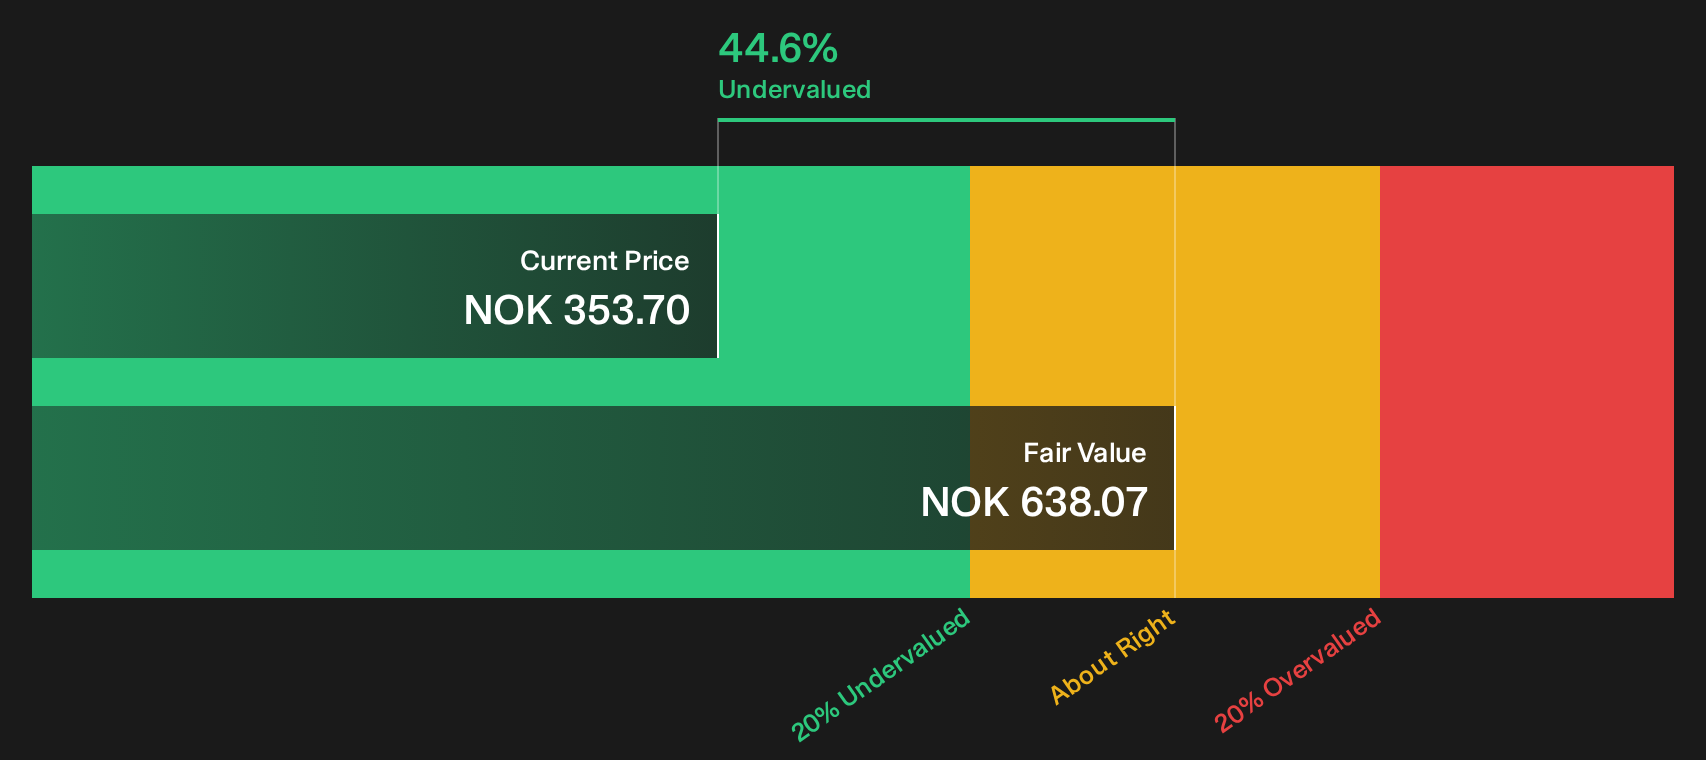
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aker BP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Aker BP pulling investors in opposite directions on risks and rewards, move quickly, check the data for yourself, and see the full breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Aker BP?
If you stop with Aker BP, you risk missing opportunities that better match your goals, risk comfort, and income needs across different corners of the market.
- Target reliable portfolio anchors by scanning a list of solid balance sheet and fundamentals (204 results) that can help cushion shocks when conditions turn volatile.
- Hunt for mispriced potential and review a 618 high quality undiscovered gems before attention and capital move on without you.
- Strengthen your income stream by checking a 223 dividend fortresses built around companies with sizeable yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com