
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Leadership Reset Might Change The Case For Investing In Universal Music Group (ENXTAM:UMG)
- Universal Music Group recently reshaped its senior ranks, promoting Frank Briegmann to oversee Europe, Australia, New Zealand, Canada and Deutsche Grammophon, while adding Libby Bush for global brands and Òscar Celma for applied AI and machine learning.
- This cluster of leadership appointments concentrates decision making in key regions and functions. This change could influence how Universal Music Group executes on digital, data and partnership priorities.
- The next consideration is what this leadership reset could mean for Universal Music Group's investment narrative, particularly around applied AI capabilities under Òscar Celma.
Universal Music Group Investment Narrative Recap
To own Universal Music Group, you need to believe its catalog, Streaming 2.0 deals and emerging AI licensing can keep turning listening time into higher quality recurring income. In the short term, the focus is execution. The group is working through weaker merchandising profitability, softer free cash flow and a highly volatile share price while still funding catalog and tech investment.
The latest leadership moves look more like enablers than hard catalysts. They do not change the near term swing factors, which remain how quickly Streaming 2.0 contracts, superfan initiatives and AI partnerships show up in margins, against the risk that user generated short form platforms stay harder to monetize.
Òscar Celma’s appointment to lead applied AI sits closest to the current thesis on Universal Music Group. The investment case already leans on responsible AI licensing with partners like Spotify, ElevenLabs and NVIDIA to build new royalty and service revenue streams that do not carry equivalent operating cost, so execution in this area matters.
Celma’s background in recommendation and discovery tools at Spotify and Pandora ties directly into those AI related catalysts, which aim to lift monetization without relying solely on higher listening hours. The key watchpoint is whether his work helps Universal Music Group improve the economics of discovery and superfan products while managing legal, cash flow and margin pressures.
Universal Music Group's current analyst narrative points to revenues of €15.6b and earnings of €1.8b by 2029. That profile assumes revenue grows at 6.9% a year and that earnings rise by about €1.5b from €323.0m today to reach the 2029 consensus level.
Uncover how Universal Music Group's fair value indicates a 46% potential upside to its current price before the market closes the discount.
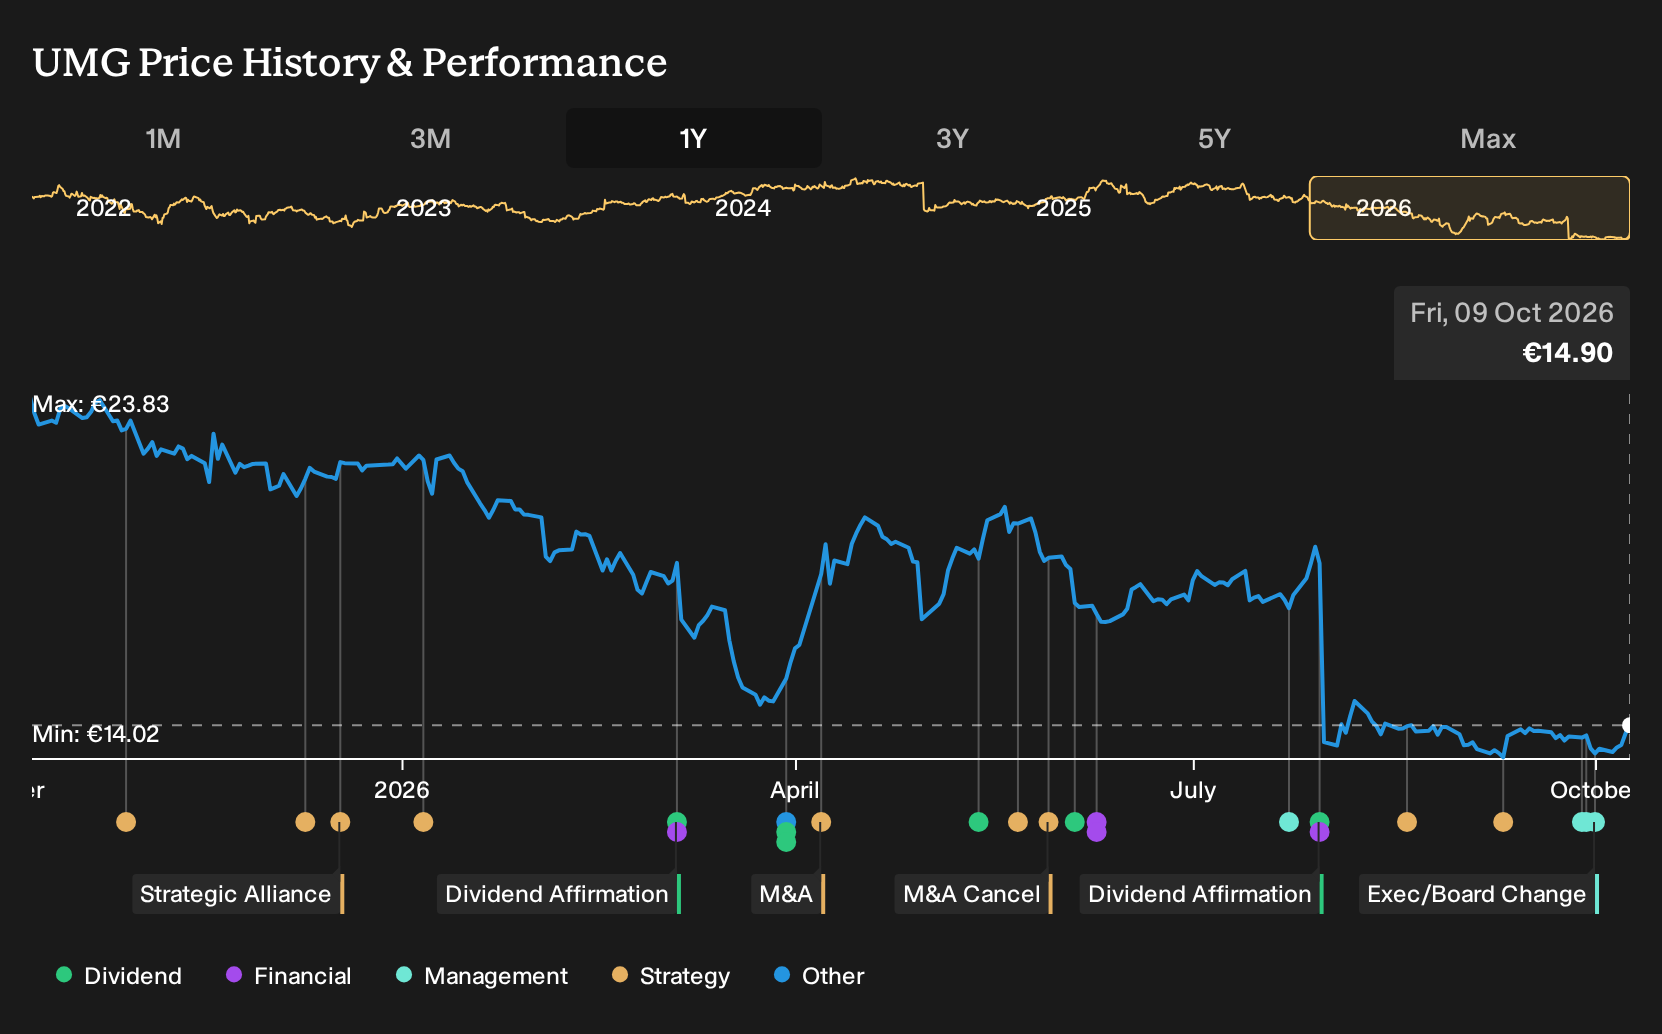
Exploring Other Perspectives
One alternate view says Universal Music Group’s bigger risk is AI eroding catalog scarcity rather than powering new products. The most bearish analysts were only comfortable with a €12.0 price target, even while still penciling in about €15.6b of revenue and €1.8b of earnings by 2029. These pre news forecasts may shift, so treat them as starting points and compare several angles before you decide how this leadership reshuffle fits your own thesis.
Explore 6 other Universal Music Group fair value estimates, including one that suggests there could be as much as 19% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Music Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Music Group's overall financial health at a glance.
Looking for more Universal Music Group style investment ideas?
If the Universal Music Group story has you thinking about what else might fit your portfolio, the Simply Wall St Screener can help you widen the field quickly while still keeping quality front and center.
- For investors who want income first, filter for established payers and resilient yields through 223 dividend fortresses that already clear a 5% hurdle.
- If balance sheet strength matters most to you, narrow the universe to companies with cleaner leverage and solid fundamentals using the list of solid balance sheet and fundamentals (204 results).
- When you are hunting for under-the-radar opportunities with robust metrics, let the 618 high quality undiscovered gems surface ideas that the broader market may not be watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com