
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Treasury Wine Estates (ASX:TWE) Is Back In The Spotlight, But What Is Driving It?
Treasury Wine Estates (ASX:TWE) has confirmed Justin Pipito as Group Chief Financial Officer, following a broad search that ended with the internal candidate who has held multiple finance roles across the business.
Treasury Wine Estates shares trade at A$5.62, with a 90 day share price return of 22.98% and a 30 day gain of 6.04%, indicating potential momentum, although the 1 year total shareholder return has declined 19.48% and the 5 year total shareholder return is down 44.54%.
Compare this leadership shift at Treasury Wine Estates with other potential turnaround stories by scanning our hand picked list of 15 high quality undiscovered gems across global markets.
Treasury Wine Estates has rallied in recent months while analysts still see a range of outcomes on fair value. With that gap sitting in plain sight, how far from the mark does today’s price look?
Most Popular Narrative: 20.5% Undervalued
The current A$5.62 share price for Treasury Wine Estates sits well below a narrative fair value of A$7.07, setting up a story that leans on execution, debt reduction and earnings recovery rather than quick fixes.
At A$7.072 per share, Treasury Wine Estates (ASX: TWE) appears reasonably valued, although the assessment relies on earnings recovering during the second half of FY26. TWE reported first-half revenue of A$1.30 billion, EBITS of A$236.4 million and underlying earnings of 15.9 cents per share. Annualising these earnings gives a P/E ratio of approximately 22 times, although management expects second-half EBITS to exceed the first-half result and now forecasts FY26 EBITS in the range of A$480 to A$490 million.
See why 5 investors see Treasury Wine Estates as 21% undervalued.
According to Jamesiskindacool, this view leans heavily on existing Treasury Wine Estates brands and current FY26 guidance, rather than assuming the full A$100m cost reduction target or a sharp recovery in the US market will arrive on schedule. The narrative also flags A$1.87b of net debt and a 2.4x leverage ratio, plus the paused FY26 interim dividend, as key items for investors tracking how quickly cash generation improves.
Result: Fair Value of A$7.07 (UNDERVALUED)
Still, the Treasury Wine Estates story could be knocked off course if weaker US demand lingers or if debt reduction and cash generation progress more slowly than planned.
Find out about the key risks to this Treasury Wine Estates narrative.
Another view on Treasury Wine Estates valuation
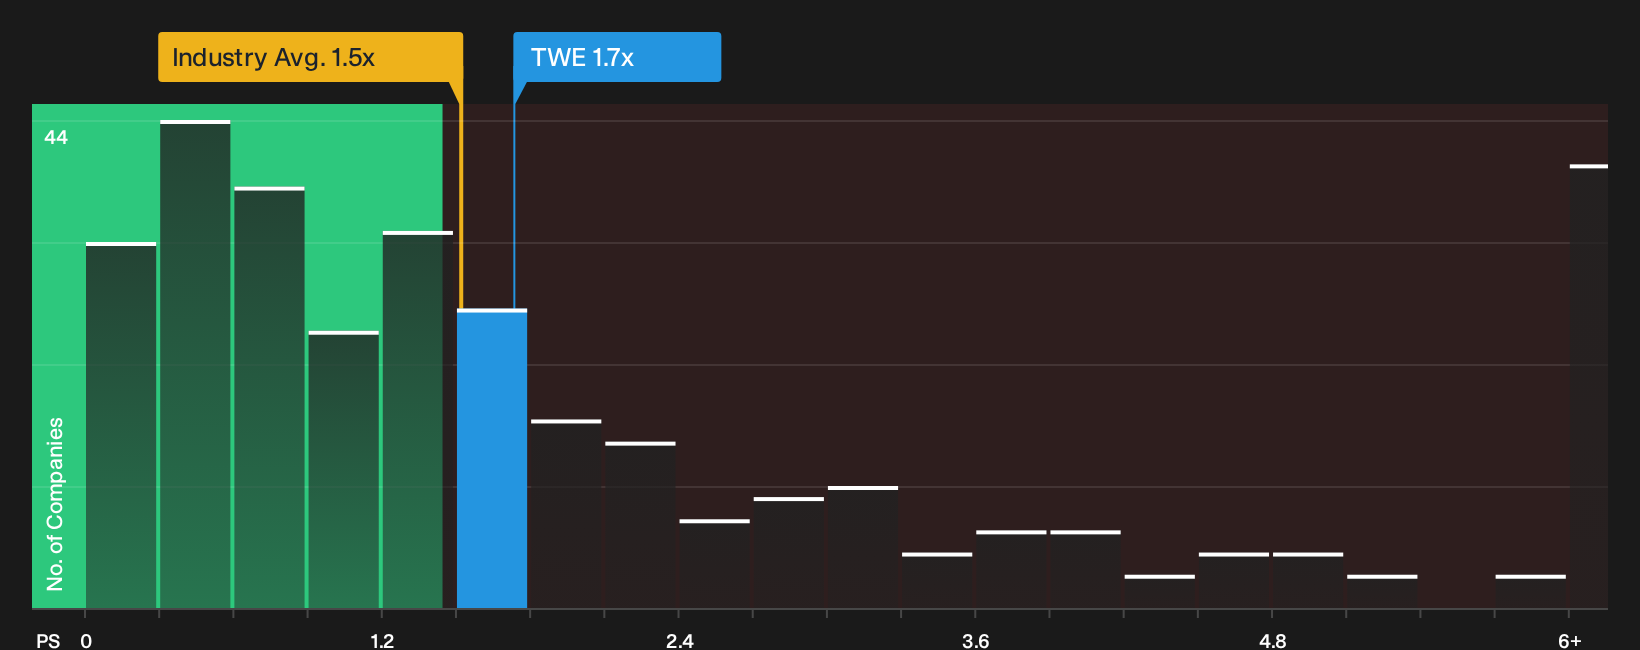
The earlier fair value of A$7.07 paints Treasury Wine Estates as undervalued, yet the current pricing tells a more cautious story. The P/S ratio sits at 1.7x. That is higher than both the peer average of 1.4x and a fair ratio of 1.2x that the market could move towards.
This richer sales multiple compared with peers and the fair ratio suggests less margin for error if earnings or cash generation disappoint. With such a gap between narrative fair value and what the P/S ratios signal, which story do you treat as your anchor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and caution around Treasury Wine Estates today. Move quickly, test the assumptions against your own criteria, and weigh how the upside stacks against the known risks in the 2 key rewards.
Looking for more investment ideas beyond Treasury Wine Estates?
If Treasury Wine Estates has your attention, do not stop here. Use the Simply Wall St screener to explore additional opportunities that fit your playbook.
- Target resilient compounding by reviewing a curated 7 resilient stocks with low risk scores that aims to prioritise stability and lower volatility in uncertain conditions.
- Hunt for mispriced quality using the 4 high quality undervalued stocks to focus on companies where fundamentals and current pricing appear out of sync.
- Build a defence first by scanning a list of solid balance sheet and fundamentals (12 results) that focuses on stronger finances and robust balance sheets before considering potential upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com