
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Chile Copper Orders At FLSmidth Stock Have Changed Its Investment Story
- FLSmidth & Co. A/S reported two sizeable Chilean copper orders in Q3 2026, worth about DKK 535 million combined, covering high-pressure grinding, large gearless ball and SAG mills, and the world’s largest gyratory crusher, plus installation, commissioning and service support.
- The Chile contracts deepen FLSmidth’s installed base in a key copper hub and reinforce long-run aftermarket and service potential, even though 2026 guidance remains unchanged.
- We will now look at how these large Chilean copper equipment orders could influence FLSmidth's investment narrative around services and capex.
FLSmidth Investment Narrative Recap
To own FLSmidth, you need to believe the mining focused portfolio can keep shifting toward higher margin service, pumps and cyclones, while stabilising the lumpier Products division. The two Chilean copper wins help the installed base in a key geography, but they do not change 2026 guidance, so they look incremental rather than transformational in the near term.
The key short term swing factor remains execution on cost base simplification and margin lift in Products from a weak EBITA position. The biggest operational risk is still delayed or softer mining capex, particularly in South America, which could leave fixed costs exposed if large greenfield projects fail to materialise as planned.
The DKK 360 million order for the world’s largest gyratory crusher and associated mills in Northern Chile is the clearest operational link to the current copper momentum. It extends FLSmidth’s footprint at a large concentrator, supports future aftermarket exposure and feeds into the push to grow recurring service revenue tied to proprietary equipment.
At the same time, this contract underlines the double edged nature of the story. Large, one off projects can lift order intake and support the Products recovery, yet they also reinforce dependence on cyclical mining capex and long project timelines, with commissioning for this package not expected until late 2029 and early 2030.
What The Chile Orders Mean Against FLSmidth's Consensus Targets
The Chile deals sit against a backdrop where analysts are already baking in steady expansion for FLSmidth. The current consensus assumes revenue increases of 7.5% a year for the next three years, with profit margins moving from 10.6% today to 11.4% by 2029 as the mix tilts more toward services and higher value equipment.
On earnings, the sell side is working with DKK 1.6b of profit today and a forecast of DKK 2.1b in 2029. That implies an uplift of about DKK 500m over the period, supported by both volume and margin improvement as the portfolio reshapes. Analysts also assume a modest reduction in share count, with outstanding shares projected to decline by 3.41% per year over the next three years. If achieved, this would amplify earnings per share relative to absolute profit growth.
Against those assumptions, the Chilean copper wins look like part of the machinery that could help fill the revenue and margin bridge rather than an outlier that rewrites the story. High pressure grinding rolls, gearless mills and the very large crusher ordered for Northern Chile deepen the equipment footprint in one of FLSmidth's most important copper regions. That larger installed base can be a feeder for service contracts, spare parts and process upgrades that align with the consensus expectation of slightly higher margins by 2029.
On valuation, the current analyst framework ties these operational assumptions to a 2029 revenue figure of DKK 18.3b and earnings of DKK 2.1b. The price target of DKK 649.17 rests on the idea that FLSmidth could be trading on a P/E of 18.3x in that year, a touch below the current 18.5x multiple and slightly under the GB Machinery sector at 19.0x. The discount rate in that model sits at about 6.8%, which is the lens used to bring those future cash flows back to today.
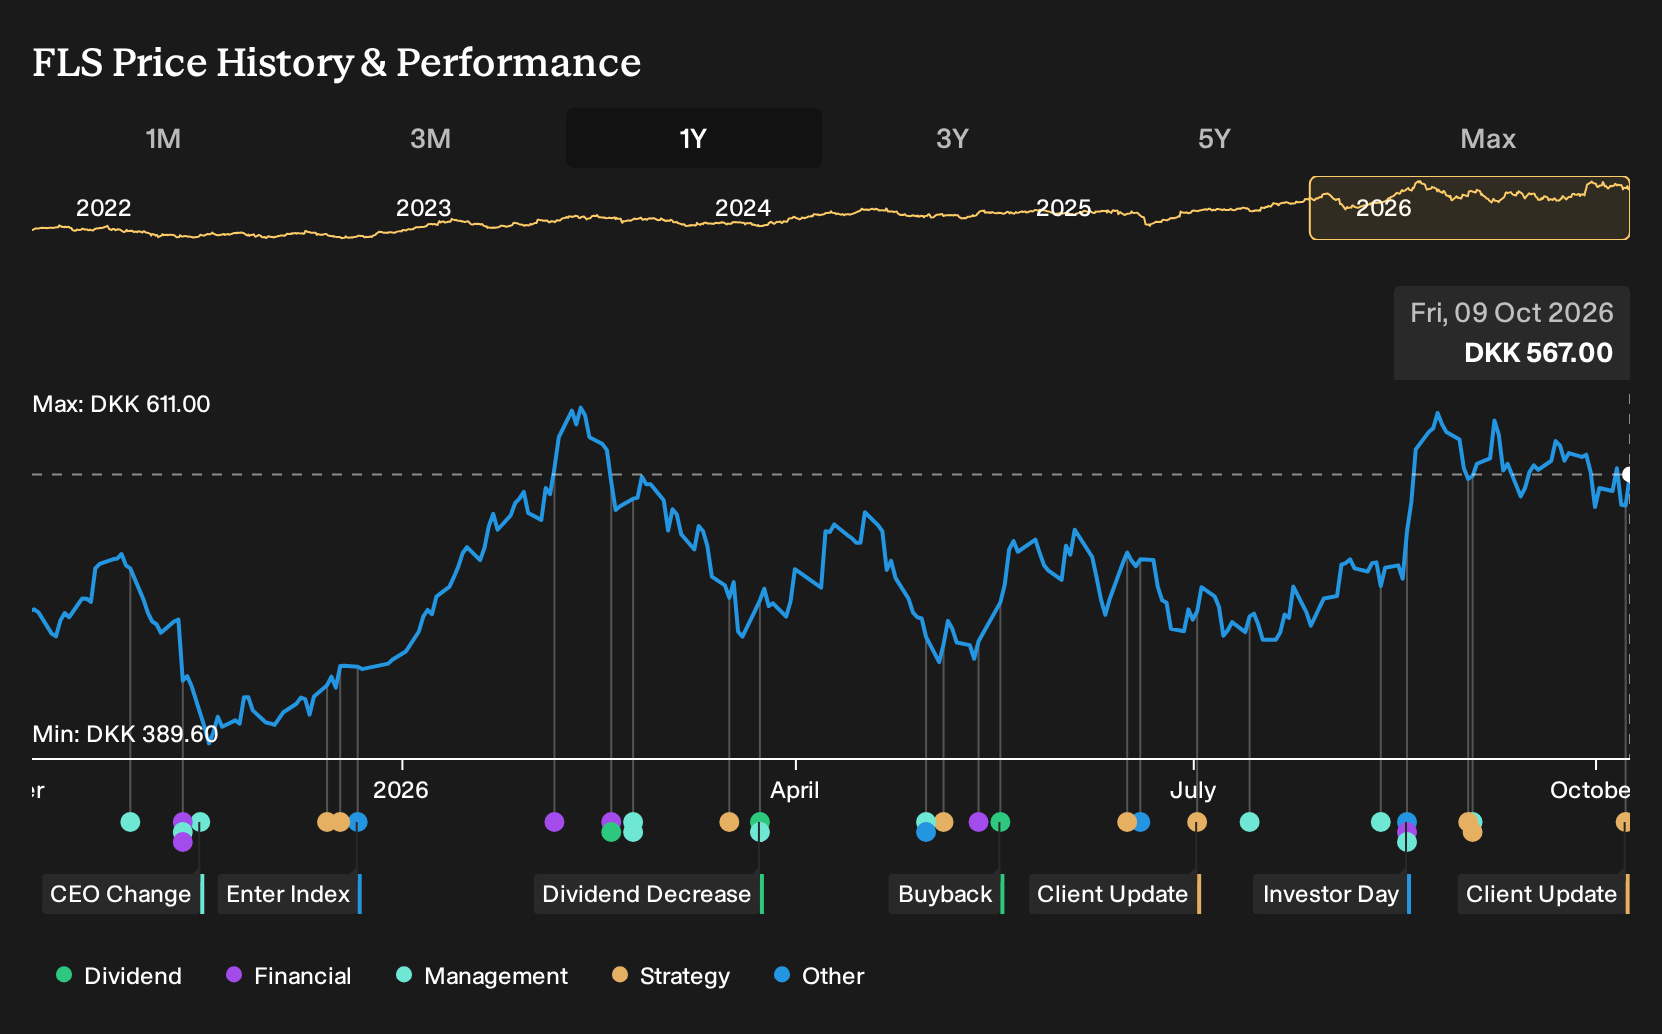
The share price context matters for how you read the Chile orders. With the stock at DKK 546.0 on the numbers provided, the consensus target implies upside of 15.9% if the revenue, margin and multiple assumptions all land as expected. The new copper work adds some comfort around the order pipeline, particularly for Products, but it does not change the formal 2026 guidance. That keeps the onus on execution in cost reduction and service expansion rather than on a single wave of mega contracts.
For anyone tracking FLSmidth as a copper and services exposure, the key question is less about whether these specific projects move the needle on a DKK 18.3b revenue base in 2029 and more about what they signal on win rates and installed base quality. Each large concentrator package in Chile effectively seeds multi decade service potential, which aligns with the consensus margin uplift. At the same time, it reinforces exposure to long dated greenfield cycles, a point worth keeping in mind if mining capex timing in South America proves choppy.
FLSmidth's narrative projects DKK 18.3b revenue and DKK 2.1b earnings by 2029, which rests on 7.5% yearly revenue growth and an earnings increase of about DKK 500m from DKK 1.6b today.
Uncover why FLSmidth's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on FLSmidth focuses on copper concentration risk. The most optimistic analysts were already assuming revenue of about DKK 18.7b and earnings around DKK 2.2b by 2029, tied to strong critical minerals exposure. You can now ask whether these Chile contracts justify that more upbeat view or push expectations even further. This is why it helps to compare several analyst scenarios rather than rely on a single story.
Explore 2 other FLSmidth fair value estimates, including one that suggests as much as 29% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your FLSmidth research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FLSmidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FLSmidth's overall financial health at a glance.
Looking For More Investment Ideas Beyond FLSmidth?
If you want to stress test your view on FLSmidth and broaden your watchlist, it can help to line it up against other companies with clear financial traits using the Simply Wall St Screener.
- If capital preservation is front of mind, compare FLSmidth's profile with a set of companies screened for resilience through 222 resilient stocks with low risk scores.
- If dependable cash generation appeals to you, stack FLSmidth against businesses that feature in our list of solid balance sheet and fundamentals (204 results).
- If you prefer to hunt for opportunities before they are widely followed, contrast FLSmidth with a pool of under-the-radar stocks drawn from 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com