
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ABN AMRO Bank (ENXTAM:ABN), What Is Behind The Fresh Attention?
Infosys and ABN AMRO Bank (ENXTAM:ABN) have renewed and expanded their AI collaboration, with Infosys taking on development, testing, and support work to help modernize the Dutch lender’s IT systems and data capabilities.
ABN AMRO Bank’s latest AI push with Infosys comes at a time when momentum has cooled in the very short term, with the 7 day share price return down 3.58% and the 30 day move down 4.89%. However, the year to date share price return of 33.76% and 1 year total shareholder return of 60.75% still point to strong longer term gains that many investors are watching closely for signs of whether this renewed tech focus extends or reshapes that trend.
Scan how ABN AMRO Bank’s AI push compares with other financial players that are leaning into automation and data, starting with our curated list of 92 AI infrastructure stocks.
ABN AMRO Bank now trades at a discount to both analyst targets and an estimated intrinsic value, despite the AI tie up headlines. Is that caution sensible, or has the pullback gone too far, as the valuation section shows next?
Most Popular Narrative: 8.3% Undervalued
On the most followed view, ABN AMRO Bank screens below an estimated fair value of €44.11, compared with a last close of €40.45. The renewed AI push with Infosys therefore fits into a story that is already framed around discounted pricing and improving fundamentals.
The fair value estimate for ABN AMRO Bank is now set at €44.11. This move is supported by analysts who have recently raised price targets across the stock, including new levels of up to €54, alongside modest adjustments to revenue growth, profit margin and future P/E assumptions.
See why 55 investors see ABN AMRO Bank as 8% undervalued.
Result: Fair Value of €44.11 (UNDERVALUED)
Still, higher regulatory capital demands and ongoing compliance costs could squeeze ABN AMRO Bank’s returns and limit the potential benefits of its AI and digital plans.
Find out about the key risks to this ABN AMRO Bank narrative.
Another View: ABN AMRO Bank On Earnings Multiples
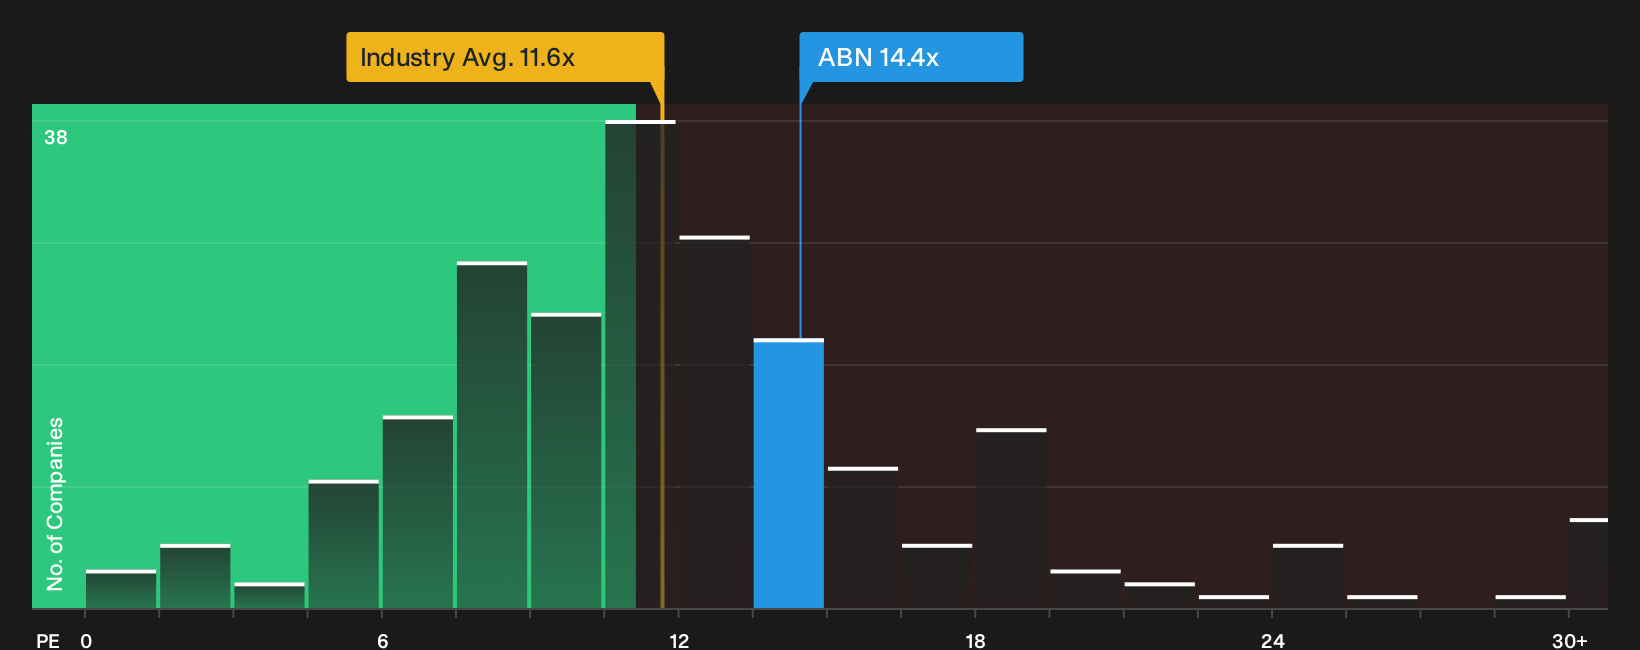
The earlier fair value work points to ABN AMRO Bank trading below an estimated worth, yet the earnings multiple tells a different story. The current P/E of 14.4x sits above the European banks average of 11.6x and a fair ratio of 13.4x, which suggests less of a bargain and more valuation risk if sentiment cools.
Our P/E check flags this gap clearly. It is worth asking how much weight you want to give to discounted cash flow style fair values when the market is already paying a premium on near term earnings for ABN AMRO Bank See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around ABN AMRO Bank is mixed, with both risks and upsides in play. Consider acting while the data is fresh and test the story against your own expectations by weighing the 3 key rewards and 2 important warning signs.
Looking for more ABN AMRO Bank style investment ideas?
If you stop with ABN AMRO Bank, you could miss other opportunities. Run the same disciplined lens across fresh ideas that match your own risk and income preferences.
- Target long term compounding by reviewing a curated group of businesses that combine strong fundamentals with attractive entry prices using the 174 high quality undervalued stocks.
- Strengthen your income stream by scanning companies that aim to pair higher yield with resilience through the 223 dividend fortresses.
- Dial back portfolio risk by filtering for financially robust businesses with cleaner balance sheets via the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com