
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is REPT BATTERO Energy (SEHK:666) Cheap After Its First EV Battery Export Shipment?
REPT BATTERO Energy (SEHK:666) is back on investor radars after REPT Battero Indonesia, its majority owned joint venture, completed Indonesia’s first export shipment of locally produced electric vehicle batteries.
The latest shipment news lands while REPT BATTERO Energy’s share price sits at HK$8.605, with a 1-day share price return of 2.26% and 7-day share price return of 3.67%. However, the 30-day and year-to-date share price returns have declined 13.43% and 34.51% respectively, contributing to a 1-year total shareholder return that is down 39.66%. This points to short-term momentum building alongside a weaker longer-term track record as investors reassess both growth potential and execution risk.
Scan for other battery and energy storage players that are showing similar export momentum with our curated list of 43 power grid technology and infrastructure stocks
The shipment win has given REPT BATTERO Energy a short-term lift, while longer term returns remain weak. Does that mix of fresh execution progress and a depressed share price still tilt the risk reward toward buyers?
Price-to-Earnings of 12.3x: Is it justified?
On the numbers, REPT BATTERO Energy trades on a P/E of 12.3x, which leaves the stock looking slightly expensive versus its Hong Kong electrical peers even though the share price has fallen sharply over the past year.
The P/E ratio links the current share price to earnings per share and gives you a shorthand way to see how much investors are paying for each unit of profit. For a lithium battery producer like REPT BATTERO Energy, that matters because earnings can move quickly as capacity ramps up. The multiple is really a snapshot of how the market is weighing future profitability against recent results.
REPT BATTERO Energy screens as good value against its peer group, with a 12.3x P/E compared to a peer average of 32.8x and an estimated fair P/E of 14x. This indicates that the market valuation is somewhat below that estimated fair level, given current profit trends and forecasts.
Against the broader Hong Kong electrical industry, the picture flips. REPT BATTERO Energy changes hands at a premium to the sector average P/E of 11.7x, which signals that investors are paying up relative to the industry while still seeing a discount compared with closer peers that trade on much richer earnings multiples.
Explore the SWS fair ratio for REPT BATTERO Energy.
Result: Price-to-Earnings of 12.3x (ABOUT RIGHT)
Still, the steep 1 year share price decline and exposure to capital intensive battery production mean any earnings disappointment could quickly pressure sentiment toward REPT BATTERO Energy.
Find out about the key risks to this REPT BATTERO Energy narrative.
Another View on REPT BATTERO Energy’s Valuation
The earnings multiple tells one story, but the SWS DCF model tells another. On that cash flow view, REPT BATTERO Energy at HK$8.61 is trading around 70% below an estimated fair value of HK$29.16. This frames the current price as heavily depressed rather than just slightly rich on a P/E basis. Which lens do you trust more when the signals disagree this much?
Look into how the SWS DCF model arrives at its fair value.
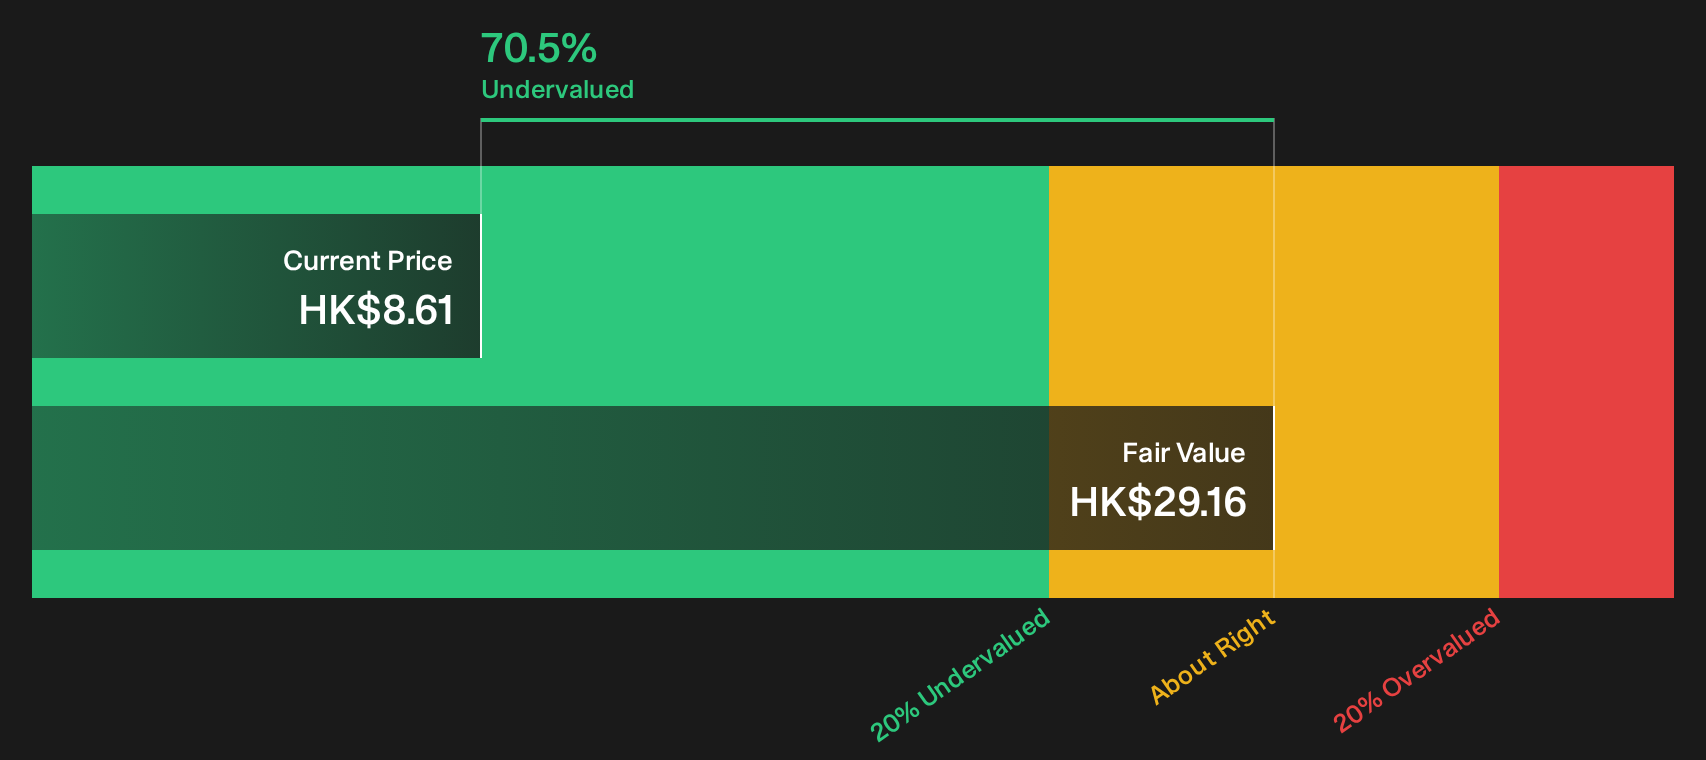
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out REPT BATTERO Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sceptical of the mixed signals around REPT BATTERO Energy, or starting to see a potential mismatch between price and expectations? Act quickly and review the full breakdown of potential upsides, then pressure test your own thesis with the 3 key rewards
Looking for more REPT BATTERO Energy style opportunities?
Do not stop your research with REPT BATTERO Energy. Fresh ideas often sit just outside your watchlist, and missing them can quietly drag long term returns.
- Target potential mispricings and refresh your watchlist with 174 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 223 dividend fortresses.
- Focus on resilience and capital protection by scanning the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com