
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CCS Milestone Could Be A Game Changer For Eni Stock (BIT:ENI)
- Eni is exploring the sale of a stake in the Perla offshore gas field in Venezuela with Repsol, while also completing installation of the Douglas CCS platform at Liverpool Bay through Eni CCUS Holding to support industrial carbon capture and storage.
- The combination of a potential portfolio reshuffle in Venezuela and tangible CCS infrastructure in the UK highlights how Eni is reallocating capital between legacy hydrocarbons and lower carbon projects, which can influence its earnings mix and regulatory exposure.
- The focus now turns to how Eni's investment narrative could shift as the Douglas CCS platform progress feeds into expectations for its earnings outlook.
Scan beyond Eni and identify peers that are repositioning their portfolios with 174 high quality undervalued stocks and are also leaning into lower carbon infrastructure while managing legacy hydrocarbon exposure.
What Is Eni's Investment Narrative?
To own Eni, you need to be comfortable with a story that mixes heavy upstream exposure with growing lower carbon infrastructure. The Douglas CCS platform in Liverpool Bay is a concrete piece of that shift, and it leans on Eni’s ability to execute complex offshore projects. The potential sale of a Perla field stake goes in the other direction. That move would effectively reweight capital away from a high risk jurisdiction and into projects where regulatory frameworks for carbon and gas are clearer.
In the short term, the key swing factors remain commodity prices, project delivery and cash generation to support a dividend that is not well covered by free cash flow. Earnings forecasts currently point to declining profit and revenue over the next three years, even after a very large jump in earnings in the last twelve months and a recent upgrade in analyst estimates. The Venezuela process adds another layer of geopolitical and sanctions risk, so investors will likely focus on how deal terms, timing and any proceeds interplay with CCS build out and balance sheet discipline.
That said, sitting underneath the CCS headlines and valuation upside implied by some models is a less comfortable pressure point around ...
There's only one way to know the right time to buy, sell or hold Eni. Head to Simply Wall St's company report for the latest analysis of Eni's Fair Value.
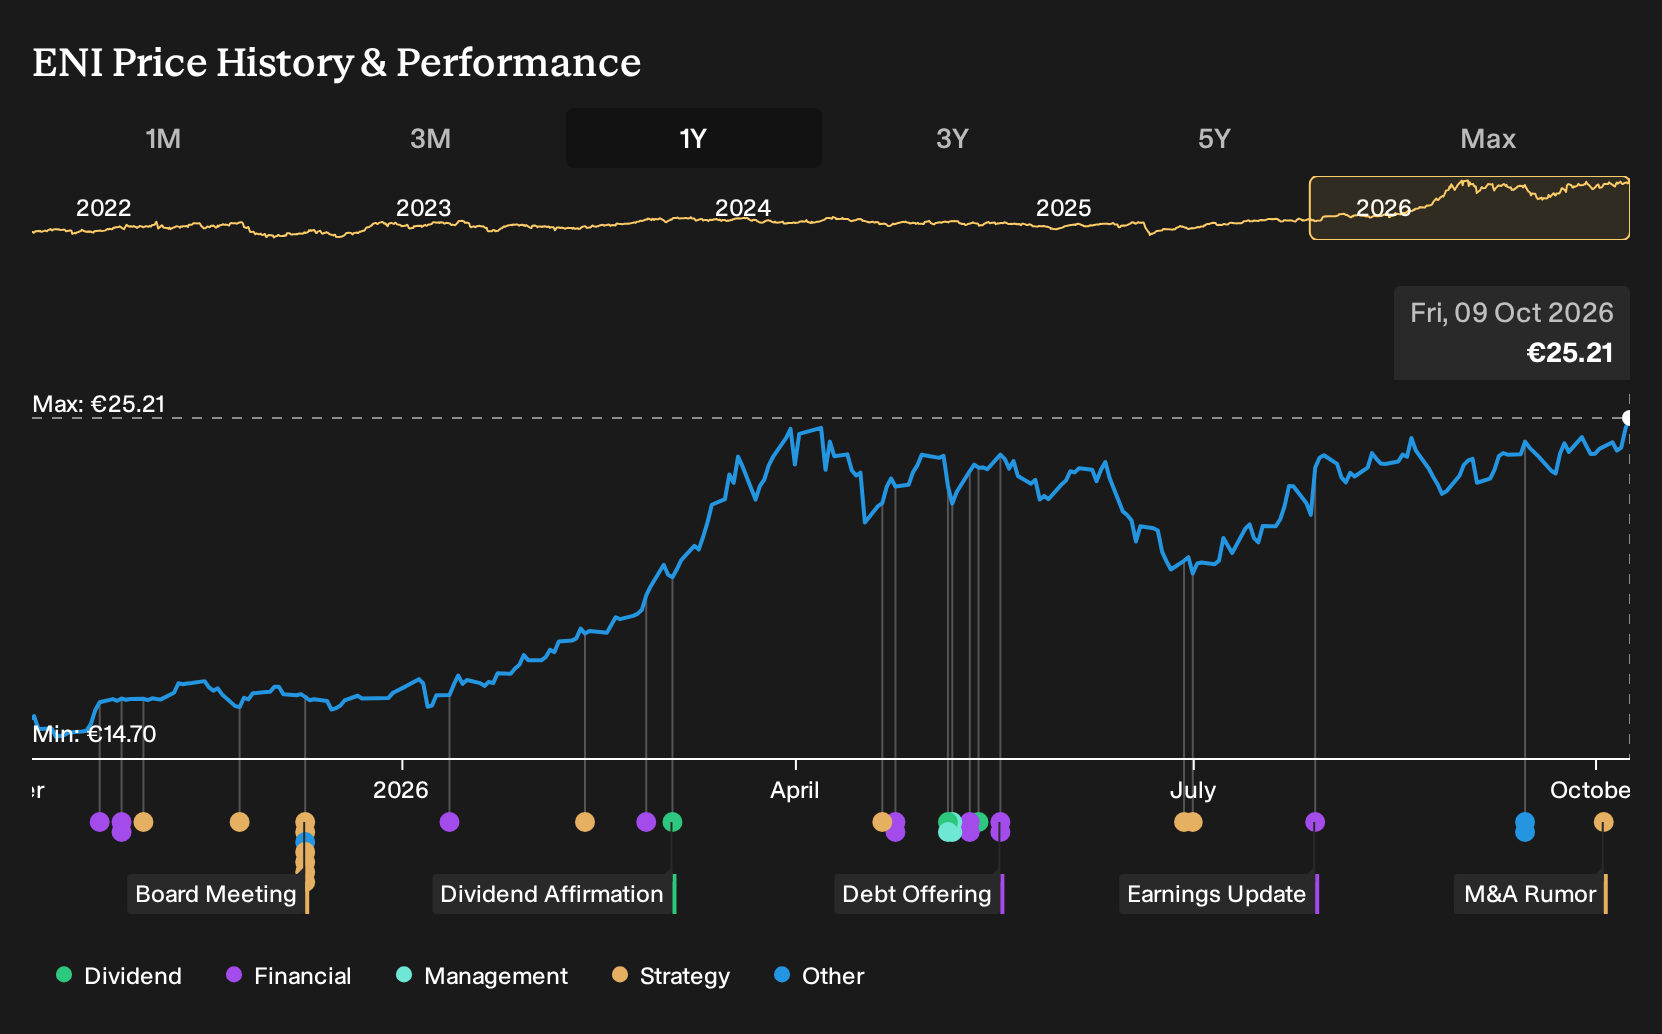
Exploring Other Perspectives
The sharpest alternate view on Eni focuses on revenue risk rather than CCS upside. The most bearish analysts were modelling revenue to fall about 14.3% each year and earnings to ease from €5.8b to €5.0b by around 2029, before this Perla stake news. Use those more cautious assumptions as a counterweight and test which story you find more convincing.
Explore 4 other Eni fair value estimates, including one that suggests as much as 18% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eni research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eni. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eni's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eni?
Once you have a view on Eni, it can help to widen the lens and compare it with other companies that fit different risk, income and balance sheet profiles using the Simply Wall St Screener.
- If capital preservation is your priority, start with companies that score well on resilience and risk, using the 222 resilient stocks with low risk scores as your filter for candidates to research further.
- For investors who want robust finances to underpin future decisions, focus on balance sheet strength and cash generation through a list of solid balance sheet and fundamentals (204 results) that can handle tougher conditions.
- Income focused readers can concentrate on payouts backed by fundamentals by reviewing a curated 223 dividend fortresses offering yields above 5% with an eye on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com