
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Dividend Stocks To Watch With Up To 5% Yield
With the US 10 year Treasury yield hovering near a 24 year high, low risk income from government bonds has become far more tempting. That puts extra pressure on investors who still want regular cash flow from equities. Well covered dividends above 3% can help fill that gap. This article highlights three stocks from a high yield, dividend focused screen that aims to balance income with sustainability.
The three stocks covered below are a small sample of what qualifies, and the full screen surfaced 175 more companies with dividend yields above 3% that also show coverage, growth and payment stability that are not detailed here. To widen your watchlist and analyze income ideas that fit your own risk tolerance, head straight into the Dividend Powerhouses (3%+ Yield) screener.
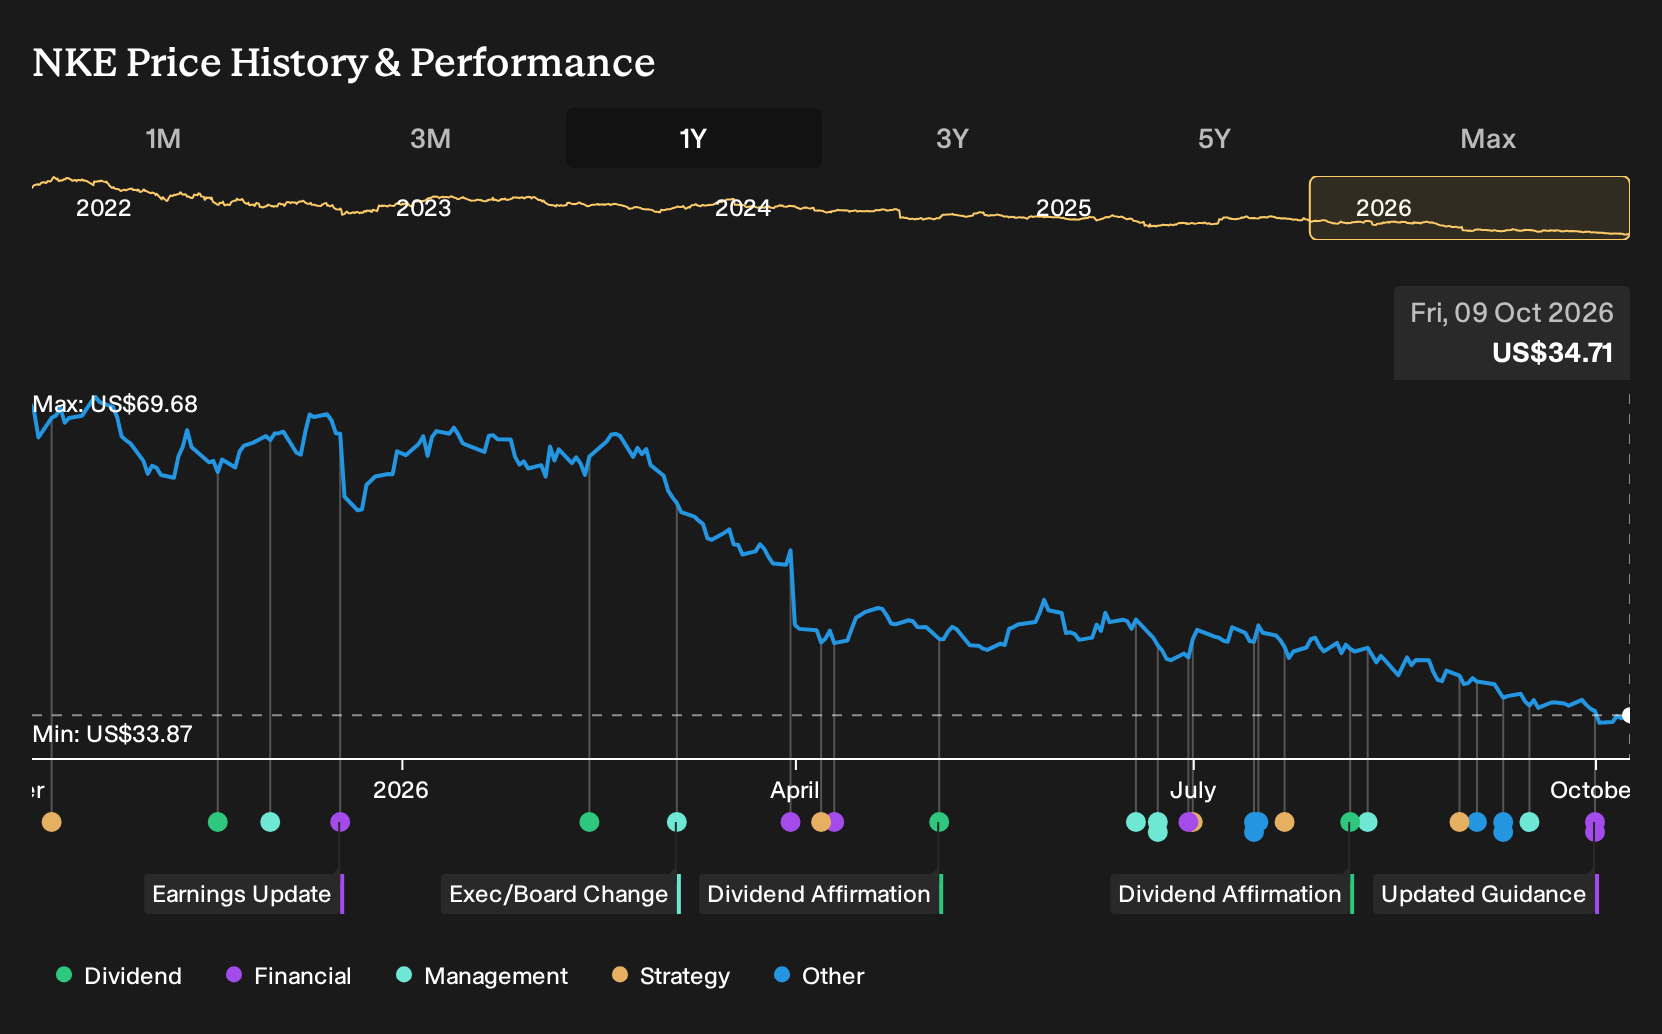
NIKE (NKE)
NIKE is best known for its global athletic footwear and apparel. What earns it a place in this Dividend Powerhouses screen is the way that cash-rich business helps fund regular shareholder payouts.
NIKE designs and sells branded sports footwear, apparel and equipment worldwide, with the NIKE Brand in North America generating about US$20.6b of revenue, Europe, Middle East and Africa contributing roughly US$12.4b, Asia Pacific and Latin America around US$6.2b, Greater China about US$5.5b, and Converse about US$1.1b. Together, these segments support a market value near US$51.6b.
"The November 2026 investor day is the deciding event. It will show whether management's targets support the recovery case or the conservative one."
Dividend focused investors will be watching how one quiet but crucial pressure on Nike’s cash generation is addressed when those plans are laid out.
That quiet pressure on cash generation is exactly where the full narrative for NIKE shows how NIKE could still accelerate shareholder returns if management resets its playbook effectively.
DRDGOLD (DRD)
DRDGOLD is a South African gold producer that earns income by extracting gold from surface mine tailings, a cash generating model that supports regular dividends in line with the Dividend Powerhouses theme. It generated ZAR 8,080 million from Ergo and ZAR 3,079 million from FWGR, and the stock has a market value around US$2.1b.
DRDGOLD couples a 3%+ yield profile with tailings based gold production. It produced ZAR 11,159 million of revenue and ZAR 4,255.5 million of net income in 2026, alongside 19 straight years of dividends. That mix of cash flow and payouts only holds if one unseen pressure on earnings quality behaves itself.
If that pressure on earnings quality has you curious, go straight to the 2 key rewards and 2 important warning signs (1 is major!) to see how DRDGOLD's dividend story and risk profile really line up.

Brown-Forman (BF.B)
Brown-Forman sits squarely in this Dividend Powerhouses theme because its long-lived Jack Daniel’s led spirits portfolio throws off consistent cash, giving the group room to support a 3%+ yield while still investing in new products and wider global reach.
Brown-Forman produces and sells a broad range of spirits, wines and ready to drink cocktails worldwide, generating about US$3.9b from beverage alcohol consumer products and carrying a market value near US$12.3b.
"Growth in ready to drink products like New Mix, el Jimador Spritz and Jack Daniel’s Tennessee Blackberry, which together are adding multi point value growth contributions in key markets, is creating a higher volume platform that can add to revenue while partially offsetting the impact of softer full strength spirits demand on operating income."
The dividend story hinges on how one margin pressure plays out against that cash rich whiskey and tequila engine over the next few years.
That margin tug of war is exactly where the full narrative for Brown-Forman maps out how Brown-Forman could keep accelerating cash generation as that ready to drink wave builds.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every fund manager is talking about a breakout list, the easy entry points can be gone. Check these under the radar sets and get in early.
- Target steadier portfolio anchors by reviewing a curated 31 resilient stocks with low risk scores that aim to hold up when momentum elsewhere stalls, so your income strategy is not doing all the heavy lifting.
- Ride the build out of next generation infrastructure with a focused 92 AI infrastructure stocks that spotlights businesses powering data centers, chips and networking gear before pricing fully reflects the demand.
- Track powerful income ideas with a hand picked 8 dividend fortresses that focuses on higher yielding payouts while cash flows and balance sheets still look supportive, so you are not chasing stretched stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com