
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Box (BOX) Wins A Japanese Bank Client, Is The Stock Fully Valued?
Why The Ogaki Kyoritsu Bank Deal Matters For Box Stock
Box (BOX) just secured a new enterprise deployment at Japan’s The Ogaki Kyoritsu Bank, which is rolling out Box Enterprise Advanced as its central, AI-ready content platform across the institution.
This agreement puts Box at the center of how the bank organizes unstructured information, from manuals to internal rules, so that AI tools can securely tap that data while meeting strict security and governance needs.
Investors have been leaning into that story. Box shares now trade at US$36.39, with the 90 day share price return of 27.06% and year to date share price return of 26.22% pointing to firming momentum. The 3 year total shareholder return of 46.14% reflects steadier compounding in the background as new enterprise wins and leadership changes, such as the incoming Chief Accounting Officer announced on 6 October 2026, reshape expectations around execution and risk.
Scan how Box fits into the wider AI-content story by comparing it with 92 AI infrastructure stocks, which is already attracting attention from institutions with similar security and data-governance needs.
Box has just run hard, yet the current US$36.39 price still sits between a modest 6% gap to the average analyst target and a much wider implied intrinsic discount of about 36%. Which anchor should investors consider more when thinking about fair value next?
Most Popular Narrative: 6% Undervalued
On Simply Wall St's most followed view, Box screens as modestly cheap, with a fair value of about $38.71 against the latest $36.39 close. This puts that Ogaki Kyoritsu Bank win into a wider AI content thesis rather than just a one off contract.
Accelerating take up of Box AI units and agentic workflow capabilities, including new guardrails, prompt injection detection and integrations with agents such as Claude, ChatGPT, Gemini and Harvey, can increase usage based monetization and support revenue growth.
See why 7 investors see Box as 6% undervalued.
Result: Fair Value of $38.71 (UNDERVALUED)
Still, the Box narrative can crack if bundled productivity suites continue to undercut pricing power or if heavy AI usage keeps gross margins close to current levels.
Find out about the key risks to this Box narrative.
Another View On Box Valuation
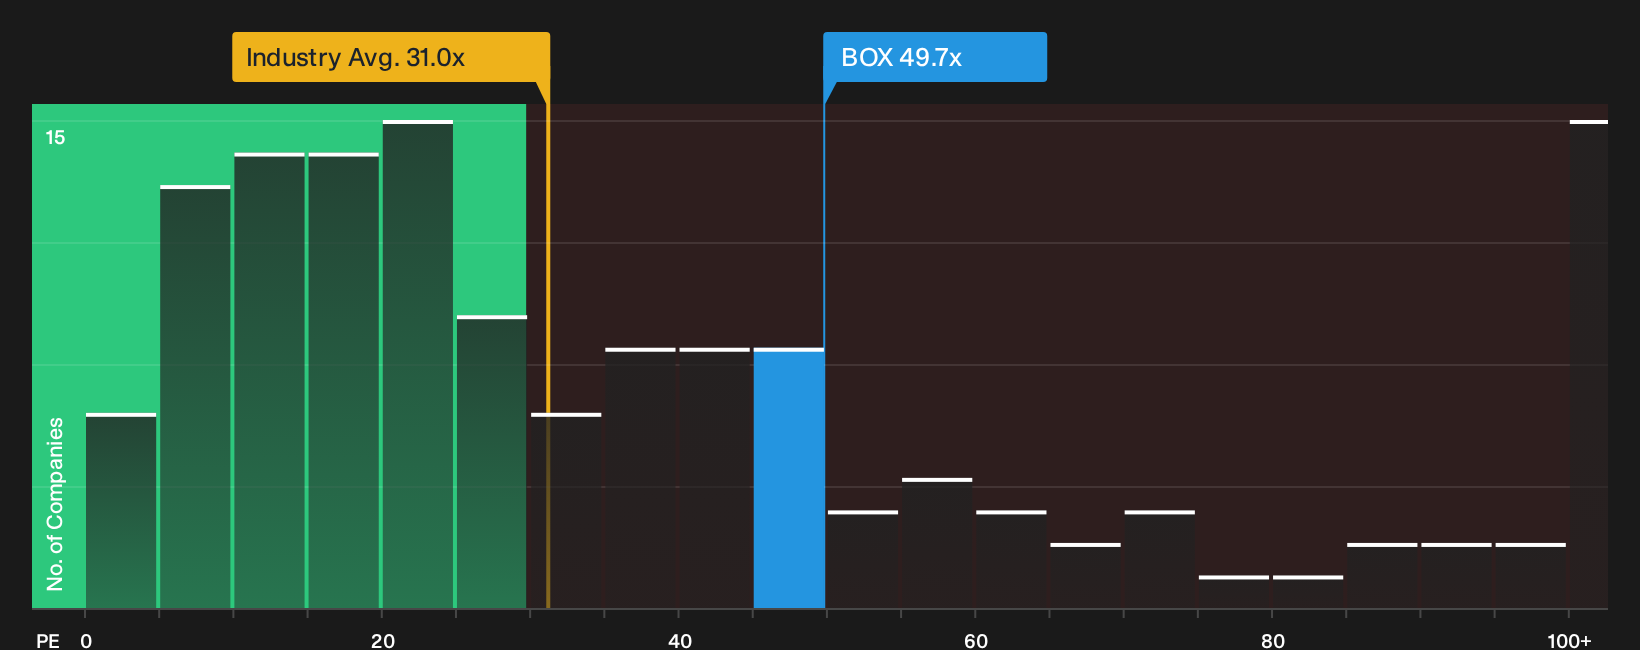
There is a different signal when you look at Box through its P/E ratio. The shares trade on roughly 49.7x earnings, above both the US Software sector at 30.9x and a fair ratio estimate of 22.2x. That gap points to meaningful valuation risk if sentiment cools.
For a closer look at what the numbers imply for Box at today’s price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Box leaves you undecided, act promptly and assess the trade off yourself with 2 key rewards and 2 important warning signs.
Looking for more Box investment ideas?
Box might be front of mind today, but the next opportunity often sits where fewer people are looking and where the numbers quietly line up in your favor.
- Target stronger upside potential by moving through 20 high quality undiscovered gems that pair solid fundamentals with quieter market attention.
- Protect your downside risk by scanning 31 resilient stocks with low risk scores built around businesses with resilient profiles and lower volatility scores.
- Anchor your portfolio in quality by focusing on the list of solid balance sheet and fundamentals (25 results) that can better handle shocks and fund future growth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com