
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Greenbrier Companies (GBX) Could Be 15% Below Fair Value On Its Leasing Growth Story
Recent share price performance and business snapshot
Greenbrier Companies (GBX) has seen its share price decline about 19% over the past 3 months, with the stock closing at US$38.43 on 9 October 2026.
The railcar manufacturer and leasing specialist generated revenue of US$2.63b and net income of US$107.1m. Its Manufacturing segment contributed the bulk of sales, alongside Leasing & Fleet Management services.
Short term momentum for Greenbrier Companies has clearly cooled, with the share price down 10.13% over the past 30 days and 18.75% over 90 days, while the 1-year total shareholder return has declined 10% and the 3-year total shareholder return remains slightly positive.
Compare Greenbrier Companies' recent pullback with hand-picked industrial peers by scanning the list of solid balance sheet and fundamentals (25 results), which aims to pair durable finances with more resilient share price trends.
Greenbrier Companies now trades lower after a steady drift in the share price, which raises a simple tension. Are investors reacting to something in the railcar business itself, or has sentiment moved faster than fundamentals justify?
Most Popular Narrative: 15.2% Undervalued
On the latest narrative, Greenbrier Companies is assessed with a fair value of $45.33 against a last close of $38.43. This points to a material valuation gap that hinges on how recurring leasing income and cost work translate into earnings over time.
Greenbrier Companies is expanding its owned lease fleet, with about 20,600 railcars at 99% utilization and a plan to invest roughly US$300 million per year while targeting doubled recurring revenue by 2028. This strategy directly supports revenue stability and earnings from high margin leasing income.
See why 3 investors see Greenbrier Companies as 15% undervalued.
Result: Fair Value of $45.33 (UNDERVALUED)
Still, the Greenbrier Companies story can be knocked off course if weak railcar orders persist or if revenue shortfalls like Q3 FY2026 repeat.
Find out about the key risks to this Greenbrier Companies narrative.
Another View: Our DCF Model Flashes Caution
The analyst-based fair value for Greenbrier Companies leans on earnings forecasts and P/E assumptions. A different tool, the SWS DCF model, points the other way, with an estimated future cash flow value of just $3.33 against a share price of $38.43. That implies Greenbrier screens as heavily overvalued on a pure cash flow lens, so which story do you trust more: the earnings multiple or the DCF cash flow path?
Before leaning on either signal too heavily, it is worth seeing how the cash flow mechanics are built and what needs to go right in the model for Greenbrier Companies to clear that hurdle. Look into how the SWS DCF model arrives at its fair value.
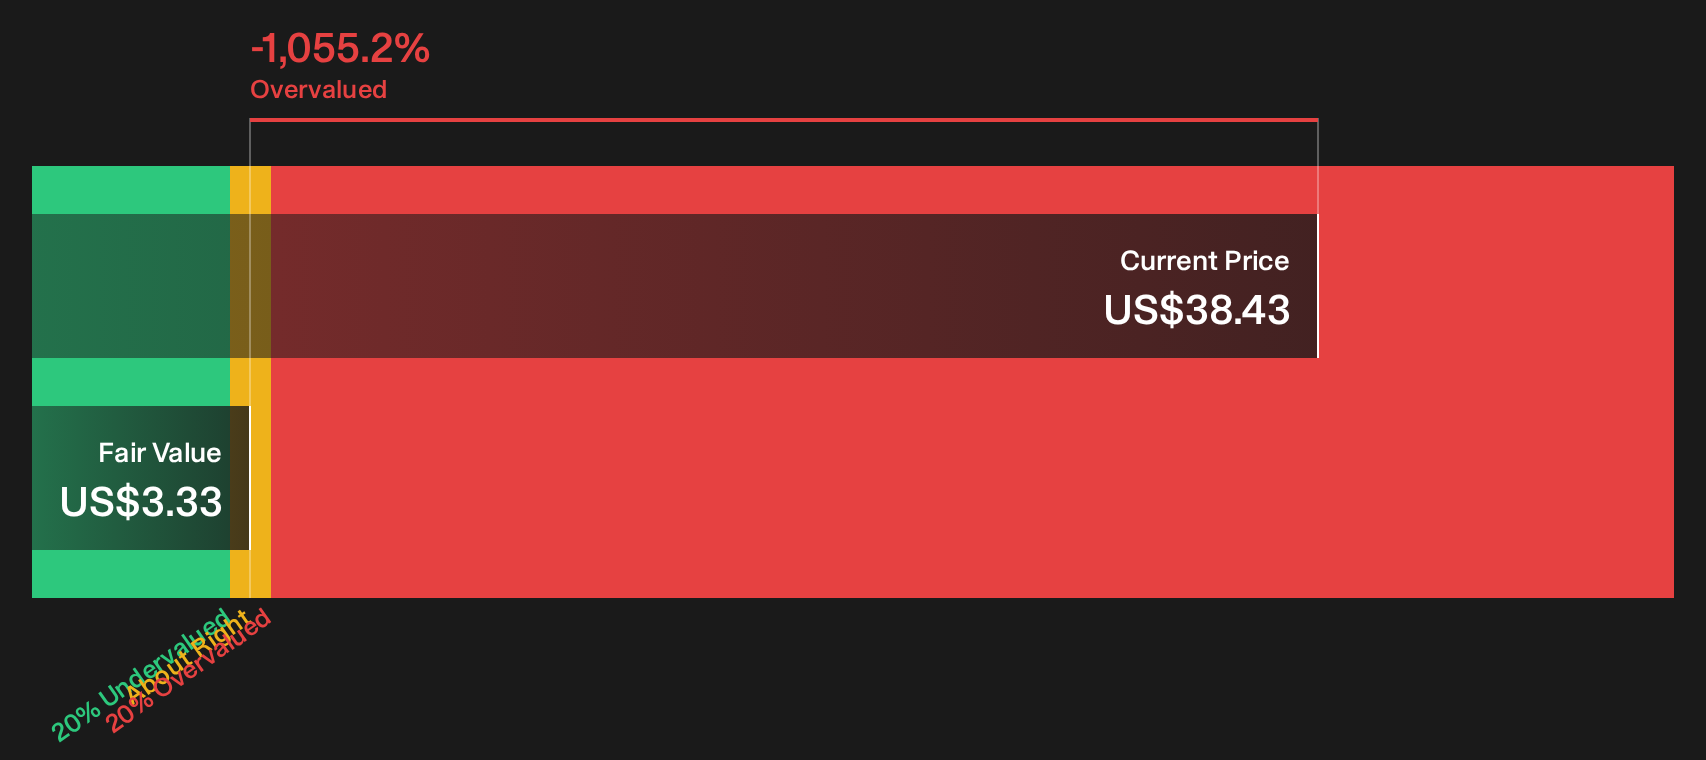
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Greenbrier Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these around Greenbrier Companies rarely last long, so consider reviewing the data for yourself and weighing both sides of the argument. To see both the upside potential and the key concerns side by side, start with the 3 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Greenbrier Companies?
Greenbrier Companies gives useful clues, but your next strong move often comes from comparing it with other opportunities that fit clear, disciplined criteria.
- Target resilient balance sheets and steady fundamentals by scanning a focused list of solid balance sheet and fundamentals (25 results) that prioritises financial strength over hype.
- Hunt for potential value opportunities by reviewing a curated 28 high quality undervalued stocks where pricing and fundamentals can look better aligned.
- Build a cash-focused portfolio by checking a handpicked 8 dividend fortresses that aims to pair higher yields with business durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com