
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ramsay Générale de Santé (ENXTPA:GDS) Faces A Boardroom Test Following Its Valuation Gap
Ramsay Générale de Santé (ENXTPA:GDS) has called a board meeting for 6 October 2026 to review the auditors’ certification report on its consolidated accounts and to address other corporate matters that could refine investor expectations.
Ramsay Générale de Santé’s share price has been volatile, with a 7 day share price return of 2.9% after a 30 day decline of 5.1% and a 90 day fall of 11.1%. The 1 year total shareholder return of 6.9% contrasts with a 3 year total shareholder return decline of 53.2%, suggesting that recent momentum has picked up slightly against a weaker longer term record as investors weigh upcoming board level decisions.
Spot opportunities around Ramsay Générale de Santé by comparing this board-driven reset with financially robust healthcare peers, screened through list of solid balance sheet and fundamentals (204 results).After a short burst of strength on a still bruised three year record, Ramsay Générale de Santé now asks a simple question: Does the current price still offer enough upside potential for the risks on the table?
Preferred Price-to-Sales of 0.2x: Is it justified?
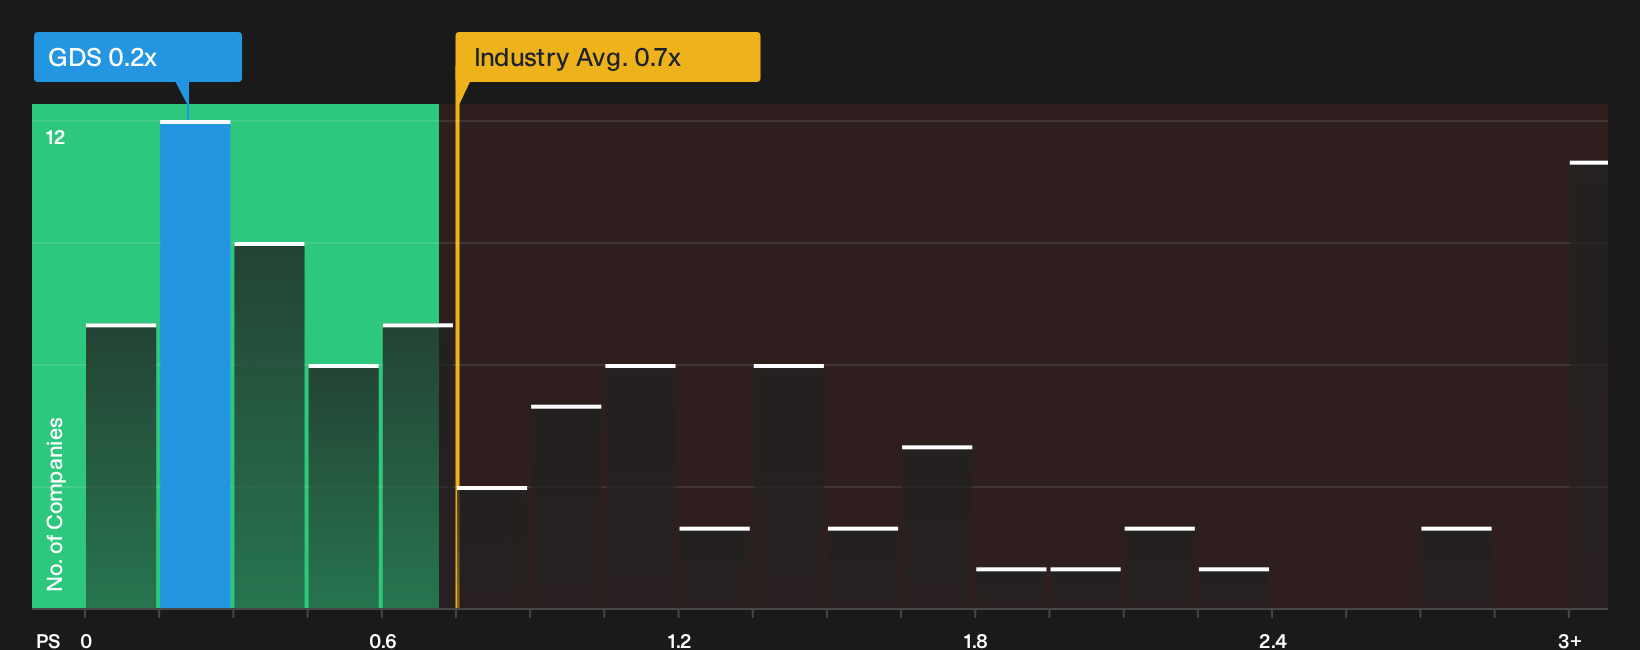
On Simply Wall St metrics, Ramsay Générale de Santé screens as inexpensive, trading at a 69% discount to an estimated future cash flow value of €32.15 per share, with the last close at €9.96 and a reported P/S ratio of 0.2x that sits well below peers.
The price to sales multiple compares the total equity value of the group to its annual revenue of €5,381.1m and gives you a rough sense of how much investors are paying for each euro of turnover. For a healthcare operator like Ramsay Générale de Santé, which is currently loss making with net income of a €41.5m loss and a negative return on equity of 2.29%, earnings based ratios are harder to use, so revenue based measures often become the first reference point.
The current DCF output suggests a fair value of €32.15 per share using the SWS DCF model, a framework that projects future cash flows and discounts them back to today using a required rate of return. That kind of model can be sensitive to assumptions, yet it anchors the discussion around the ability of the business to convert its hospital and care capacity into cash over time rather than short term accounting profits.
Ramsay Générale de Santé operates across France and the Nordics, reports unprofitable results and faces interest costs that are not well covered by earnings. This helps explain why the market may be cautious despite the low P/S multiple. For investors, the tension is between those balance sheet and profitability pressures and a valuation gap that the DCF output frames as substantial if future cash generation moves closer to the model path.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of €32.15 (UNDERVALUED)
Still, the unprofitable €41.5m net loss and interest costs that earnings do not comfortably cover could challenge the bullish Ramsay Générale de Santé valuation story.
Find out about the key risks to this Ramsay Générale de Santé narrative.
Another View On Ramsay Générale de Santé’s Valuation
Ramsay Générale de Santé looks inexpensive on a simple P/S of 0.2x compared with 0.8x for the wider European healthcare sector and 0.6x for peers. That gap points to either meaningful mispricing or a clear quality discount. The key question is which side of that trade you are on as risks and cash flows evolve.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ramsay Générale de Santé for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Ramsay Générale de Santé’s valuation and risk profile can feel messy, so act while the data is fresh and pressure test the full picture for yourself using the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Ramsay Générale de Santé?
If Ramsay Générale de Santé has you rethinking your watchlist, now is the moment to widen your search while valuations and risks are front of mind.
- Target stability first by reviewing a 222 resilient stocks with low risk scores that filters for businesses with resilient profiles when conditions change.
- Hunt for quality at a discount with the 174 high quality undervalued stocks that focuses on companies combining solid fundamentals with appealing pricing.
- Build a cash flow focused portfolio using the 223 dividend fortresses that highlights income ideas offering yields above 5%.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com