
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Barcelona Water Contract Altering The Investment Case For Veolia (ENXTPA:VIE)?
- Veolia Environnement recently won a €1b, 25 year tender from the Metropolitan Council of Barcelona to manage drinking water services for eight municipalities, covering more than 230,000 residents and including leak detection sensors, digital control centers, meter upgrades and an electrified vehicle fleet.
- The Barcelona win reinforces Veolia Environnement’s push toward long duration, technology heavy water contracts that can support operational efficiency, regulatory compliance and long term service resilience in drought exposed regions.
- Attention now turns to how Veolia Environnement’s investment narrative could be reshaped by this 25 year Barcelona water management mandate.
Veolia Environnement Investment Narrative Recap
To own Veolia Environnement, you need to be comfortable with a utility style story built on long contracts, heavy capex and gradual efficiency gains rather than sharp swings in quarterly numbers. The Barcelona mandate fits that picture, as does the Princeton Meadows facility, both pointing to more complex water work and tighter links to regulation and climate resilience.
The key short term swing factor is still execution on the existing backlog and efficiency programs that underpin margin ambitions, not these individual wins alone. The biggest risk remains project delays or operational hiccups that slow cash generation when debt is already flagged as not well covered by operating cash flow.
The Princeton Meadows wastewater upgrade is the clearest operational echo of Barcelona. It adds another reference site with advanced treatment, UV disinfection, energy efficient equipment and climate resilient design. This directly ties into Veolia Environnement’s push toward higher value, technology heavy services in water and wastewater.
For catalysts, this kind of US project matters because it shows Veolia Environnement working at the intersection of water reuse, stricter environmental standards and energy efficiency. These are all areas analysts already highlight as drivers for Water Technologies and municipal contracts. Execution quality here will influence how confidently investors treat the wider pipeline and the associated debt load.
Veolia Environnement’s current analyst story points to revenues of €50.8b and earnings of €1.9b by 2029, based on 4.5% yearly revenue growth and an earnings uplift of about €0.6b from the €1.3b reported today.
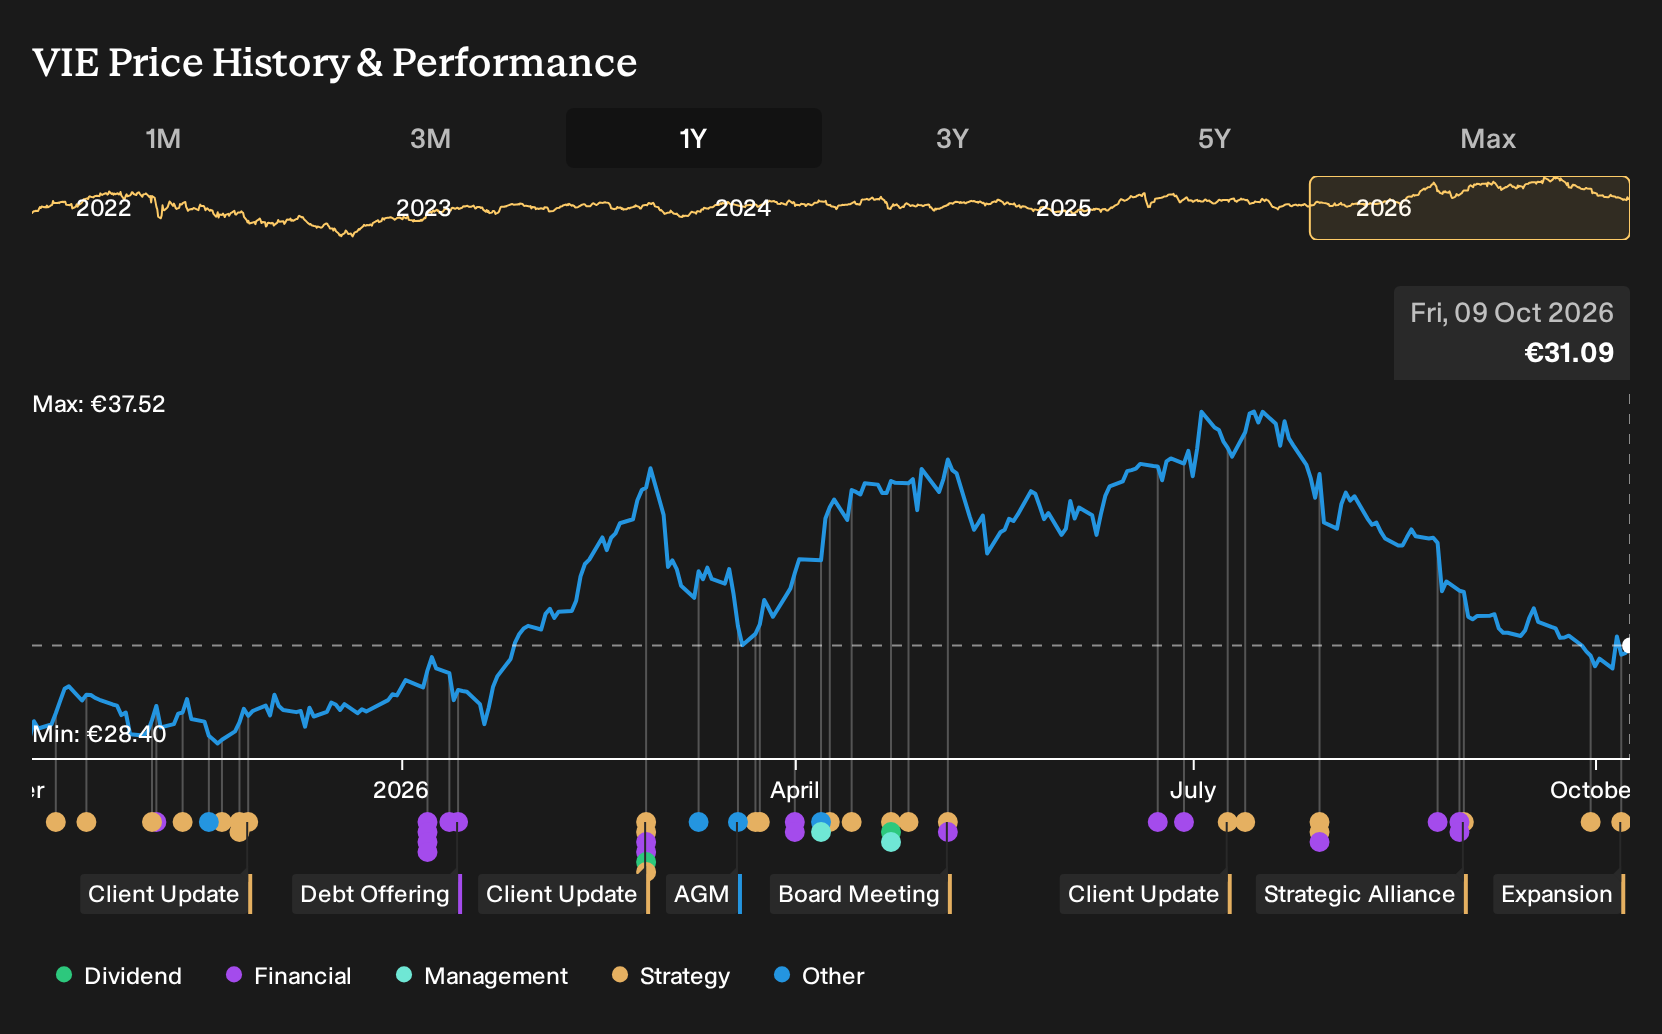
Uncover why Veolia Environnement's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Veolia Environnement’s earnings trajectory at the center. The most optimistic analysts were already pencilling in €53.9b of revenue and €2.2b of earnings by 2029, before the Barcelona win and Princeton Meadows ribbon cutting. You can treat those higher forecasts as one possible path and compare them with your own expectations.
Explore 5 other Veolia Environnement fair value estimates, including one that suggests potential upside of up to 136% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Veolia Environnement research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Veolia Environnement. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veolia Environnement's overall financial health at a glance.
Looking For More Investment Ideas Beyond Veolia Environnement?
If the Veolia Environnement story has you thinking about resilience, contracts and balance sheets, it can help to widen the lens and see how other companies stack up on similar themes using the Simply Wall St screener.
- If you want businesses that combine financial resilience with relatively low risk scores, start with a 222 resilient stocks with low risk scores that may better match your comfort with volatility.
- If your focus is on quality at a measured price, scan through 174 high quality undervalued stocks and compare their fundamentals to what you see at Veolia Environnement.
- If you are building a portfolio around income resilience, put time into assessing 223 dividend fortresses that offer yields above 5% and may complement a core holding like Veolia Environnement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com