
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
North Atlantic Energies (ENXTPA:NAE) Could Be 91% Undervalued Following Half Year Earnings
North Atlantic Energies earnings trigger fresh look at the stock
North Atlantic Energies (ENXTPA:NAE) just released half year results to June 30, 2026, showing sales and revenue broadly steady while the net loss narrowed sharply, a shift that can reset how investors view ongoing performance.
Recent trading has been choppy for North Atlantic Energies, with the share price down 16.3% over the past month after a strong 56.1% three month share price return. The year to date share price gain of 82.7% and a one year total shareholder return of 131.9% point to momentum that has built over a longer stretch as investors reassess the business after the half year loss narrowed.
Expand your watchlist beyond North Atlantic Energies and review hand-picked peers with resilient balance sheets and fundamentals through our list of solid balance sheet and fundamentals (204 results) to see how they compare on quality and risk.
North Atlantic Energies now trades after a sharp run and a much smaller loss, yet still at a very large discount to estimated fair value. Is the market being prudently cautious, or is it mispricing the turnaround risk and reward?
Price-to-Sales of 0.1x: Is it justified for North Atlantic Energies?
On simple valuation grounds, North Atlantic Energies screens as very cheap, with a P/S ratio of 0.1x against a share price of €82.35, while peers in the European Oil and Gas industry trade on 1.7x and a direct peer group on 3.7x sales.
The P/S multiple compares the market value of the equity to the revenue that the business generates, which can be helpful when a refiner is loss making and earnings based measures like P/E are less informative. For North Atlantic Energies, investors are currently paying €0.10 for each euro of sales, compared to €1.70 at the broader industry level and an even higher figure across similar companies.
Such a low P/S ratio, alongside an internal estimate that the shares trade 91.4% below an assessed fair value based on a future cash flow value of €961.08, suggests the market is pricing in meaningful concerns about the sustainability of profits, the balance sheet and the 73.11% dividend payout that is not covered by earnings or free cash flow. The discount compared to both the sector and peers is very large, which indicates sentiment around the unprofitable track record and weak financial position is much more cautious than the sector average.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 0.1x (UNDERVALUED)
Still, North Atlantic Energies carries clear pressure points, including ongoing net losses and a dividend payout that is not supported by current earnings or free cash flow.
Find out about the key risks to this North Atlantic Energies narrative.
Another view on North Atlantic Energies valuation
The P/S discussion tells only part of the story. Our DCF model presents a contrasting view, with an assessed future cash flow value of €961.08 per share compared with the current €82.35 price, which indicates a very large gap that could reflect either potential mispricing or substantial embedded risk. Look into how the SWS DCF model arrives at its fair value.
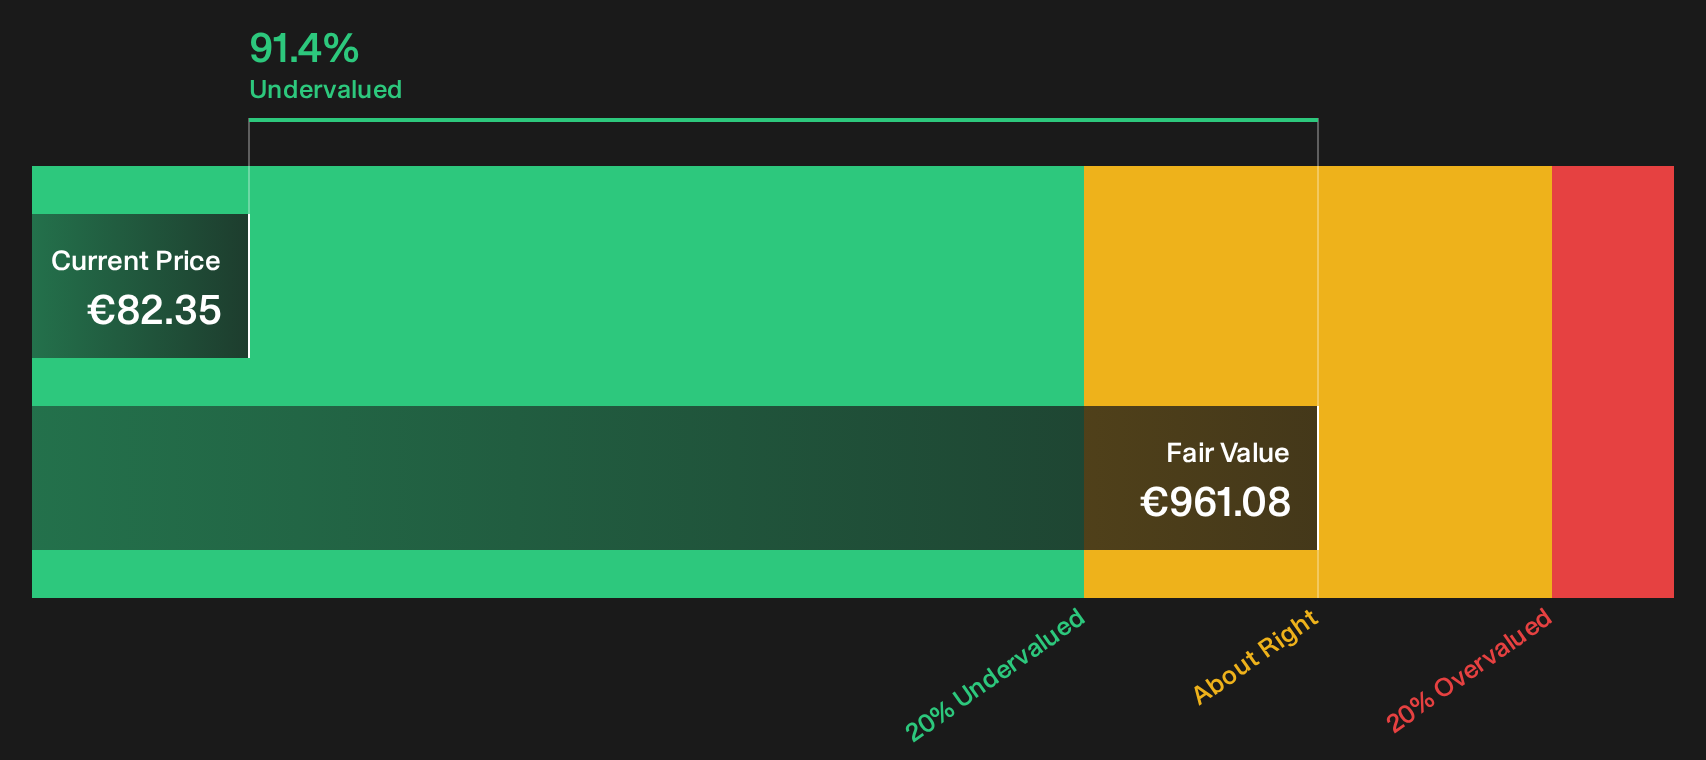
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out North Atlantic Energies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around North Atlantic Energies can feel confusing. Move quickly from headline reactions to your own view by weighing both sides of the story with the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond North Atlantic Energies?
North Atlantic Energies gives you one angle. Casting a wider net with structured screeners helps you benchmark its story against other opportunities and avoid blind spots.
- Target stronger pricing power by scanning for companies that score well on value and quality using our 174 high quality undervalued stocks.
- Strengthen your income stream by focusing on payouts that aim for resilience with the 223 dividend fortresses.
- Dial down portfolio stress by filtering for businesses with lower risk profiles through the 222 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com