
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Gilead Sciences (GILD) Could Be Trading At A 18% Premium Following Strong Earnings
Gilead Sciences (GILD) moved back into focus after a strong quarterly report, with revenue growth topping analyst expectations and management lifting its HIV sales outlook for 2026 despite pressure in other products.
Gilead Sciences has ridden that earnings surprise into a strong run, with the share price up 16.44% over 90 days and a 24.32% year to date share price return. The 1-year total shareholder return of 32.19% points to momentum that has been building rather than fading.
Spot emerging momentum beyond Gilead Sciences by scanning a curated set of resilient healthcare and pharma names in our 31 resilient stocks with low risk scores.Bulls see a high free cash flow yield and rising HIV guidance as evidence that Gilead Sciences is mispriced. Bears point to recent losses and pressure outside HIV. Which story does the valuation appear to support next?
Most Popular Narrative: 17.8% Overvalued
The most followed narrative on Gilead Sciences pegs fair value at $128.38, which sits below the last close of $151.17 and suggests that expectations have moved ahead of that price anchor.
Gilead is transitioning from a “single-franchise HIV company” into a multi-platform biopharma with high-probability growth drivers like lenacapavir and Trodelvy, as well as potential opportunities in cell therapy and immunology. At the same time, temporary earnings headwinds from acquisition charges and integration work are affecting reported profitability and can make the long-term value story harder to see in the current numbers.
See why 18 investors see Gilead Sciences as 18% overvalued.
Result: Fair Value of $128.38 (OVERVALUED)
Still, two pressure points could flip this Gilead Sciences story: weaker than expected oncology or cell therapy traction, and any stumble in integrating recent acquisitions.
Find out about the key risks to this Gilead Sciences narrative.
Another View: Cash Flow Signals On Gilead Sciences
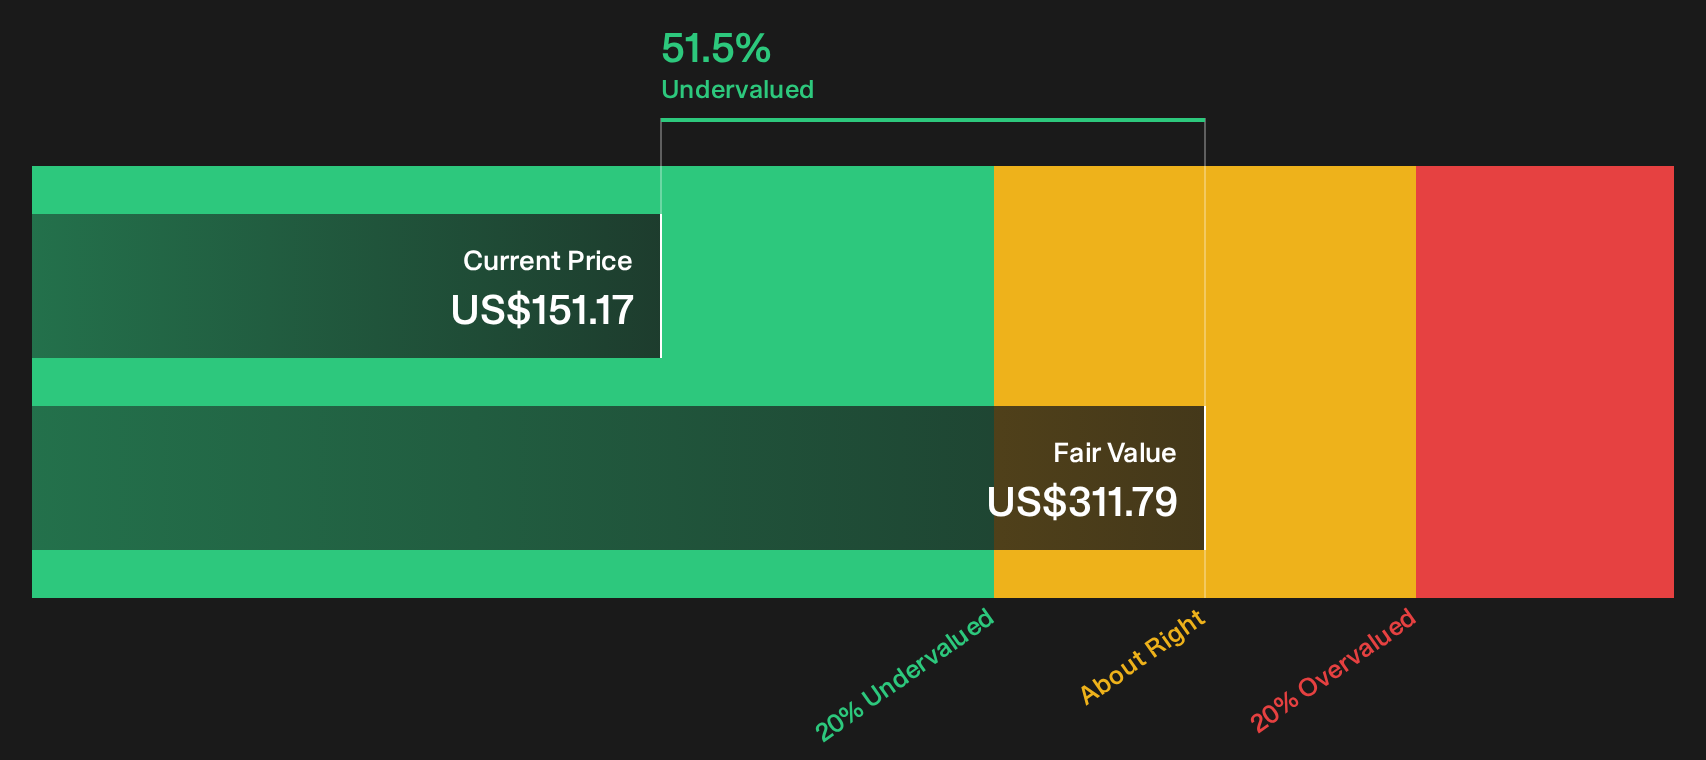
The user narrative points to Gilead Sciences trading 17.8% above an estimated fair value of $128.38. Our DCF model sends a very different message. It values future cash flows at $311.79 per share, which is more than double the recent price of $151.17.
That gap hints at either a cautious narrative model or optimistic cash flow assumptions in the SWS DCF model. Every reader has to decide which framework feels more realistic for Gilead Sciences over the long haul.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views like these only matter if you test them against the numbers yourself and move before sentiment shifts again, so weigh both sides carefully, then dig into the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Gilead Sciences?
If you stop with Gilead Sciences, you risk missing other opportunities with stronger balance sheets, income potential, or mispriced quality that might fit your portfolio even better.
- Target resilient balance sheets and steady fundamentals by scanning a focused list of solid balance sheet and fundamentals (25 results) that can help you filter for financial strength quickly.
- Hunt for mispriced quality by reviewing the 28 high quality undervalued stocks and see which stocks the data suggests may offer more for each dollar invested.
- Build a portfolio that works harder for your income goals by screening companies in the 8 dividend fortresses and spotting yields that meet your targets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com