
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Valeo's Run? What Holders Had To Believe
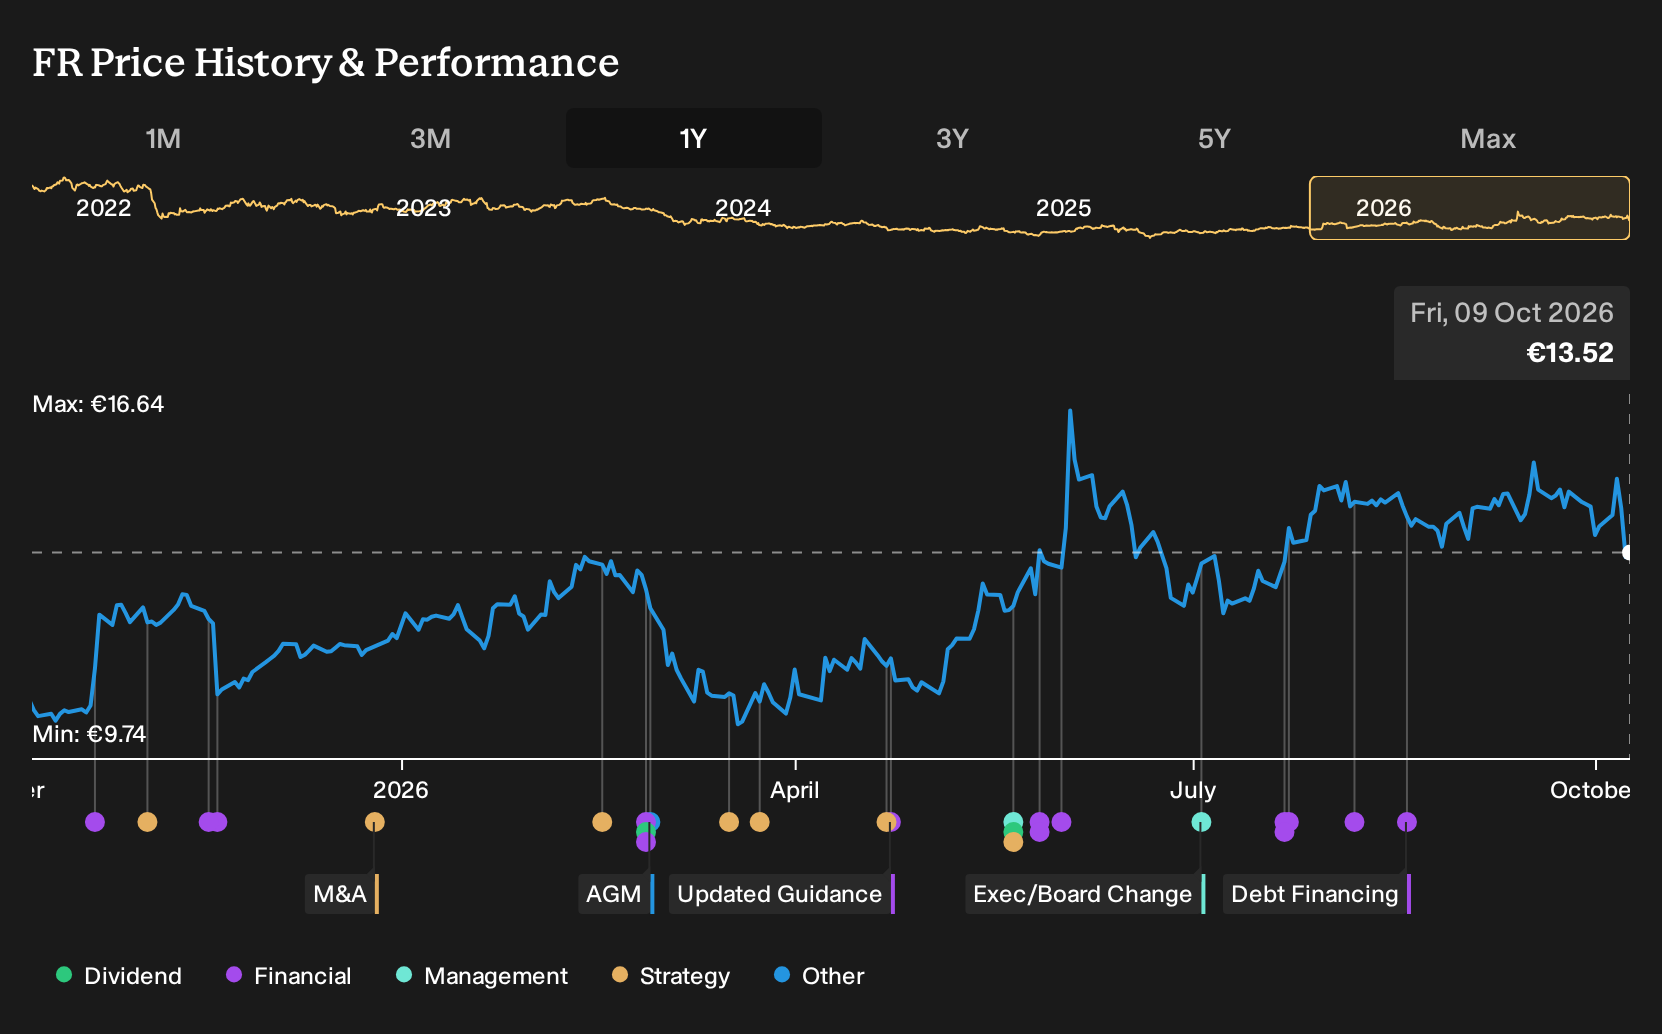
Valeo’s new contract to supply a radar suite for a North American EV maker’s L2+ and L3 systems put its ADAS tech in the headlines, yet the real story for investors sat in the payoff. Investors who held Valeo over the past year are up 40.9%, including dividends. If you were weighing a purchase on 9 October 2025, what exactly did you need to believe about electrification and driver assistance to back that outcome?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Valeo. Zero in on 174 high quality undervalued stocks for companies trading below our estimates.
The Two Valeo Stories Investors Had To Weigh
The shares cost €10.06 at the start of the period, and buyers had to decide which story about Valeo felt more believable.
The bullish narrative put fair value at €11.50. It leaned on electrification, ADAS and smart lighting, plus expectations of revenue rising 1.6% a year and profit margins reaching 4.0% by 2028.
The bearish view set fair value at €8.15. That camp focused on electrification order cancellations, weaker high voltage powertrain prospects and trade risks around cross border production.
What The Evidence Around Valeo Actually Tested
Valeo’s radar contract for a North American EV maker backed the bullish view that ADAS and software heavy content could matter more than canceled high voltage orders. H1 2026 results told a tighter story. Revenue of €10,378m sat below H1 2025, while net income was roughly flat and the net margin stayed at 1.0%. The evidence cut both ways.
The lesson is simple. When a thesis leans on higher quality content, check whether contract wins show up in order intake, margin and cash generation, not just in headlines.
What Valeo’s 41% Run Already Prices In
Today Valeo trades at €13.52. The selected Narrative puts its Fair Value below that level, arguing that recent electrification setbacks and order cancellations leave less room for error, even after progress on Elevate 2028, ADAS content and debt reduction.
The key question for a buyer now is whether Valeo can keep lifting margins and cash flow while holding share against lower cost rivals, despite weaker high voltage powertrain visibility.
"Weakness in the electrification segment and order cancellations have heightened risk to future top-line performance and growth prospects. Rising geopolitical risks and high investment needs, combined with industry volatility, threaten both margins and market share retention."
The price and this Narrative do not agree. → Uncover what this Narrative says Valeo is actually worth
Where Valeo’s Story Connects Next
Once you have tested Valeo’s thesis, you can look sideways. Electrification and driver assistance rely on more than sensors and wiring.
Drivers still worry about range, charging time and day to day convenience. Another EV specialist is trying to solve that bundle of problems directly.
This business runs its own charging and battery swap network, built around a software heavy ownership model.
It lets users treat energy and servicing as a recurring package, not a one off headache.
If more buyers want premium tech and less hassle, that kind of bundled ecosystem could matter as much as any single component supplier.
That argument has a Narrative and a number behind it. → See the company one Narrative values 78% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com