
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Glacier Bancorp (GBCI) Screens As Undervalued, Is The Market Missing Its Fair Value?
Glacier Bancorp (GBCI) has drawn fresh attention after its share price closed at US$42.73 on 9 October 2026, with recent returns lagging over the month and the past 3 months.
Over the past year Glacier Bancorp has seen its share price weaken in the short term, with the 30 day share price return down 6.62% and the 90 day move down 17.01%. At the same time, the 3 year total shareholder return of 57.51% points to a much stronger longer run journey despite a 4.77% decline in the past 12 months. This suggests that recent selling reflects cooler momentum and shifting views on risk rather than a simple one way story.
Compare Glacier Bancorp's recent pullback with other banks that combine resilient financials and potential re-rating candidates by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Glacier Bancorp now trades at a sizeable discount to both analyst targets and one intrinsic value estimate after a rough 3 months. Is that a cautious market reading the risks correctly, or is it mispricing a solid regional bank?
Most Popular Narrative: 23.5% Undervalued
On the most followed view, Glacier Bancorp screens as undervalued, with a narrative fair value of about $55.83 against the recent $42.73 close. That gap focuses attention on whether margin gains, efficiency targets and acquisitions can keep supporting earnings.
The main factor that has to go right is that Glacier Bancorp continues to sustain low credit losses and stable core deposit costs while integrating Bank of Idaho and Guaranty Bank & Trust into a more efficient, higher margin franchise.
The current valuation implies that the market is discounting Glacier Bancorp’s recent net interest margin gains, efficiency ratio improvement, and earnings growth, which supports the view that the stock may be undervalued and that the narrative remains positive.
See why 4 investors see Glacier Bancorp as 23% undervalued.
Result: Fair Value of $55.83 (UNDERVALUED)
Still, the Glacier Bancorp story can change quickly if progress on the net interest margin stalls or if loan and deposit growth tilts toward lower quality segments.
Find out about the key risks to this Glacier Bancorp narrative.
Another View: Glacier Bancorp Looks Rich On Earnings
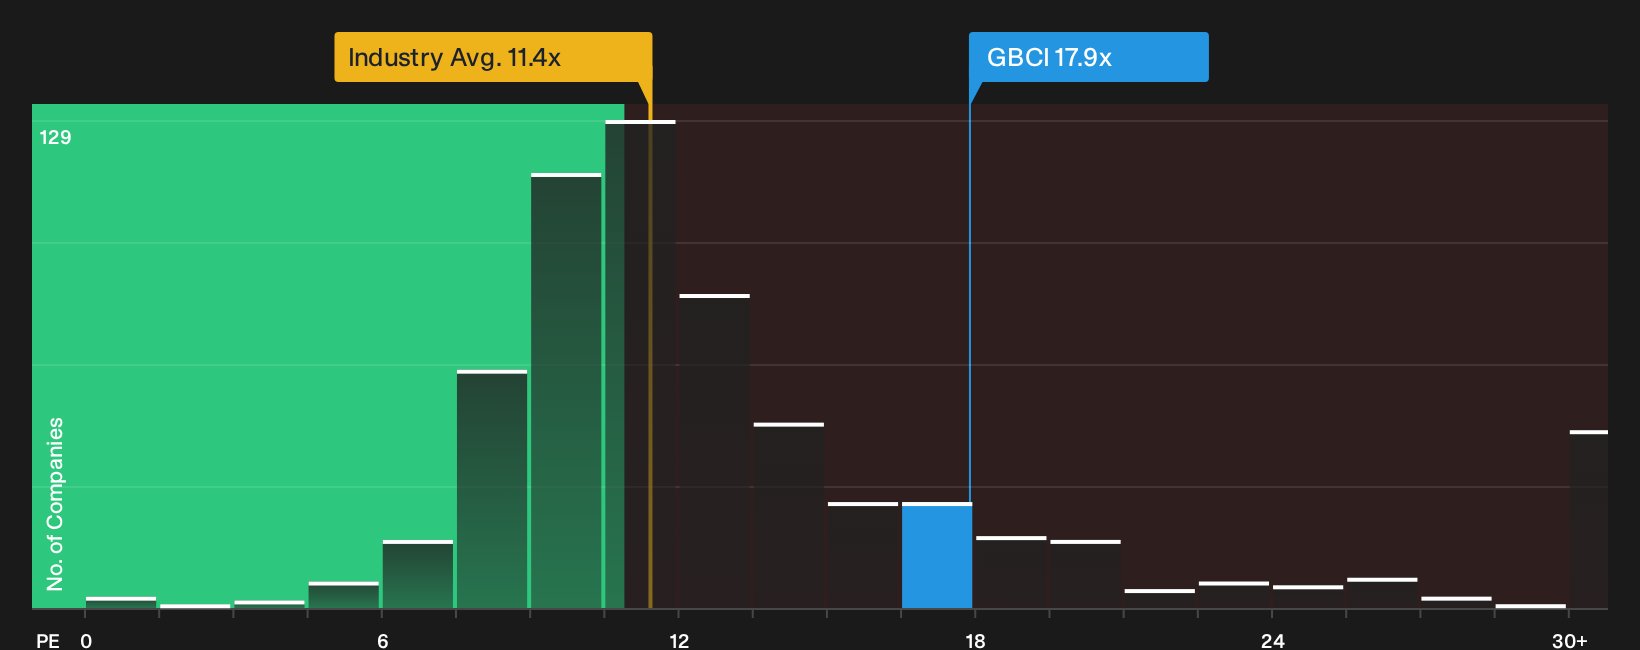
The story shifts when you look at Glacier Bancorp through its P/E ratio. The stock trades on 17.9x earnings, which is well above the US Banks industry at 11.5x and above its own fair ratio of 15.2x. That richer multiple tilts the conversation toward valuation risk. Is the market already paying up for much of the good news?
For a closer look at how this earnings multiple compares with both peers and Glacier Bancorp's own fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Glacier Bancorp drawing mixed reactions on value and risk, you should pressure test the numbers yourself and consider acting before sentiment shifts again. Start by weighing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Glacier Bancorp?
If Glacier Bancorp has you reassessing your watchlist, now is the moment to scan fresh opportunities so you do not miss the next move.
- Target potential mispricings by reviewing companies that screen as quality businesses trading below their estimated value through the 28 high quality undervalued stocks.
- Lock in income-focused opportunities by zeroing in on companies screened as potential 8 dividend fortresses with robust payouts backed by fundamentals.
- Strengthen your defensive side by scanning a 31 resilient stocks with low risk scores that surfaces businesses with more resilient risk profiles and steadier return potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com