
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Moog (MOG.A) Below Fair Value As Argus Cuts Its Target To $395?
Moog (MOG.A) is back on investor radar after Argus reduced its projected value for the stock to $395. This has prompted fresh questions about how the aerospace and defense controls specialist is currently being valued.
Recent trading has cooled after a strong run. The share price is at $363.09, with the 7 day share price return down 7.55% and the 90 day share price return down 10.81%. However, the year to date share price return is 45.31% and the 1 year total shareholder return is 78.57%. This indicates longer term momentum for Moog despite the recent pullback as investors reassess growth prospects and risk around the current valuation.
Scan how Moog compares across the aerospace and defense controls space by reviewing the hand picked 91 robotics and automation stocks that could be next in line for sharp re-ratings.
Moog now trades below the Argus target and at a discount to broader analyst expectations, yet the pullback signals market hesitation. Is that caution mispricing the controls specialist or simply marking fair value discipline?
Most Popular Moog Narrative: 19% Undervalued
Against a last close of $363.09, the most followed Moog valuation storyline anchors on a fair value of $446.40, so the current pullback is being framed as a discount rather than a warning sign by that camp.
Moog is positioned to benefit from a sustained increase in global defense spending, with significant order backlog and direct exposure to U.S., NATO, and Indo Pacific modernization programs. These factors are likely to drive multi year revenue growth and increased earnings stability.
See why 21 investors see Moog as 19% undervalued.
Result: Fair Value of $446.40 (UNDERVALUED)
Still, the Moog story could be knocked off course if higher than expected tariff costs squeeze Commercial Aircraft profitability or if free cash flow again feels the strain of heavier investment.
Find out about the key risks to this Moog narrative.
Another View On Moog’s Valuation
The analyst narrative presents Moog as roughly 19% undervalued relative to a fair value estimate of $446.40. A different lens tells a sharper story. The SWS DCF model values the future cash flows at $179.72 per share, which is well below the current $363.09 price and, by that metric, screens as overvalued. Which perspective do you think better reflects your expectations for Moog’s cash generation?
To see how this cash flow driven approach compares with the narrative fair value and analyst targets, Look into how the SWS DCF model arrives at its fair value.
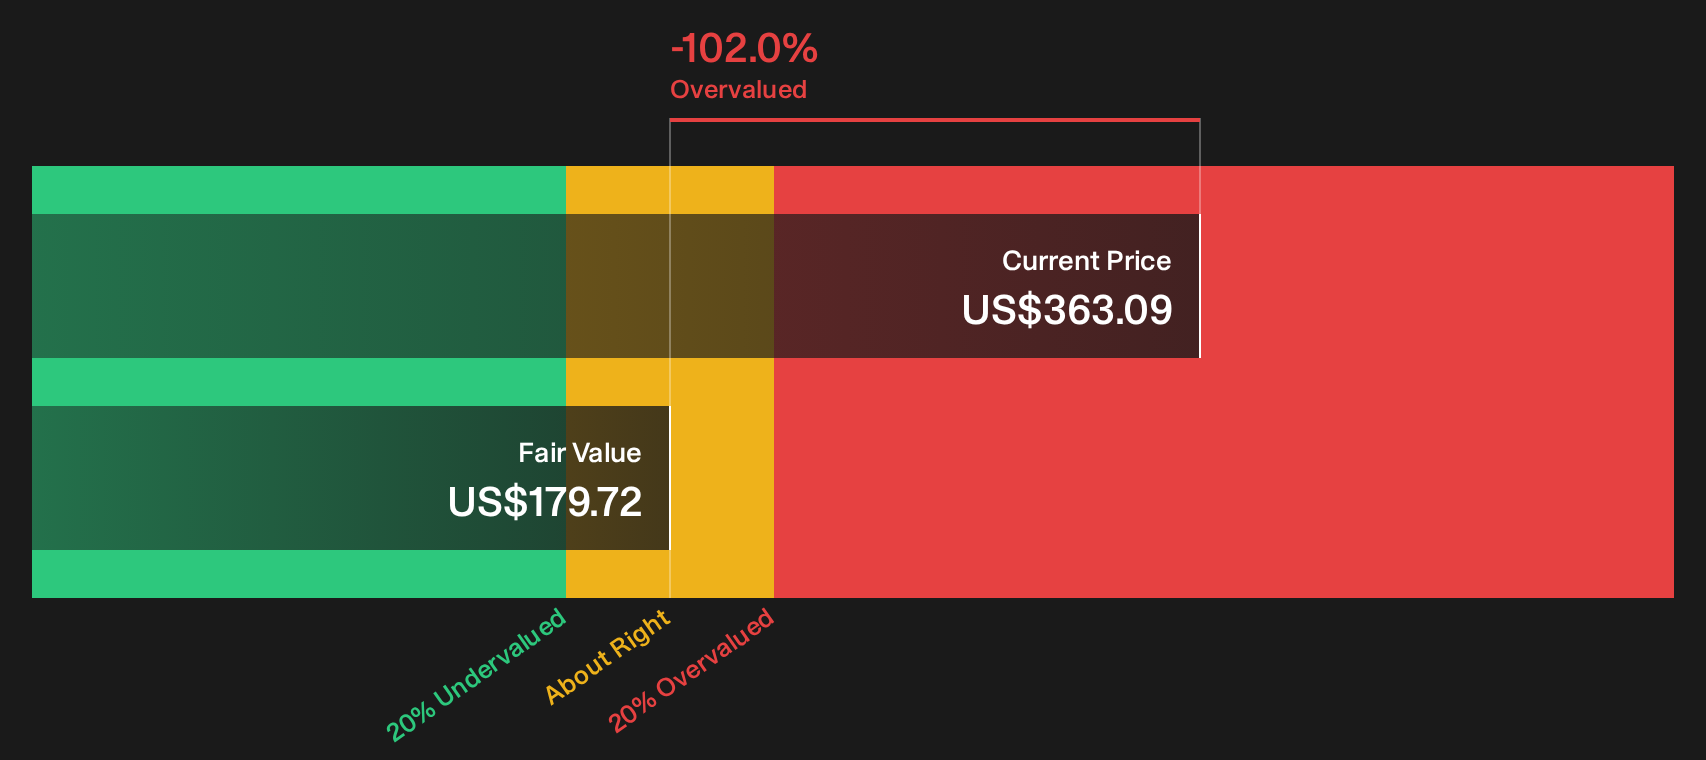
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Moog for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Moog split between optimism and discipline, it helps to move quickly, review the underlying metrics, and reach your own judgment. To see what enthusiastic investors are focusing on, start with the 3 key rewards.
Looking for more Moog investment ideas?
If you are weighing Moog against fresh opportunities, do not stop here. Put Simply Wall Street’s screener to work and uncover other data driven ideas before the crowd does.
- Target reliable compounding by scanning companies that combine income with resilience through the 8 dividend fortresses.
- Hunt for mispriced opportunities where fundamentals outclass the share price using the 28 high quality undervalued stocks.
- Prioritize peace of mind and focus on durability first with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com