
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Yoshinoya Holdings Stock In Focus As Board Reviews Interim Dividends
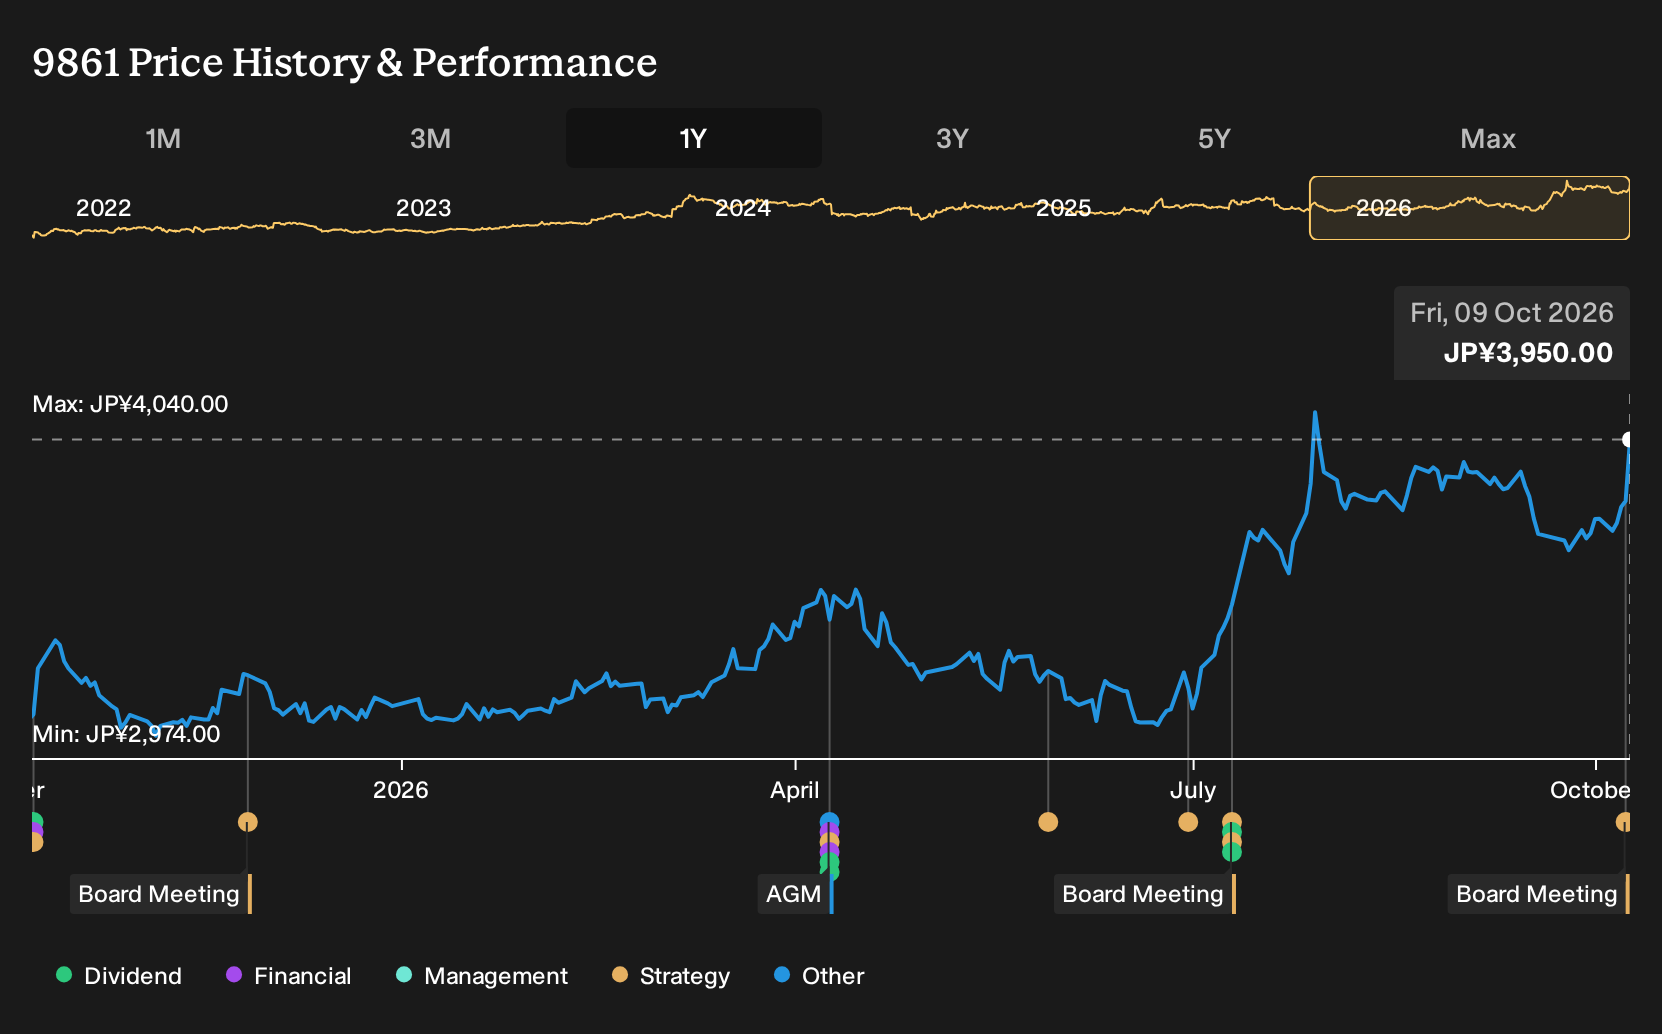
- Yoshinoya Holdings has scheduled a board meeting on October 8, 2026 to consider an interim dividend from retained earnings with an August 31, 2026 record date and to review the planned interim dividend for the August 31, 2027 record date.
- The focus on both current and future interim dividends highlights how Yoshinoya Holdings is reassessing capital allocation, cash needs and shareholder payout expectations over a multi year window, rather than treating each distribution decision in isolation.
- The next area of attention is how this renewed focus on interim dividends could influence Yoshinoya Holdings' broader investment narrative for shareholders.
What Is Yoshinoya Holdings' Investment Narrative?
To own Yoshinoya Holdings, you need to be comfortable with a very execution driven story. This is a restaurant operator that lives or dies on store level efficiency, consistent demand for beef bowls and noodles, and the ability to hold pricing without eroding traffic. Earnings growth of 48.5% over the past year and improving profit margins to 2.5% show what tighter operations can do, although return on equity at 8.3% still looks modest for a consumer brand.
The board’s fresh look at interim dividends fits into that operational picture rather than redefining it. A payout review can signal confidence in cash generation and capital discipline, but it does not remove the near term pressures of labor costs, ingredient pricing, and capital spending for new formats. The stock already trades on a P/E of 44.1x, above the JP hospitality average, so any shift in dividend policy sits alongside the broader questions around future earnings quality and growth.
Even so, there is a less comfortable angle to Yoshinoya Holdings that starts with how it is funded and...
There's only one way to know the right time to buy, sell or hold Yoshinoya Holdings. Head to Simply Wall St's company report for the latest analysis of Yoshinoya Holdings's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Yoshinoya Holdings research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Yoshinoya Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yoshinoya Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Yoshinoya Holdings?
If you want to put Yoshinoya Holdings in context, it helps to line it up against other stocks with different income, quality, and risk profiles. The Simply Wall St Screener gives you a quick way to compare opportunities and pressure test whether Yoshinoya fits the role you want it to play in your portfolio.
- If income is the priority, scan a curated set of dependable payers through our 28 dividend fortresses and see how their yields and fundamentals compare with Yoshinoya Holdings.
- If quality at a reasonable entry price matters more to you, check out the 12 high quality undervalued stocks that pair solid business profiles with valuations that may leave more room for upside.
- If capital preservation sits higher on your list, start with a 23 resilient stocks with low risk scores that screens for balance sheets and risk profiles designed to keep volatility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com