
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Forestar Group (FOR) Missed Estimates And Cut Guidance, Is It Still Undervalued?
Forestar Group (FOR) has come under pressure after its latest quarterly update, where the residential lot developer missed Wall Street expectations on both revenue and earnings per share and outlined softer full-year guidance versus peers.
That weaker guidance has quickly fed through to the chart, with Forestar Group’s share price falling 15.93% over the past 90 days and 4.68% over the last month. Even though the year-to-date share price return is still 5.47% and the 5-year total shareholder return sits at 31.54%, this signals fading near-term momentum after a much stronger multi-year run.
Stress test your thesis on Forestar Group by comparing it with a curated list of solid balance sheet and fundamentals (25 results) that have also drawn attention after guidance or earnings surprises.
Forestar Group now trades well below the average analyst target and yet above one intrinsic value estimate. Is the recent slide closing a gap to fair value, or opening one up?
Most Popular Narrative: 25% Undervalued
Against Forestar Group’s last close at $25.65, the most followed narrative anchors fair value at $34.00. This frames the recent drawdown as a valuation gap rather than just sentiment fatigue.
The main thing that has to go right is that Forestar Group converts its large contracted lot backlog and planned US$1.4b of land and development spending into consistently profitable lot sales, despite recent volume declines, margin pressure, and negative free cash flow.
The current valuation implies that Forestar Group is priced for ongoing demand risks and capital efficiency concerns, even though the company has strong liquidity, a sizeable contracted lot base, and a long-term goal to increase the share of D.R. Horton homes built on Forestar-developed lots.
See why 12 investors see Forestar Group as 25% undervalued.
Result: Fair Value of $34 (UNDERVALUED)
Still, the Forestar Group story can break if lot volumes keep sliding while returns on invested capital weaken, or if prolonged margin pressure leads to persistently lower profitability.
Find out about the key risks to this Forestar Group narrative.
Another View: Cash Flows Point The Other Way
Forestar Group screens as undervalued on the $34 fair value narrative, yet the SWS DCF model tells a different story. On that cash flow based lens, the stock at $25.65 sits above an estimated value of $20.97, which frames the shares as overvalued instead of cheap.
This gap between earnings based and cash flow based estimates raises a practical question for investors. Which matters more to you, the near term earnings power or the cash the business is expected to generate over time, and how does that shape the price you are willing to pay today?
Look into how the SWS DCF model arrives at its fair value.
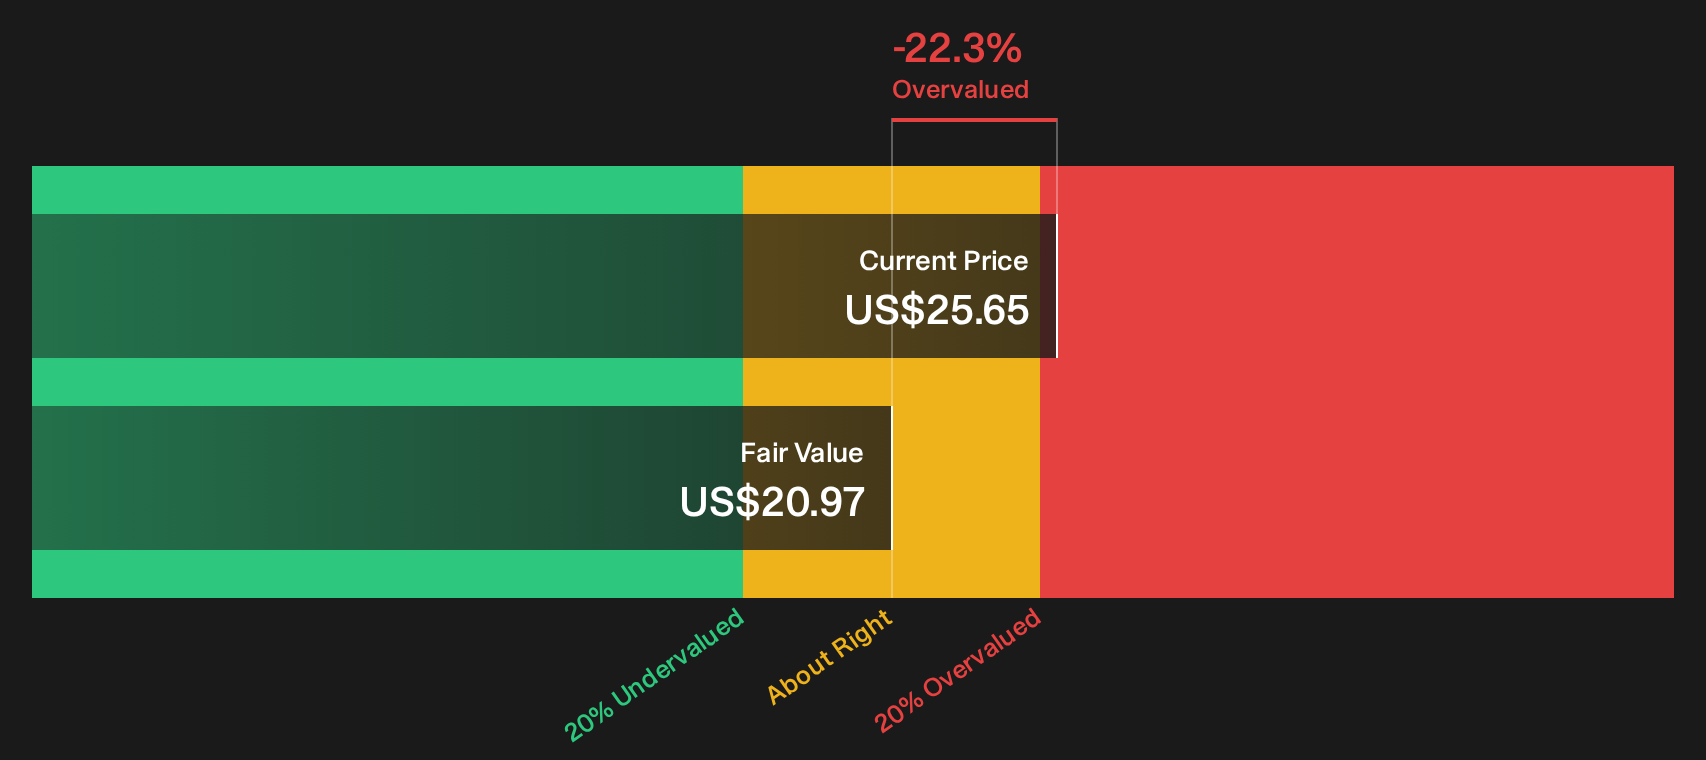
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Forestar Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Unsure whether the mix of opportunity and risk around Forestar Group fits your approach, or confident in your view? Act quickly and pressure test that perspective against 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Forestar Group?
If Forestar Group has sharpened your thinking, do not stop here. Broaden your watchlist and give yourself more options before the next move hits.
- Target steady compounding by reviewing 31 resilient stocks with low risk scores that keep volatility in check while still giving you meaningful exposure to the market.
- Hunt for value by scanning 20 high quality undiscovered gems that pair robust fundamentals with relatively low investor attention.
- Strengthen your core holdings by comparing Forestar Group with a curated 8 dividend fortresses that focus on higher-yielding payouts backed by financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com