
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Lattice Semiconductor Stock Could Change Following Arm Collaboration
- Lattice Semiconductor reported a past collaboration with Arm that links Arm AGI CPU server platforms, Lattice FPGAs, and AMI firmware to provide secure control, manageability, and adaptable connectivity for AI data center infrastructure, using OCP compliant LTPI to support modular deployment.
- This tie up positions Lattice FPGAs as companion control chips inside Arm based AI servers, which can deepen platform integration and potentially increase the firm’s role in hardware rooted security and manageability for large scale AI racks.
- We will now look at how Lattice Semiconductor's investment narrative could shift as its Arm based secure AI control platform takes shape.
Scan beyond Lattice Semiconductor and size up other chip players wiring AI data centers with hardware rooted security by reviewing our hand picked 92 AI infrastructure stocks.
Lattice Semiconductor Investment Narrative Recap
Lattice Semiconductor is now asking investors to focus on a control and security story around AI infrastructure, not just low power FPGAs. The Arm collaboration supports that view in a visible way but does not erase nearer term pressure points such as supply chain costs, industry wide assembly capacity and a rich P/S multiple that leaves little room for operational missteps.
The key potential upside trigger remains execution on higher content per AI rack and deeper attach of the FPGA plus AMI firmware platform into servers and industrial systems. The main risk is still concentration in a focused product set and end markets, where any slowdown or customer pivot could affect revenue conversion and margins before new sockets ramp.
Among the recent milestones, the CyberSecurity Breakthrough Award for the MachXO5 NX TDQ FPGA family is particularly important in the context of this Arm AI server collaboration. Investors now see Lattice Semiconductor discussing secure control in data centers while also having external recognition for post quantum cryptography capabilities that support that message.
That award supports one of the central potential catalysts for the stock: rising hardware rooted security needs in AI data centers and in regulated industrial or automotive uses. The combination of Arm AGI platforms, Lattice FPGAs and AMI firmware could give the firm more ways to sell those PQC ready devices into multi socket systems, although customer adoption speed and tariffs still present obstacles to clean execution.
What The Analyst Case Implies For Lattice Semiconductor
For Lattice Semiconductor, the analyst blueprint is clear on paper. Revenue is assumed to climb at 45.0% a year over the next three years, profit margins are modeled to expand from 5.6% today to 27.1%, and consensus earnings are projected to reach US$537.9 million by 2029 from US$36.3 million today, which implies an increase of roughly 14.8x in earnings. The same framework pegs 2029 revenue at US$2.0b, with the stock trading on a P/E of 67x those forecast earnings compared with 503.8x on current numbers and above the 49.5x multiple cited for the broader US semiconductor group.
This setup effectively treats the Arm aligned AI control platform and broader FPGA attach story as strong enough to support much higher profit pools without assuming unlimited multiple expansion. Analysts are also building in share count growth of 3.83% per year over the next three years. This means any future earnings per share outcome will need to factor in that dilution as well as the higher absolute profit pool.
The spread between the most bullish forecast of US$736.7 million in 2029 earnings and the most cautious estimate of US$213.4 million should matter to you as an investor. That gap reflects very different views on how quickly Lattice Semiconductor can convert its AI control and security pitch into booked margin dollars, particularly if tariffs or assembly capacity issues constrain what ships out the door.
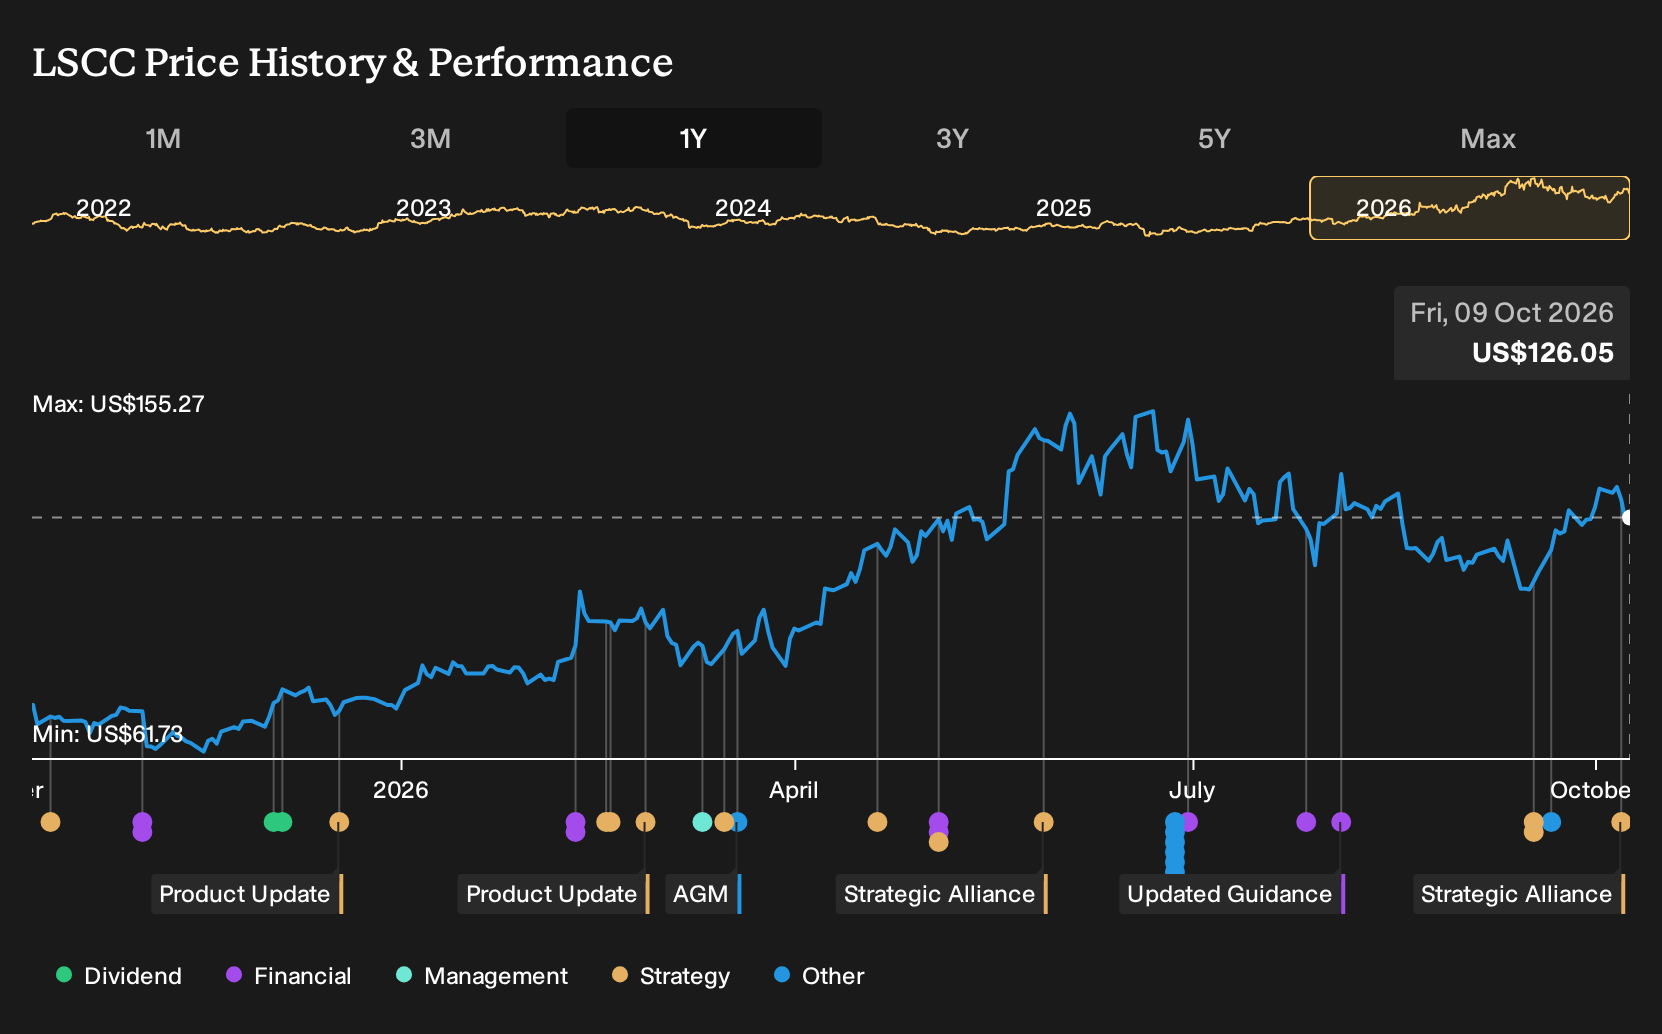
The price targets attached to this model sit in a similarly wide band. The consensus target of US$164.54, framed against a current share price of US$128.86 as of the report, comes with a range from US$125.00 up to US$180.00. Those numbers only line up if you accept the US$2.0b revenue and US$537.9 million earnings scenario for 2029, along with the 67x P/E multiple and an 11.3% discount rate used to pull that future profile back into today’s terms.
Before leaning on those projections, it helps to stress test your own view of the business against the model inputs. Ask whether a shift from 5.6% to 27.1% margins feels consistent with the supply chain costs, tariff exposure and assembly constraints already highlighted, and whether the implied earnings multiple in 2029 looks reasonable for a company still anchored in low power FPGAs and control silicon for AI racks and industrial gear.
Lattice Semiconductor's narrative projects US$2.0b revenue and US$537.9 million earnings by 2029. This assumes 45.0% yearly revenue growth and an earnings increase of about 14.8x from US$36.3 million today.
Uncover why Lattice Semiconductor's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate story puts the Arm and AMI platform upside at the center. Bullish analysts were already penciling in roughly US$2.3b of revenue and US$735.0 million in earnings by 2029, well above the baseline US$2.0b and US$537.9 million view. You can treat the new Arm collaboration as a fresh test of which camp has the sharper read on Lattice Semiconductor’s long term potential.
Explore 3 other Lattice Semiconductor fair value estimates, including one that suggests as much as 31% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lattice Semiconductor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lattice Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lattice Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lattice Semiconductor?
If you want to put Lattice Semiconductor in context, it helps to line it up against other stocks with clear financial profiles. The Simply Wall St Screener lets you do that quickly by filtering for different balance sheet strength, cash generation and income potential styles.
- If capital preservation comes first for you, start with a group of companies screened for resilience using our 31 resilient stocks with low risk scores.
- If dependable income matters more than excitement, focus on businesses that have been filtered for strong yields and stability through the 8 dividend fortresses.
- If you are hunting for underfollowed ideas with solid fundamentals, sort through a curated pool of potential outliers using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com