
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ansell And 2 Other Undervalued Stocks To Watch
Rising US Treasury yields near multi decade highs have pushed many investors toward cash and short term bonds, leaving some cash rich businesses trading quietly below estimated fair value. That gap between current prices and future cash generation can create an entry point for patient buyers. This article discusses three stocks flagged by our cash flow value screener that currently trade at a discount on a discounted cash flow basis.
The three stocks highlighted below are just a small sample. The full screen surfaces 460 more companies where current prices sit below Simply Wall St’s assessment of their cash flow value and where the underlying story may be just as compelling.
If you want to move quickly from idea to action, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, compare, and analyze the cash flow opportunities that best fit your own checklist.
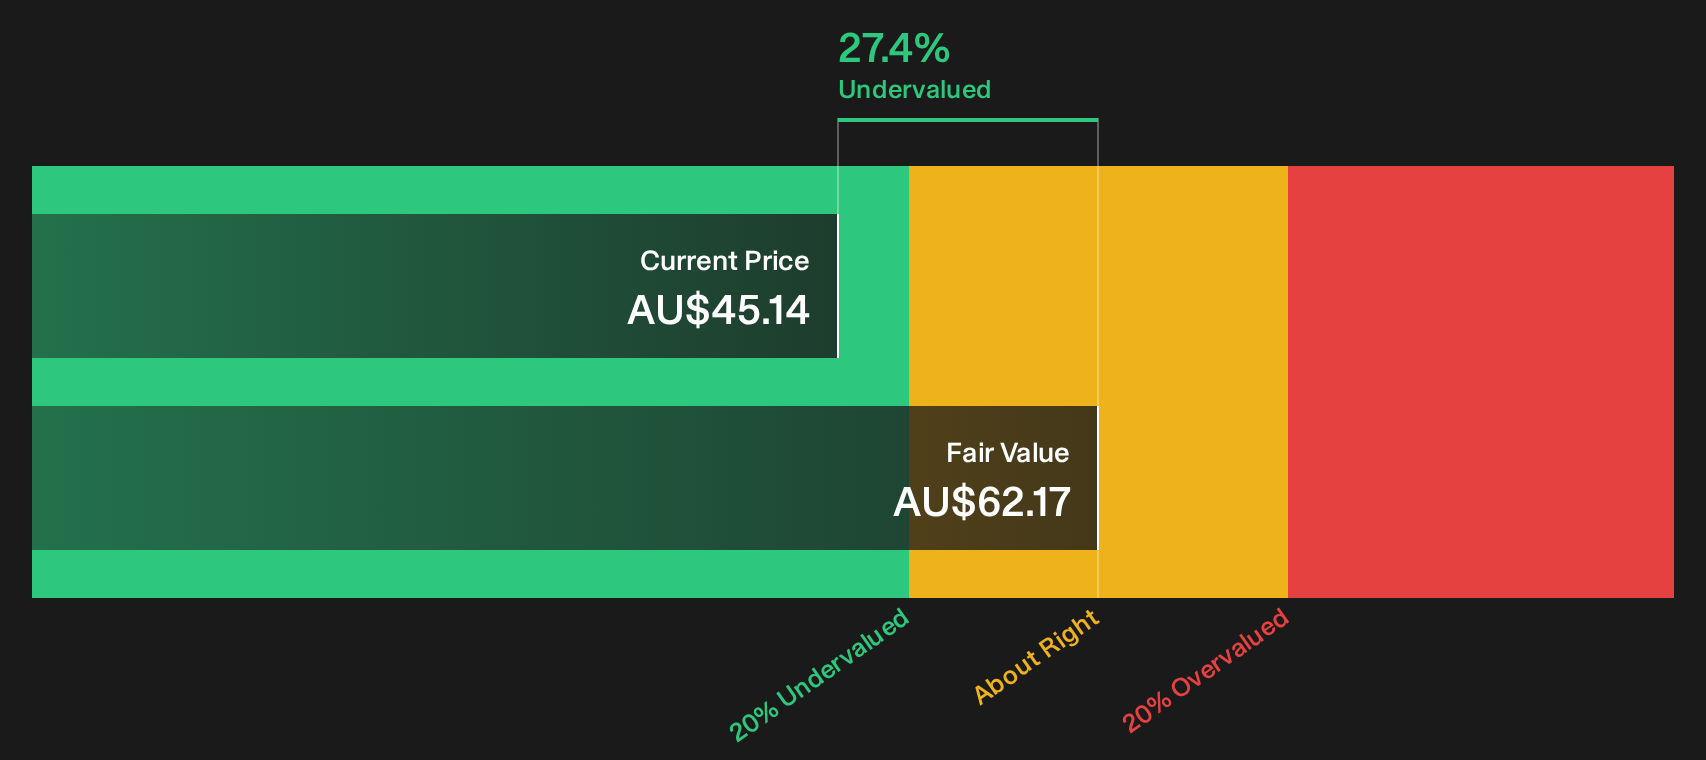
Ansell (ASX:ANN)
Overview: Ansell is a global supplier of healthcare and industrial protective gloves and garments, with recurring demand from hospitals, clinics and industrial customers.
Operations: Ansell generates about US$1.19b from Healthcare and US$947 million from Industrial, with the largest regional contribution of US$1.00b from North America.
Market Cap: A$6.26b
Ansell fits this cash flow screen because its healthcare consumables, especially surgical and examination gloves, generate recurring income from essential procedures and lab work, giving investors a clearer line of sight on future cash generation.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace-safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
What matters next is how one unseen pressure on its glove economics ultimately shapes the strength of those future cash streams.
That pressure point is the real hinge for Ansell’s story, and the full narrative for Ansell explains how glove economics, cash flows, and valuation could be decoupling.
Yadea Group Holdings (SEHK:1585)
Overview: Yadea Group Holdings develops, manufactures, and sells electric scooters, bicycles, and related batteries, generating recurring cash flows from vehicle and replacement sales.
Operations: Yadea Group Holdings generates about CN¥34.1b from electric two wheelers and accessories and CN¥7.7b from batteries and electric drives, almost entirely in China.
Market Cap: HK$27.4b
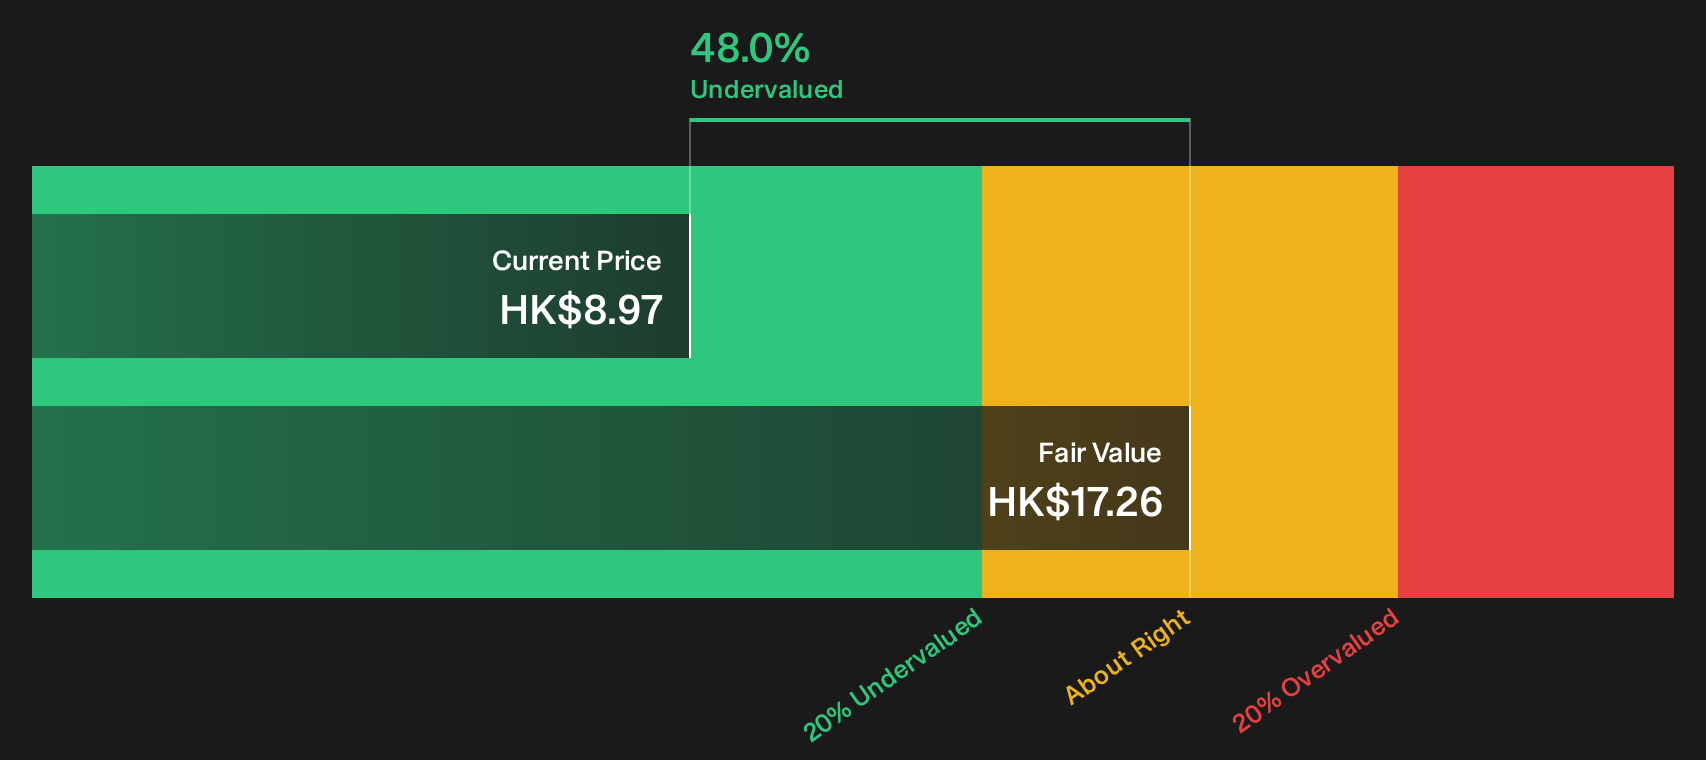
Yadea Group Holdings links tightly to this cash flow screen because electric two wheelers and batteries can bring repeat sales as riders upgrade vehicles and replace packs. The shares trade below the provider’s estimated fair value even after H1 2026 profit and revenue fell, so the key cash flow question now hinges on how pressure on demand plays out.
That demand pressure is exactly why the 4 key rewards and 1 important warning sign can help you see whether recent weakness is masking a stronger long term cash story.
Kalmar Oyj (HLSE:KALMAR)
Overview: Kalmar Oyj supplies heavy material handling equipment and high margin lifecycle services, including data and AI tools, to global ports and logistics hubs.
Operations: Kalmar Oyj earns about €1.20b from Equipment and €618.6 million from Services, with sizable revenue across Europe, the Americas, and Asia Pacific.
Market Cap: €2.38b
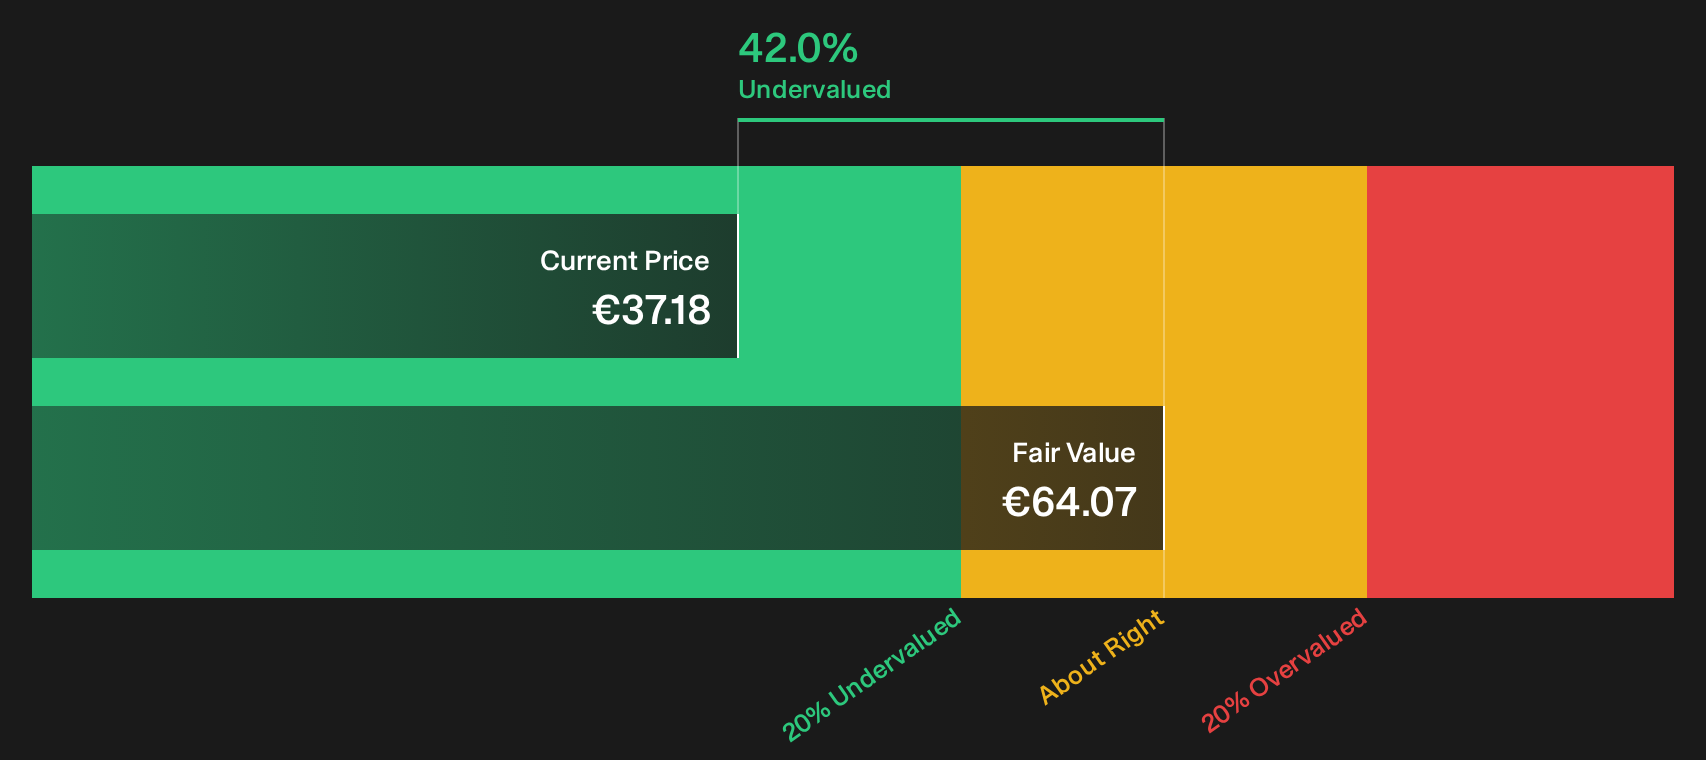
Kalmar Oyj matters for this cash flow screen because its growing service contracts and analytics offerings create repeatable income that can smooth the more cyclical equipment side of the business.
"Reliance on a high share of eco and electric equipment, with fully electric machines at 11% of equipment orders over the last 12 months, could expose Kalmar to slower than expected customer adoption if payback periods lengthen or funding tightens. This, in turn, would pressure equipment revenue growth."
What really moves the needle for Kalmar now is how one quiet shift in customer behavior shapes the strength of those future cash streams.
That shift is exactly what the full narrative for Kalmar Oyj unpacks, showing where Kalmar Oyj’s service engine could accelerate while equipment risk stays firmly in view.
Seeking Alternatives Before Momentum Flies
Fresh ideas often move first. By the time a breakout reaches headlines, early momentum can be gone and prices already elevated. Review these under the radar lists now to explore opportunities earlier in the cycle.
- Track steady cash generators and stress test your income plan with a curated 6 dividend fortresses that aims to keep payouts flowing when markets start dropping.
- Explore infrastructure related to AI demand and evolving power needs, and use the focused 43 power grid technology and infrastructure stocks to filter grid specialists before they become more widely followed.
- Identify resilient operators and review your downside risk with a hand picked 7 resilient stocks with low risk scores list while prices still reflect today’s quieter conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com