
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Silvercorp Metals (TSX:SVM) Global Expansion Push
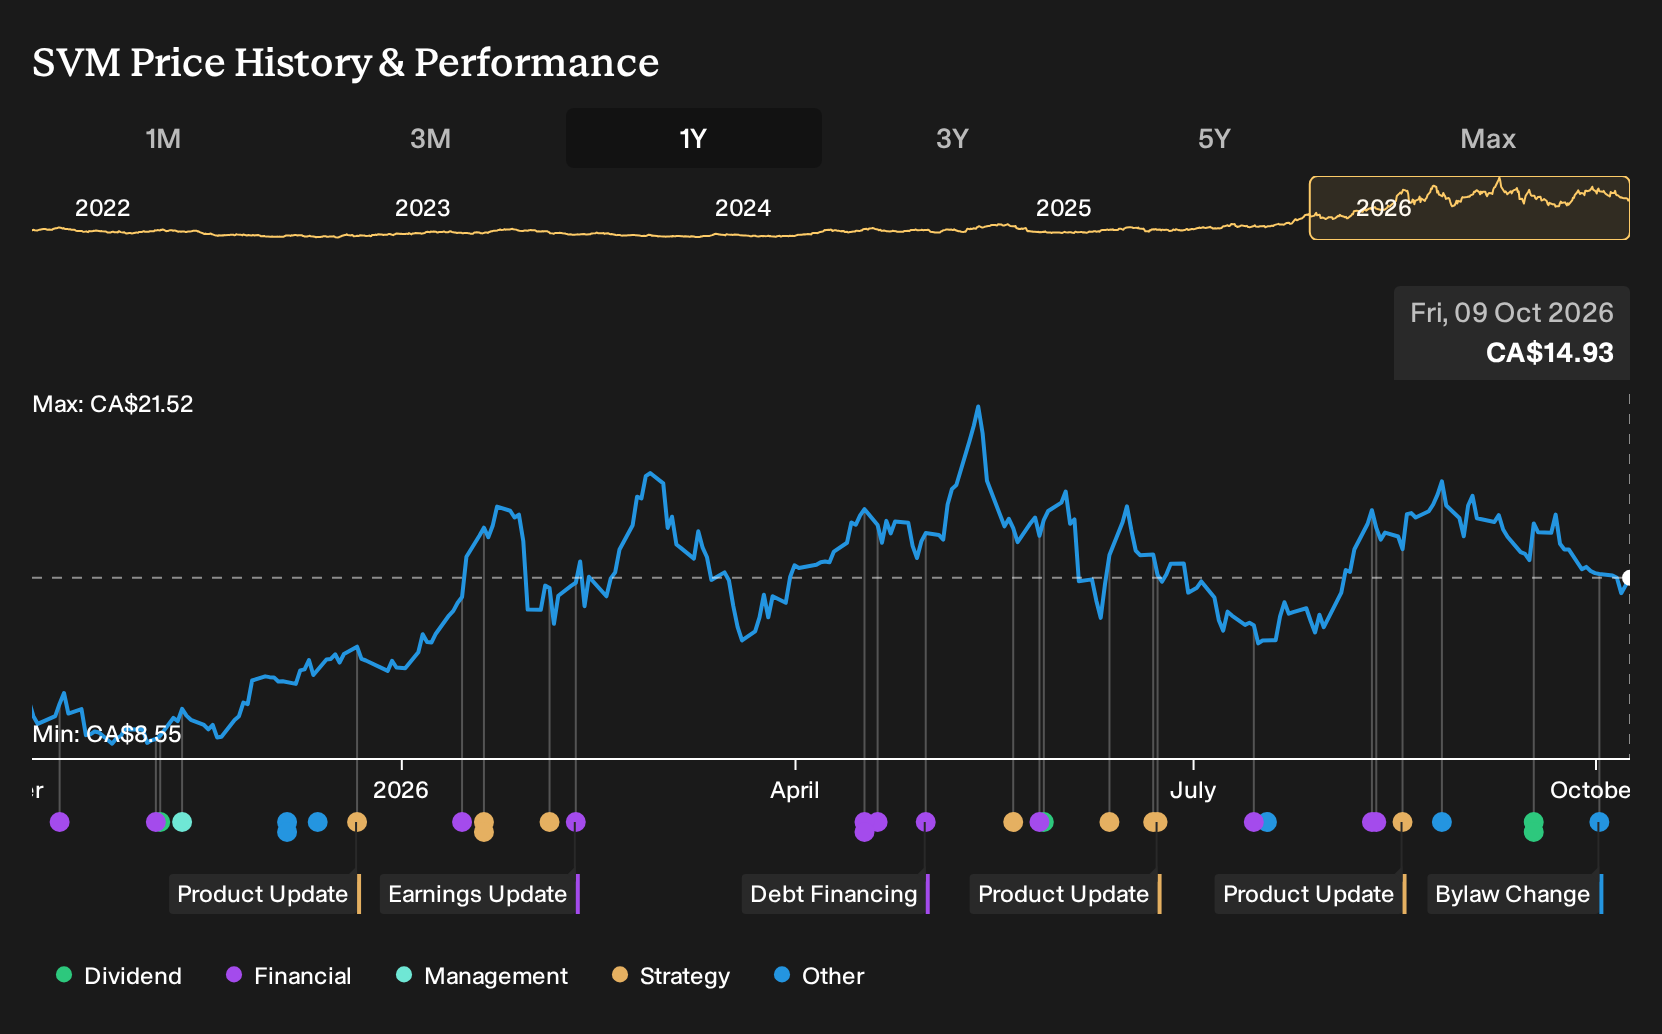
- Silvercorp Metals shareholders approved amendments to the company’s Articles at the October 2, 2026 meeting to align governance with Hong Kong Stock Exchange listing rules described in prior circulars and news releases.
- These governance changes sit alongside paused Chinese production for new safety standards and expansion projects in Ecuador and Kyrgyzstan, highlighting a push toward a more globally balanced asset base.
- Next, we will look at how Silvercorp Metals’ broader investment narrative is affected by its Hong Kong focused article amendments.
Silvercorp Metals Investment Narrative Recap
Owning Silvercorp Metals means buying into a miner that is trying to shift from heavy China exposure toward a broader mix, while still relying on Chinese assets for cash flow today. The near term swing factor remains how quickly production paused for new safety standards comes back and how cost control looks as operations restart.
The biggest operational risk stays the combination of Chinese regulatory pressure and rising all in sustaining costs, with paused production amplifying both. The Hong Kong aligned article amendments do not materially change those drivers. They mainly frame how the company accesses capital rather than altering project timelines in China, Ecuador, or Kyrgyzstan.
The recent approval of article amendments at the October 2, 2026 meeting is most clearly connected to the earlier disclosure of strong operating cash flow and aggressive top line growth. A Hong Kong rule aligned structure can matter for how Silvercorp Metals presents itself to a broader investor base while funding mine development and jurisdiction diversification.
For your catalyst map, that governance step sits in the background of more immediate triggers such as production ramp decisions at the Chinese mines and progress at El Domo in Ecuador and Kyzyltash in Kyrgyzstan. Execution risk at these projects and any fresh regulatory actions around safety or permitting still dominate the operational outlook.
Silvercorp Metals Analyst Assumptions In Context
For anyone tracking Silvercorp Metals, the analyst model pins the story firmly to a specific earnings ramp. The consensus view has revenue growing at 17.9% a year over the next three years, while profit margins are assumed to rise from 17.7% today to 28.4% by 2028. On that math, earnings would move from $54.4 million today to $143.0 million by about September 2028, which is roughly a 2.6x jump in profit over the period.
Silvercorp Metals' narrative projects $504.4 million revenue and $143.0 million earnings by 2028. This requires 17.9% yearly revenue growth and roughly a 2.6x earnings increase from $54.4 million today.
Those earnings and revenue figures also sit inside a valuation framework that assumes a lower future P/E multiple. The consensus price target builds in a shift from a 20.5x P/E today to 11.4x on those 2028 earnings. That future multiple sits below the current 18.0x P/E level quoted for the wider US metals and mining peer group. Analysts are also baking in modest equity dilution, with shares on issue expected to rise by 0.49% per year, which slightly tempers per share gains even if total profit reaches the $143.0 million mark.
On price targets, the numbers give you a clear reference point rather than a prediction to rely on. The average target of CA$8.38 sits above the quoted CA$7.05 share price as of the report, with a spread from CA$7.57 on the low end to CA$9.56 on the high end. Rather than treating that range as guidance, use it as a cross check against your own view on whether Silvercorp Metals can realistically deliver 17.9% annual revenue growth, a margin shift toward 28.4%, and a smoother production profile out of China while bringing Ecuador and Kyrgyzstan into the mix.
Discover how Silvercorp Metals' fair value indicates a 15% potential upside to its current price that may not be available for long.
Exploring Other Perspectives
Some of the most optimistic analysts frame Silvercorp Metals around aggressive M&A as the real upside lever. Before this governance news, the bullish camp was already modeling about $511.8 million of revenue and $107.4 million of earnings by 2028, on a 22.0x P/E. Those opinions may evolve as the Hong Kong aligned structure beds in, so treat this as one narrative and compare it with others before deciding what makes sense for you.
Explore 4 other Silvercorp Metals fair value estimates, including one that suggests the potential for as much as 199% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Silvercorp Metals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Silvercorp Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Silvercorp Metals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Silvercorp Metals?
Once you have a view on Silvercorp Metals, it can help to compare it with other opportunities that fit different risk levels, balance sheet strength, and income profiles. The Simply Wall St Screener lets you quickly filter for stocks that match the kind of portfolio you want to build.
- For investors hunting for smaller companies with room to grow, check out a focused group of 19 elite penny stocks with strong financials that already show stronger financial traits than many peers.
- If resilience matters most to you, start with a curated 7 resilient stocks with low risk scores that filters for businesses with lower overall risk scores and steadier fundamentals.
- For those who care about financial strength first, work through a list of solid balance sheet and fundamentals (7 results) that screens for cleaner balance sheets and sturdier core metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com