
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vulcan Materials (VMC) Could Be 24% Below Fair Value After Dividend Reaffirmation
Vulcan Materials (VMC) reaffirmed its cash return policy and declared a quarterly dividend of $0.52 per share, payable on November 24, 2026, to shareholders of record on November 9.
At a share price of US$244.58, Vulcan Materials has seen the share price fall 17.2% over the past 90 days and the 1-year total shareholder return decline 18.3%. However, the 5-year total shareholder return of 43.9% points to stronger longer term momentum built before the recent pullback.
Scan Vulcan Materials' latest pullback and dividend move against a curated 31 resilient stocks with low risk scores that prioritizes resilient balance sheets over headline volatility.After that 17.2% pullback, Vulcan Materials now trades well below the average analyst target yet sits only slightly under some intrinsic value estimates. Is this a discount, or simply the new fair value range setting in?
Most Popular Narrative: 24% Undervalued
Vulcan Materials is priced at $244.58 while the most followed narrative anchors fair value at about $321.78, so the recent pullback is being framed more as a valuation gap rather than a permanent reset.
A strong balance sheet, with net debt to adjusted EBITDA at 1.7x, operating cash flow of US$1.8b over twelve months, and significant returns of cash to shareholders, gives Vulcan Materials capacity to fund capital expenditure and additional M&A. This can support future revenue growth and earnings while reinforcing confidence in its capital allocation.
See why 13 investors see Vulcan Materials as 24% undervalued.
Result: Fair Value of $321.78 (UNDERVALUED)
Still, the Vulcan Materials story can be knocked off course if diesel costs stay elevated, or if softer government and housing demand drags on aggregates volumes.
Find out about the key risks to this Vulcan Materials narrative.
Another View On Vulcan Materials' Valuation
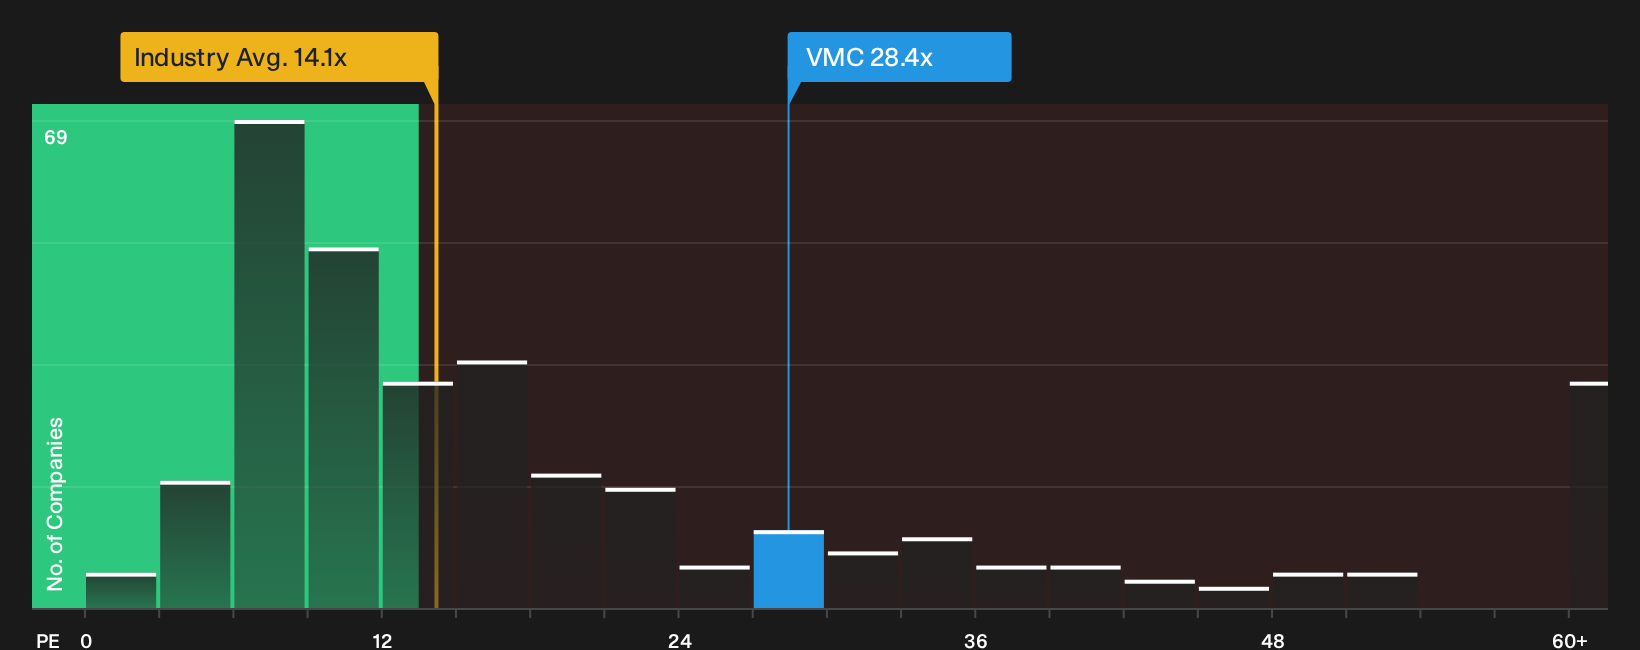
The popular story paints Vulcan Materials as 24% undervalued, yet the P/E of 28.4x tells a tougher story. It is richer than both peers at 20.9x and the global Basic Materials group at 13.9x, and also above a 20.4x fair ratio. Is this a genuine bargain or just paying up for quality?
To see how that premium stacks up in hard numbers, and what it could mean for valuation risk if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether Vulcan Materials represents mispriced quality or simply a fully valued compounder after a pullback. Do not wait for consensus. Put the pieces together yourself by weighing the 3 key rewards and 2 important warning signs.
Looking for more Vulcan Materials sized opportunities?
If Vulcan Materials has your attention right now, do not stop there. Broaden your watchlist with fresh ideas that could balance risk and reward across different angles.
- Target resilient balance sheets that can handle shocks by scanning companies in the list of solid balance sheet and fundamentals (25 results).
- Spot quality businesses priced below their estimated worth by running a focused search through the 28 high quality undervalued stocks.
- Zero in on quieter potential standouts before they hit the spotlight by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com