
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Watts Water Technologies (WTS) Expands Its Growth Story, Is The Stock Undervalued?
Watts Water Technologies (WTS) is back on investor radars after announcing the planned 2027 retirement of long-serving General Counsel and Chief Compliance and Sustainability Officer Kenneth R. Lepage.
Recent trading has been choppy for Watts Water Technologies, with the share price slipping 2.9% over the past week and 1.0% over the past month. Even so, the year-to-date share price return sits at 26.6%, and the 5-year total shareholder return reaches 107.1%, which points to long-run momentum that shorter-term volatility has not erased.
Scan beyond Watts Water Technologies and compare it with a hand picked 43 power grid technology and infrastructure stocks that is riding the build out of modern energy and water infrastructure.
After a choppy few weeks, the real tension around Watts Water Technologies is not the recent pullback. Instead, it is where fair value sits between the current US$352.72 price and a spread of intrinsic and analyst estimates.
Most Popular Narrative: 13% Undervalued
On the most followed view, Watts Water Technologies screens as undervalued, with a fair value of $404 against the latest $352.72 close. That gap rests on a detailed earnings path, margin story, and a specific discount rate of 8.41%.
The accelerating rollout and success of Nexa, Watts' intelligent water management platform, positions the company to capture the growing demand for advanced, data-driven water conservation, efficiency, and regulatory compliance solutions. This is expected to drive higher-margin, recurring revenue and support long-term earnings and margin expansion.
Ongoing global urbanization and the need for water infrastructure upgrades, especially in fast-growing segments like data centers and across verticals such as hospitality and multifamily, are expected to sustain revenue growth by increasing the addressable market and demand for Watts' portfolio, including through new acquisitions.
See why 7 investors see Watts Water Technologies as 13% undervalued.
Result: Fair Value of $404 (UNDERVALUED)
Still, the bullish case for Watts Water Technologies collides with some clear pressure points, including softer volumes in Europe and ongoing tariff uncertainty that could squeeze profitability.
Find out about the key risks to this Watts Water Technologies narrative.
Another View: Watts Water Technologies Looks Rich On P/E
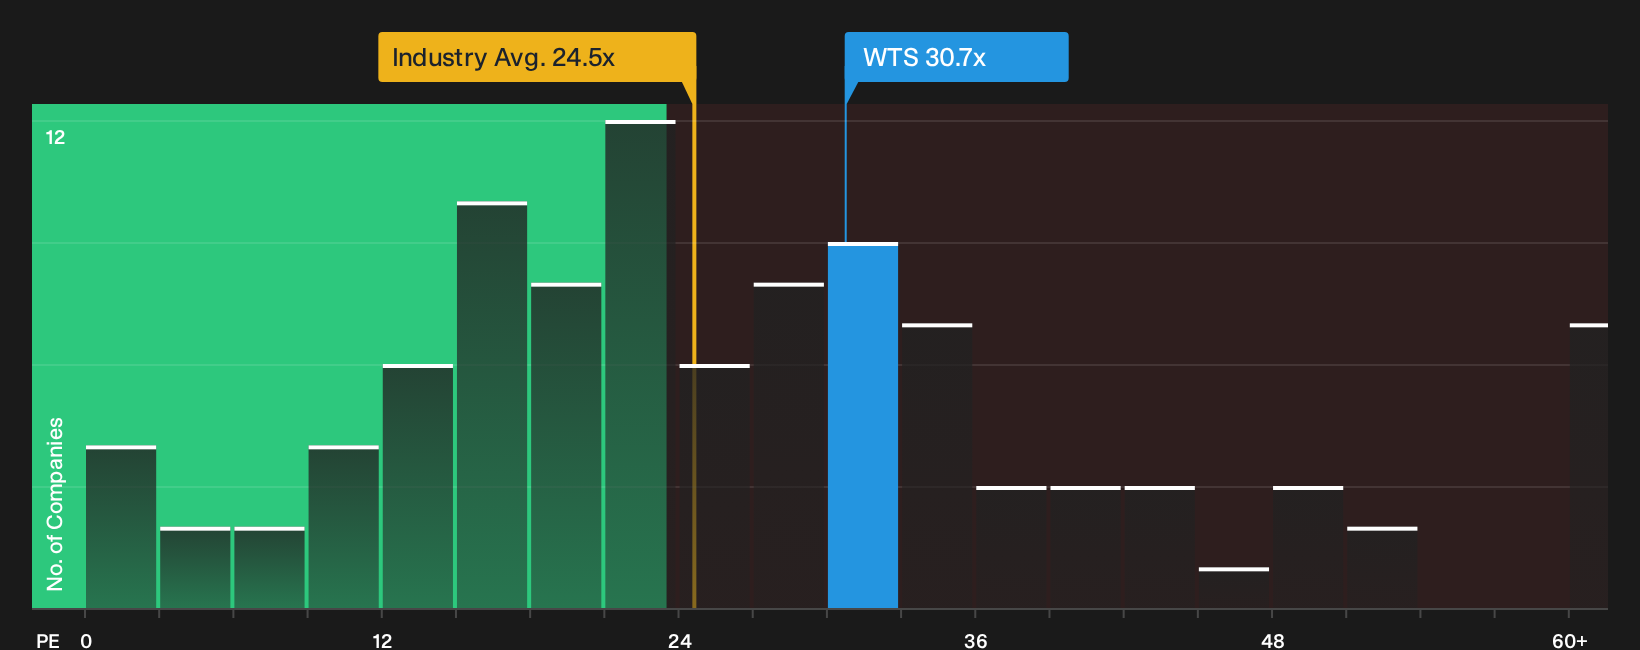
On a simple earnings multiple, Watts Water Technologies screens as expensive. The stock trades on a P/E of 30.7x, compared with 24x for the wider US Machinery group and a 21.3x fair ratio the market could move toward over time.
That gap means investors today are paying a premium valuation for each dollar of earnings, leaving less room for error if growth or margins fall short of expectations. It raises a straightforward question for you as a shareholder or prospect: is that premium a comfort or a risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Watts Water Technologies valuation and risk can be hard to reconcile, so act promptly, review the full context, and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Watts Water Technologies?
If Watts Water Technologies has sharpened your thinking, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh, data driven ideas that match your style.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can handle tough cycles without stretching their finances.
- Hunt for potential bargains by reviewing a 28 high quality undervalued stocks that screens for quality businesses trading below their assessed worth.
- Prioritize stability by focusing on a 31 resilient stocks with low risk scores that highlights companies with fewer red flags and stronger overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com