
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FDA Warning Letter Could Be A Game Changer For Neogen Stock (NEOG)
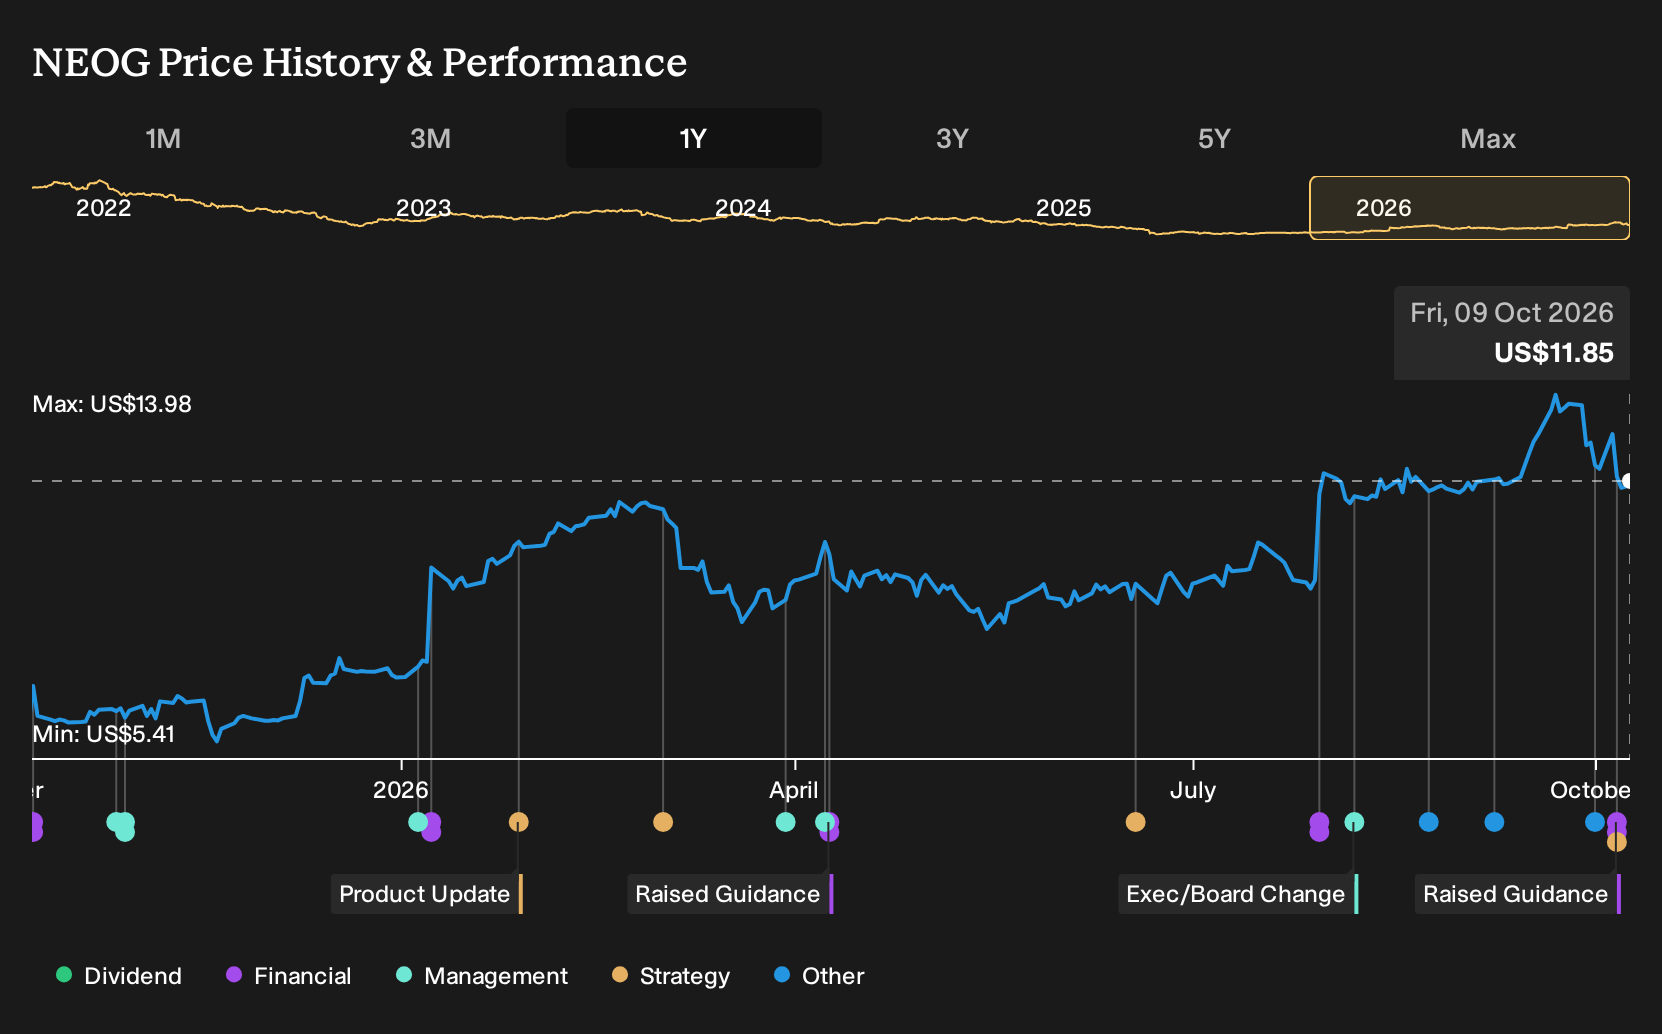
- Neogen reported first quarter revenue of US$222.8 million and a net loss of US$11.9 million, raised full year 2027 revenue guidance, and separately received an FDA warning letter over contaminated HYCOAT(R) veterinary product lots that were already recalled after serious horse fatalities.
- The FDA letter highlights extensive manufacturing and labeling violations around HYCOAT(R), pointing to potential remediation spend, quality system upgrades, and reputational pressure that directly intersect with Neogen's multi year plan to improve margins and streamline its animal safety portfolio.
- This article examines how Neogen's investment narrative is tested by the FDA warning letter on HYCOAT and the related recall fallout.
Scan how Neogen’s mix of higher revenue guidance, earnings pressure and regulatory scrutiny compares with hand-picked peers by reviewing the 31 resilient stocks with low risk scores that currently look more resilient on risk.
Neogen Investment Narrative Recap
To own Neogen right now, you need to believe the food safety engine and portfolio clean up can outweigh near term noise in animal health and integration work. The raised 2027 revenue outlook points to management leaning into that long term plan, even as the group sits in a loss making position this quarter.
The key near term catalyst is execution on cost fixes and quality systems while keeping food safety demand on track. The HYCOAT warning letter and related remediation risk now look like the biggest operational overhang, because they can pull cash, focus and regulatory attention away from margin repair.
The most relevant update to this HYCOAT episode is the first quarter print with US$222.8 million of revenue, a net loss of US$11.9 million and a higher revenue range for fiscal 2027. That mix of top line ambition and bottom line strain frames how much room Neogen has to absorb extra compliance and quality expenses.
The equity investment and collaboration with Hinalea Imaging also matters for catalysts. It ties directly to Neogen’s push into faster, more automated food safety workflows, which is where regulators and customers are already spending more. Your call is whether management can keep funding these projects while dealing with the HYCOAT clean up and still move margins in the right direction.
Neogen's current earnings are a loss of US$7.9 million, while consensus forecasts point to earnings of US$112.7 million on revenue of US$896.0 million by 2029. This implies a US$120.6 million improvement in earnings from today if analysts are correct that revenue remains fairly flat over the next three years before reaching that 2029 level.
Uncover how Neogen's fair value indicates an 18% potential upside to its current price that could narrow quickly if sentiment improves.
Exploring Other Perspectives
You might see the FDA warning letter and immediately focus on regulatory risk. The lowest analysts already leaned hard into that theme even before this news, with prior forecasts closer to US$861.3 million of revenue and US$108.3 million of earnings by 2029. Their view is more cautious, but yours does not have to be. Use this event as a reason to compare several narratives, not just one.
Explore another Neogen fair value estimate, including one that suggests as much as 98% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Neogen research is our analysis highlighting 1 important warning sign that could impact your investment decision.
- See our latest analysis for Neogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Neogen's overall financial health at a glance.
Looking for more Neogen sized investment ideas?
If the Neogen story has sharpened your thinking and you want to cast a wider net, the Simply Wall St Screener can help you quickly filter for other listed businesses that better fit your risk, income, or value preferences.
- If capital preservation matters most, compare Neogen with other companies that currently screen as relatively steady on risk using the 31 resilient stocks with low risk scores.
- If dependable income is a priority, scan for companies that combine higher yields with fundamental support through the 8 dividend fortresses.
- If you are hunting for overlooked opportunities, start with the 20 high quality undiscovered gems that meet strict quality and financial strength criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com