
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Cash Dividend Declaration Just Shift Graham Holdings' (GHC) Investment Narrative?
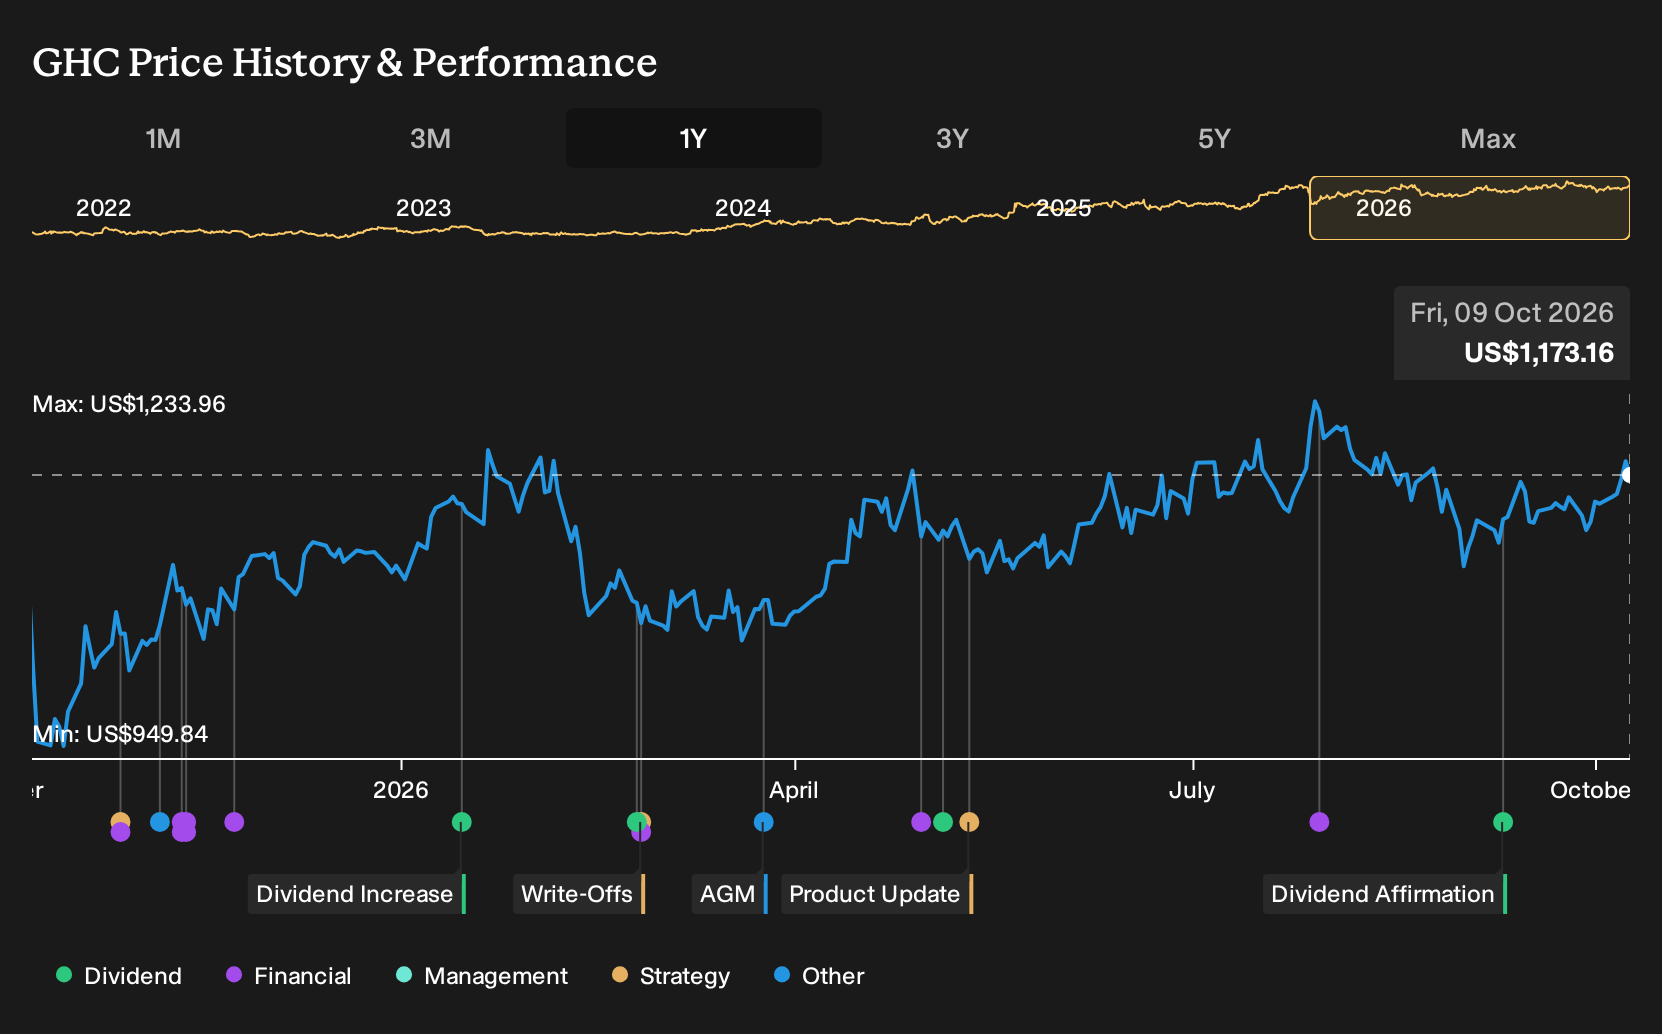
- Graham Holdings Company recently declared a cash dividend of $1.88 per share, with an ex-dividend date set for October 15, 2026, reflecting ongoing capital returns from its diversified activities in education services, healthcare, media, and industrial supply.
- The dividend decision highlights how Graham Holdings is using its varied operating base, from classrooms to clinics to industrial supply chains, to support shareholder payouts grounded in underlying cash generation.
- Next, the focus shifts to how this $1.88 cash dividend fits into Graham Holdings' broader investment narrative and risk profile.
What Is Graham Holdings' Investment Narrative?
To own Graham Holdings, you really need to believe in the value of a collection of steady, cash generating businesses rather than a single growth story. Education services, healthcare, television, industrial supply and automotive all pull in different directions, so execution depends on disciplined capital allocation and operational focus in each unit. The recently declared US$1.88 dividend fits that mindset. It signals that management still feels comfortable returning cash after a year where earnings included large one off items and current net margins of 10.7% sit below last year’s 14%.
In the near term, the dividend itself is unlikely to reshape the main catalysts. Attention stays on how Graham Holdings handles capital intensive areas like manufacturing and automotive, keeps demand healthy in education and healthcare, and manages higher risk funding that relies on external borrowing. With the stock trading on a 9.2x P/E and recent returns ahead of both the US market and Consumer Services sector, the focus remains on whether that diversified engine can support both reinvestment and payouts without eroding return on equity, which sits at 11.4%.
Even so, one awkward tension in the Graham Holdings story keeps coming back to ...
There's only one way to know the right time to buy, sell or hold Graham Holdings. Head to Simply Wall St's company report for the latest analysis of Graham Holdings's Fair Value.
Exploring Other Perspectives
Across three fair value estimates from the Simply Wall St Community, numbers stretch from just US$990 to more than US$2,324,780. This shows how wildly opinions on Graham Holdings can differ. These figures were set before the US$1.88 dividend announcement, so treat them as a starting point and explore multiple viewpoints.
Explore 2 other Graham Holdings fair value estimates, including one that suggests as much as 198064% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graham Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Graham Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graham Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Graham Holdings?
Once you have a view on Graham Holdings, it helps to widen the lens and compare it with other opportunities that match your income or quality goals. The Simply Wall St Screener can surface a wide mix of businesses so you can line up their dividends, balance sheets, and fundamentals side by side.
- For investors who want steadier balance sheets as a base for long term compounding, start with our list of solid balance sheet and fundamentals (25 results) and see which businesses pair financial resilience with fundamental strength.
- If your priority is a smoother ride with fewer shocks, focus on resilience first and use the 31 resilient stocks with low risk scores to spot companies that score well on risk while still offering meaningful exposure.
- When you are hunting for under followed opportunities with strong underlying metrics, the 20 high quality undiscovered gems can point you toward businesses that combine quality with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com