
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To OSL Group (SEHK:863) Stablecoin Fund Mandate
- OSL Group disclosed that it was engaged to tokenize, custody and distribute 2WA's USDGO Plus SP, a market neutral digital asset fund built on the USDGO stablecoin and offered to eligible professional investors in Hong Kong.
- The mandate concentrates several fee pools for OSL Group in one product, including tokenization services, custody of both USDGO and fund units, and distribution through its licensed Hong Kong platform.
- We will examine how OSL Group's investment narrative is affected by this USDGO Plus SP tokenization mandate across its regulated digital asset rails.
Scan regulated digital asset plays like OSL Group by reviewing hand-picked opportunities that are screened for stronger balance sheets and fundamentals in our list of solid balance sheet and fundamentals (204 results), which is tailored for this corner of the market.
OSL Group Investment Narrative Recap
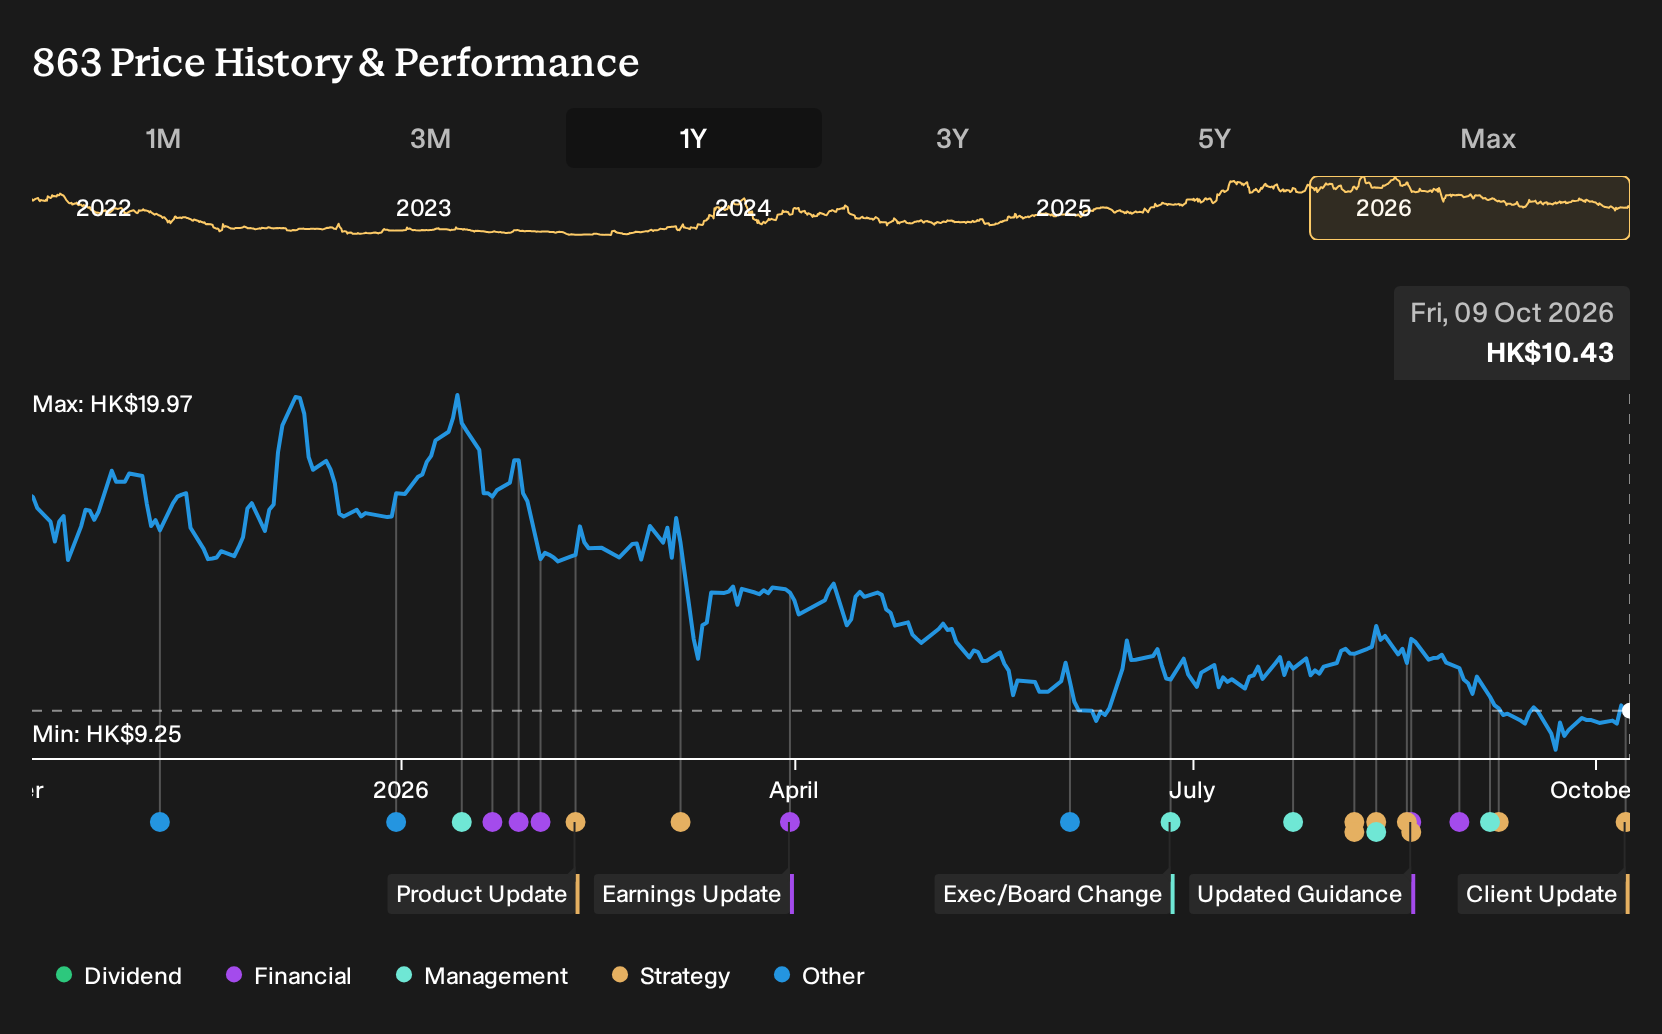
To own OSL Group, you need to believe its stablecoin rails, tokenization stack and AI agent ready payments can scale fast enough to support a business that is still loss making and investing heavily. The USDGO Plus SP mandate fits that belief by putting more activity on its licensed infrastructure, but it does not change the fact that analysts still see revenue declining and no near term profitability.
The near term catalyst remains whether management can convert its large regulatory footprint and vertical stack into steady, fee based volumes while holding operating losses in check. The biggest risk is still execution on that plan, especially with less than one year of cash runway flagged and a heavy spend across expansion, technology and potential M&A.
The most relevant recent development is OSL Group’s role with Anchorage Digital Bank’s USDGO stablecoin, where OSL acts as brand operator and distributor. The USDGO Plus SP engagement leans directly on that relationship, since the fund is fully built on USDGO and custodied on OSL’s rails. That keeps the operational story tightly linked to stablecoin activity rather than pure trading volume.
For catalysts, that pairing means any pick up in USDGO based payments, treasury flows or tokenized products can feed several parts of OSL’s model at once, from issuance to custody to subscription and redemption fees. For risks, you are still exposed to slower stablecoin adoption, regulatory changes across those licensed markets and the possibility that higher costs and funding needs swamp the incremental revenue from mandates like this.
OSL Group’s story ties analyst assumptions to a revenue forecast of HK$24.9 million and projected earnings of HK$9.1 million by 2029. This outlook is built on an expected yearly revenue decline of 89.7% and an earnings swing of roughly HK$1.2 billion, from today’s loss of HK$1.2 billion to the forecast profit.
Discover how OSL Group's fair value indicates a 53% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view on OSL Group focuses on margin risk. Bearish analysts worry that higher staffing, technology and legal costs could eat most of the USDGO Plus SP style fee pool. They were pencilling in about HK$80.0 million of revenue and HK$79.7 million of earnings by 2029, yet still used a high 234.6x P/E. Those estimates and the USDGO mandate were set on different days, so opinions may shift as you weigh both stories.
Explore another OSL Group fair value estimate, including one that suggests it could be worth just HK$15.98!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your OSL Group research is our analysis highlighting 2 important warning signs that could impact your investment decision.
- See our latest analysis for OSL Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSL Group's overall financial health at a glance.
Looking for more investment ideas beyond OSL Group?
Once you have a view on OSL Group, it can help to compare it with other listed businesses that share some of the qualities you care about, whether that is value, resilience or income.
- If you want potential value opportunities with stronger fundamentals, review companies highlighted in our 174 high quality undervalued stocks and see which ones match your criteria.
- If capital preservation and steadier profiles matter more to you, scan through the 222 resilient stocks with low risk scores to find businesses filtered for lower risk scores.
- If you are hunting for income ideas, use the 223 dividend fortresses to spot high yielding dividend payers that may fit a cash flow focused portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com