
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will AI Cloud Backlog Change Nebius Group (NBIS) Stock Narrative
- Nebius Group has drawn attention as an AI cloud infrastructure provider after reporting very large revenue growth in 2025, positive net income, and continued expansion of data center capacity supported by a sizable contracted backlog.
- The business is leaning into capital intensive GPU buildouts to serve AI demand, which supports scale but also raises questions around long term margins, debt levels, and how much pricing power Nebius can sustain in a crowded market.
- We will now look at how Nebius Group's surging AI infrastructure revenue and backlog reshape the investment narrative that investors focus on.
Scan how Nebius Group fits into the AI infrastructure story by comparing it with a curated set of peers in our 92 AI infrastructure stocks.
Nebius Group Investment Narrative Recap
To own Nebius Group, you need to be comfortable with a capital hungry AI infrastructure story in which GPU buildouts, new regions, and an AI focused cloud platform are the core of the thesis. The short term swing factor is execution on that contracted backlog and keeping utilization high as new data centers open, while managing operating costs so margins do not come under further pressure.
The biggest near term risk is that heavy reliance on external borrowing, thin net profit margins, and a very high P/S multiple collide with any slowdown in AI workloads or pricing pressure from larger hyperscalers. Recent sector volatility tied to interest rate moves has amplified that risk but does not alter Nebius Group's operating priorities.
The most relevant recent update is Nebius Group's reported 2025 revenue of US$1.36b with US$1.31b from Nebius AI Cloud, alongside positive net income and strong contracted backlog. That combination shows the AI cloud unit already drives almost all of the business and that current demand is supporting both top line scale and profitability, even as margins remain modest.
For catalysts, the focus now is on whether that backlog converts into cash fast enough to justify ongoing GPU and data center commitments funded through higher risk borrowing. Execution on new data center launches in markets such as the U.S., U.K., Israel, and Finland will shape how efficiently Nebius Group can absorb new capacity, defend pricing, and potentially lift returns on equity from current low levels.
Nebius Group's current earnings of US$42.4 million sit alongside analyst expectations for revenue to grow by 179.9% per year and reach US$29.7b with earnings of US$2.1b by 2029, which implies an earnings increase of almost 50 times from today.
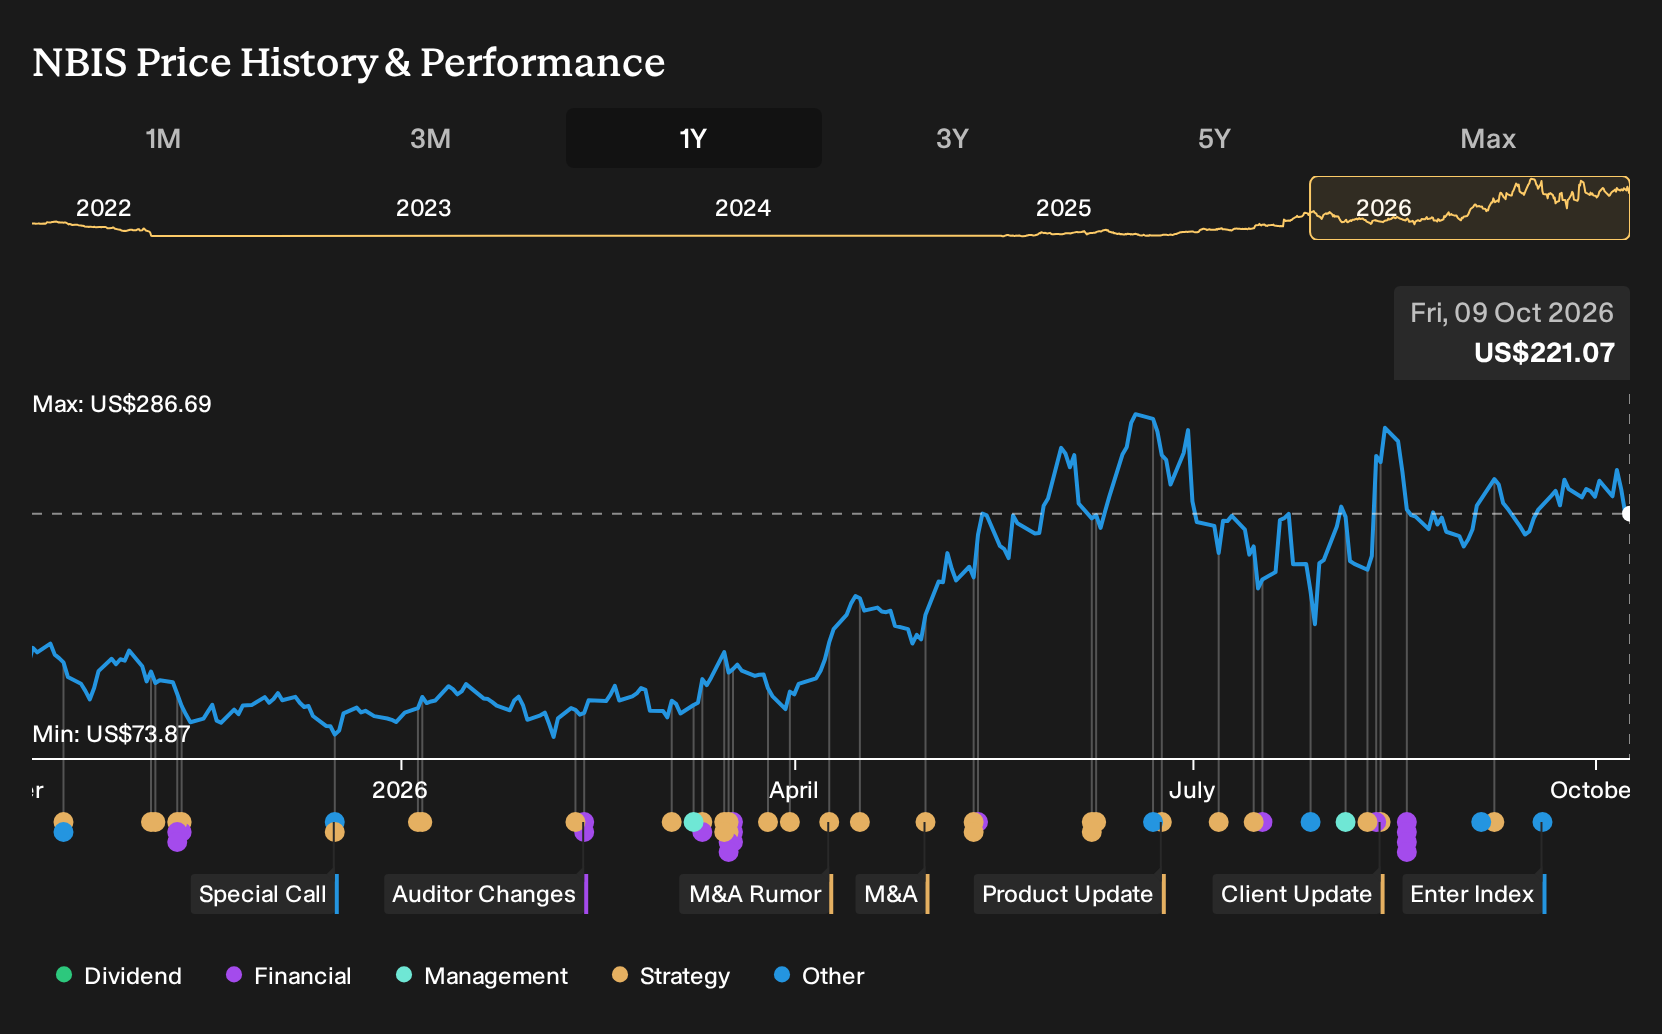
Uncover why Nebius Group's fair value indicates a 28% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternative angle on Nebius Group puts far more weight on capacity expansion as a long term catalyst. The most optimistic analysts were already modeling revenue of US$48.5b and earnings of US$1.1b by 2029. These views were set before the latest AI enthusiasm and could shift again as new information lands.
Explore 12 other Nebius Group fair value estimates, including one that suggests as much as 88% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nebius Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking For More Ideas Beyond Nebius Group?
Once you have a view on Nebius Group, it can help to compare that thesis with a wider set of companies that fit different risk and quality profiles using the Simply Wall St Screener.
- If capital preservation is high on your list, consider starting with a basket of resilient businesses through our 31 resilient stocks with low risk scores.
- If you prefer companies with strong finances over story stocks, broaden your watchlist with a list of solid balance sheet and fundamentals (25 results).
- If you want a shot at earlier stage opportunities backed by fundamentals, scan through a 20 high quality undiscovered gems that could deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com