
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Hornbach (XTRA:HBH) Steady Outlook Confirmed
- HORNBACH Holding KGaA reported past second quarter sales of €1,813.7 million and net income of €74.9 million, with six-month figures of €3,816.2 million in sales and €174.7 million in net profit. The company also confirmed guidance that targets net sales at or slightly above the prior year's €6.4b.
- The combination of higher earnings per share over both the quarter and first half and reaffirmed revenue guidance reflects management's stated confidence in HORNBACH Holding KGaA's current business trajectory and cost discipline despite external pressures on consumer demand.
- We will now assess how HORNBACH Holding KGaA's confirmed sales guidance influences its existing investment narrative, which is built around controlled European expansion.
HORNBACH Holding KGaA Investment Narrative Recap
To stay invested in HORNBACH Holding KGaA, you need to be comfortable with a slow growth, execution heavy story. The core belief is that controlled European expansion, omnichannel DIY retail and process efficiency can support earnings, even when consumer demand looks soft. The latest half year and second quarter figures, together with reiterated sales guidance, point to a steady rather than explosive operating profile.
The key short term catalyst is how effectively HORNBACH converts new space, online traffic and cost measures into profit, while wage and pre opening expenses weigh on margins. The biggest near term risk remains subdued DIY demand in Germany combined with ongoing inflation in operating costs. The new guidance mainly confirms that this trade off is still in place and does not materially shift that balance.
The confirmed outlook for fiscal 2026/27 is the announcement that matters most here. Management expects net sales to be at or slightly above the prior year's €6.4b. In practical terms, that sets a relatively tight range for top line expectations and frames the next few quarters as a test of operating discipline rather than a revenue driven story.
For you as a shareholder, that confirmed guidance directly connects to the main catalysts and risks already in play. Store openings, omnichannel investments and efficiency projects now have to work against what the company itself frames as essentially flat market conditions. Any sign of pressure on margins from wage agreements or pre opening costs will likely draw more attention than small variations inside that sales range.
HORNBACH Holding KGaA's narrative projects €7.0b revenue and €159.2 million earnings by 2029. This implies 2.2% yearly revenue growth and an earnings increase of about €26.8 million from €132.4 million today.
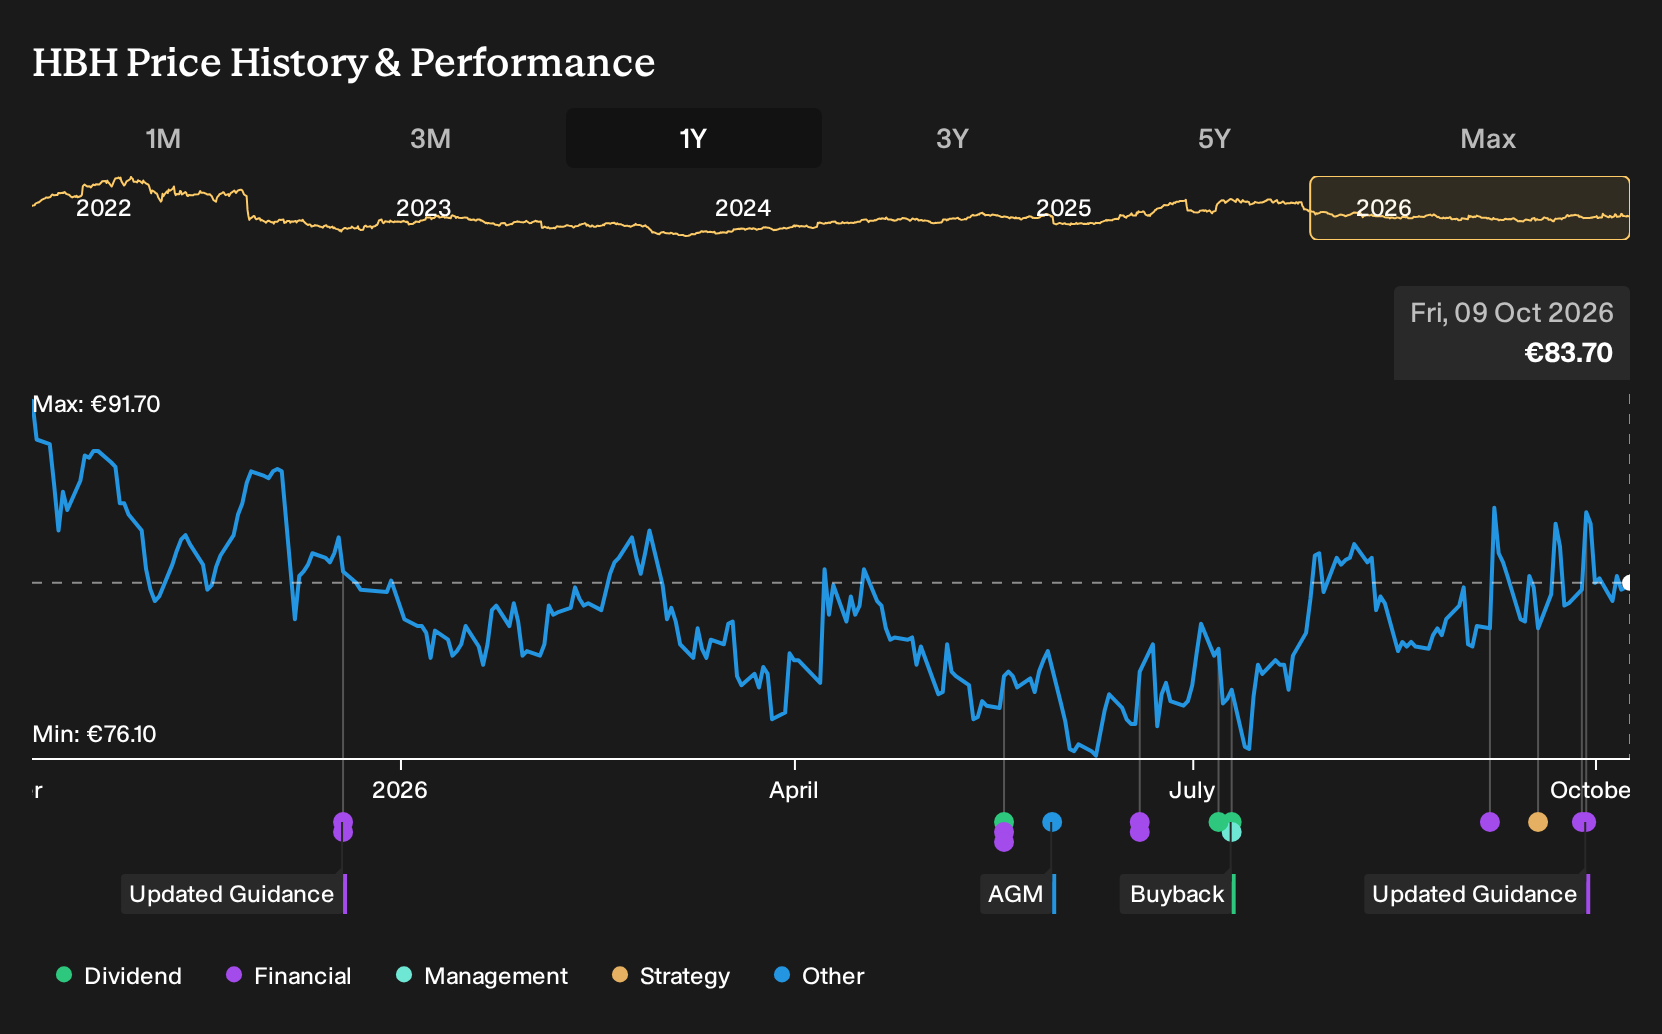
Uncover why HORNBACH Holding KGaA's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate narrative for HORNBACH Holding KGaA focuses on heavy store expansion as the main risk. The most cautious analysts were assuming revenue of about €6.6b and earnings of €143.5 million by 2029, with only a small margin lift to 2.2%. That is a much more muted path than consensus, and it might shift once this new guidance is fully reflected. Use that gap in expectations as a reminder that opinions differ widely. It is worth exploring both the cautious and the more upbeat scenarios before you decide how this stock fits your portfolio.
Explore 3 other HORNBACH Holding KGaA fair value estimates, including one that suggests it could be worth just €80.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your HORNBACH Holding KGaA research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for HORNBACH Holding KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HORNBACH Holding KGaA's overall financial health at a glance.
Looking for more investment ideas beyond HORNBACH Holding KGaA?
Once you have a view on HORNBACH Holding KGaA, it can help to compare it with a few very different types of opportunities so you keep a balanced watchlist rather than anchoring on a single story.
- If you want potential mispricing paired with healthier fundamentals, scan through a hand picked group of 175 high quality undervalued stocks and see which ones match your risk tolerance.
- For income focused investing where stability and yield work together, use the curated set of 223 dividend fortresses as a shortlist to investigate payout strength and consistency.
- When capital preservation matters most, start with a 222 resilient stocks with low risk scores and compare their balance sheets, earnings profiles and volatility with what you see at HORNBACH.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com