
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shopify (SHOP) Stock May Trade At A Premium Following Canvas Launch
Shopify has surged back into focus after a strong multi year run. With the stock now around US$170, the real question is whether that price still lines up with the earnings the business is generating.
- Over the past 3 years, Shopify has delivered a very large 231.4% share price gain. That puts a lot of weight on whether its current profit stream can support that kind of re rating.
- New products like the AI powered Canvas design tool can shape how investors think about future earnings by influencing how much revenue the platform may capture from smaller merchants and how efficiently it can be earned.
- There is a second opinion on Shopify worth weighing. See what analysts think Shopify's shares could be worth.
For investors, the debate is whether Shopify's current earnings are strong and durable enough to justify where the stock trades today.
If you are weighing whether Shopify's US$170 share price is justified by its earnings, it can help to ask the same question across 28 high quality undervalued stocks.
Does Shopify Look Pricey on Earnings?
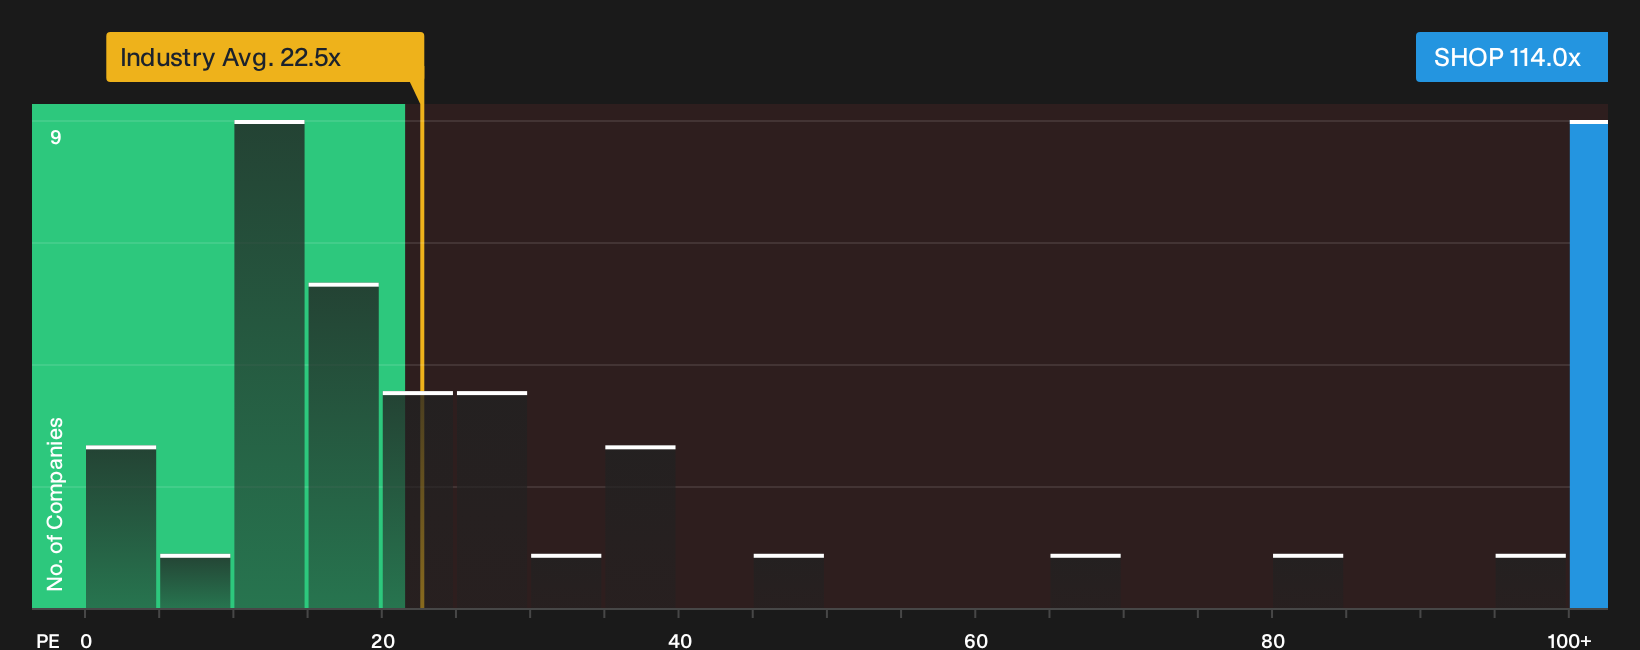
P/E is usually the cleanest shorthand for a business like Shopify, where earnings and free cash flow are both closely watched. At around 114.0x, Shopify’s P/E is far above the wider IT industry average of roughly 22.5x and also well ahead of the peer group on about 68.9x. That gap means buyers today are paying a steep premium per dollar of reported earnings compared with many other software and commerce platforms.
On Simply Wall St’s fair multiple framework, which tries to align the P/E with Shopify’s growth profile, margins, size and risk, the current 114.0x sits above the level implied by those fundamentals and screens as overvalued. Despite excitement around new tools like the Canvas AI design platform and broader enthusiasm for e commerce plays, the present P/E assumes a lot from future profit delivery relative to both sector norms and that tailored yardstick. Explore the numbers behind Shopify's P/E valuation.
The Shopify Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Shopify's valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to play out for the current share price to look either stretched or conservative. Each scenario sets out its own fair value assumptions in plain terms, so you can track how those expectations stack up against Shopify's reported results over time on the Community page.
Community views on Shopify split between those who see a deepening commerce infrastructure play and those who think rising costs and competition justify caution.
Bull case: 32% undervalued
"By expanding its role behind the scenes, Shopify increases switching costs, as merchants are less likely to leave a platform that handles payments, inventory, analytics, and customer identity."
Discover why this Narrative puts Shopify at 32% undervalued.
Bear case: 26% overvalued
"As e-commerce platform features continue to converge, Shopify risks losing differentiation, especially as larger merchants migrate to custom solutions or competitors introduce similar offerings."
Explore why this Narrative puts Shopify at 26% overvalued.
One More Shopify Check That Sits Beyond The P/E
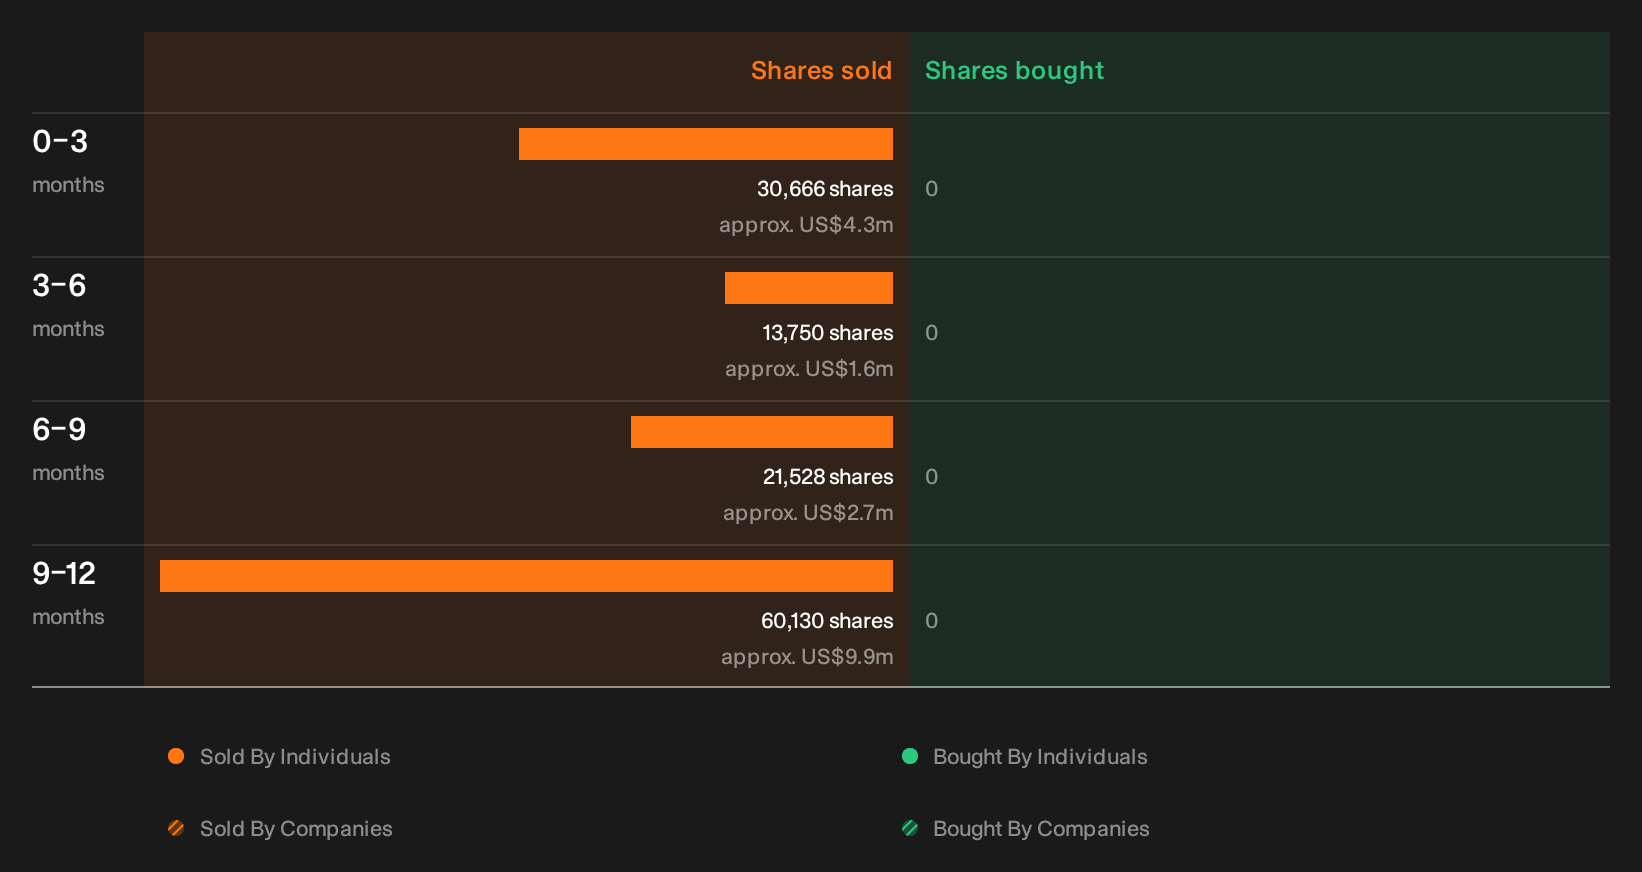
Price multiples tell you what the market is willing to pay today, yet recent transactions by people inside Shopify can hint at how those closest to the business are acting with their own capital. See the recent insider selling flagged for Shopify.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com