
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Wood Fiber Insulation Deal Might Change The Case For Investing In Weyerhaeuser (WY)
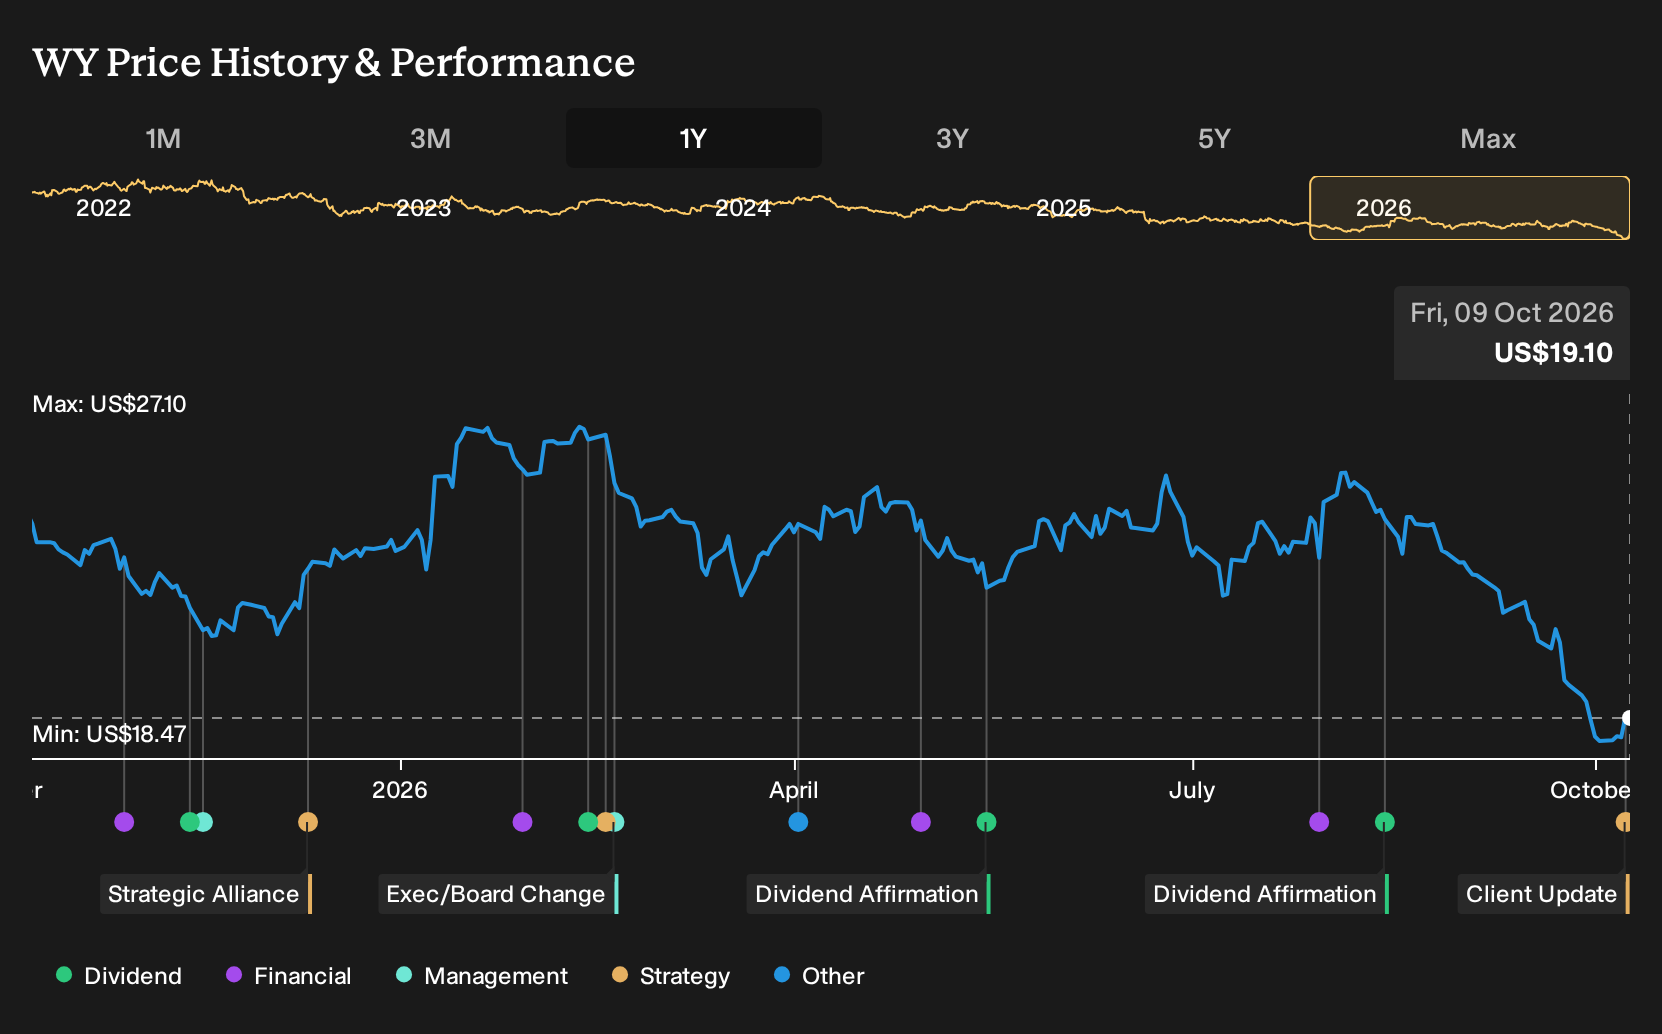
- TimberHP announced a commercial partnership with Weyerhaeuser, giving Weyerhaeuser U.S. commercialization and distribution rights in the LBM channel for TimberBatt, TimberBoard and related wood fiber insulation products, while TimberFill keeps its current distribution model.
- The arrangement extends beyond logistics and pairs Weyerhaeuser’s sales force with TimberHP’s technical team to support training, specification support and broader adoption of wood fiber insulation across U.S. building projects.
- We will now assess how Weyerhaeuser's expanded role in distributing wood fiber insulation could influence the company’s broader investment narrative.
Scan how Weyerhaeuser’s push into wood-based building materials compares with other construction and materials plays by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Weyerhaeuser Investment Narrative Recap
For a shareholder in Weyerhaeuser, the core belief is that timberlands, higher value wood products and emerging climate projects can collectively support earnings even when housing and Oriented Strand Board markets feel sluggish. The TimberHP partnership fits that story, but it does not change the near term reality of softer OSB profitability and housing activity described as stuck in second gear.
The near term swing factor still looks tied to execution on projects like the Monticello TimberStrand mill and disciplined capital allocation while leverage sits just above 5x net debt to EBITDA. The biggest risk remains a softer earnings patch that tightens interest coverage and keeps pressure on the dividend, rather than anything in this insulation agreement.
The Monticello TimberStrand mill project in Arkansas is the clearest recent announcement to line up with the TimberHP news. Both point to Weyerhaeuser leaning into higher margin engineered wood and adjacent materials, using its timber base and distribution reach to support more specialized building products instead of relying only on commodity cycles.
Monticello carries about US$500 million of planned capital spending. It is expected to reach more than US$100 million of annual EBITDA at full run rate after its planned first half 2027 start up. That scale makes execution on construction, ramp up and returns a more important catalyst, and also a more material risk, than the TimberHP distribution agreement on its own.
Weyerhaeuser's current analyst storyline points to revenue of US$8.5b and earnings of US$697.1m by 2029, based on an assumed 7.4% yearly top line growth rate. That implies current earnings of US$472.0m and an increase of about US$225m to reach the consensus profit forecast.
Uncover how Weyerhaeuser's fair value indicates a 57% potential upside to its current price, prior to broader expectations for Weyerhaeuser narrowing that gap.
Exploring Other Perspectives
One alternate view puts more weight on execution risk at Monticello rather than on the TimberHP insulation deal. Under that angle, the lowest analysts were penciling in about US$7.9b of revenue and US$781.2m of earnings by 2029, yet still landed on a lower US$24.0 target. That shows how sharply opinions on Weyerhaeuser can diverge and invites you to test how this new partnership might shift those pre news assumptions.
Explore 3 other Weyerhaeuser fair value estimates, including one that suggests it could be worth just $29.73!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Weyerhaeuser research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Weyerhaeuser. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weyerhaeuser's overall financial health at a glance.
Looking For More Ideas Beyond Weyerhaeuser?
If the Weyerhaeuser story has you thinking more broadly about where to allocate fresh capital, it can help to scan a wider field of candidates that already meet some of the quality checks you care about.
- Prefer to keep risk contained and sleep better at night, even when markets feel choppy? Review 31 resilient stocks with low risk scores that already clear a tighter risk screen.
- If consistent income is a priority, especially alongside more cyclical holdings like Weyerhaeuser, check out 8 dividend fortresses that focus on higher yielding payouts.
- Looking for potential mispricings where fundamentals and price do not fully line up? Use 28 high quality undervalued stocks as a starting universe for deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com