
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AXT (AXTI) Stock Could Look Pricey Given Its Rich Sales Valuation
AXT has turned into one of the bolder moves in US semiconductors over the past few years, and the current share price puts a spotlight squarely on what investors are paying for its sales. With such a sharp change in market value, the central issue is how that price lines up with the revenue the business actually generates.
- Over the past 3 years, AXT has delivered a share price gain of 2,838.2%, which puts a lot of pressure on the current valuation to be supported by its revenue base.
- The business model relies on translating specialty semiconductor materials into sustainable top line growth and cash generation, which can shape how much investors are willing to pay for each dollar of sales.
- There is a second opinion on AXT worth weighing. See what analysts think AXT's shares could be worth.
The issue now is whether AXT's current share price is justified by its sales when set against the Fair Ratio benchmark.
If you want to test the same sales versus price question across a broader set of semiconductor related listings, line AXT up next to the 92 AI infrastructure stocks.
Does AXT Look Pricey on Sales?
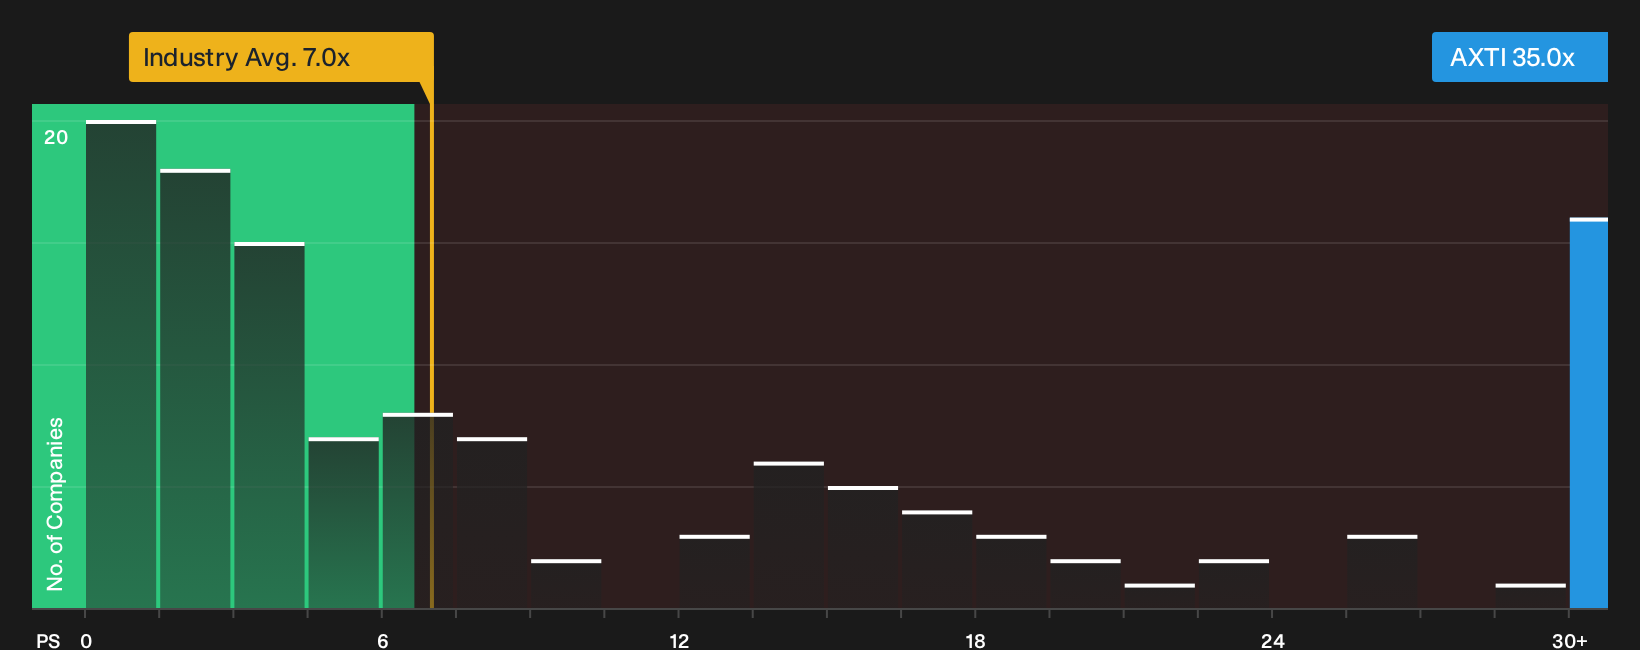
P/S suits AXT because investors are effectively paying for its potential revenue stream rather than current free cash flow. The stock trades on a P/S of 35.0x, which is far above the semiconductor industry average of 7.0x. It also sits well ahead of the peer group average of 4.0x, so every dollar of AXT revenue is priced at a much richer level than many similar businesses.
The Fair Ratio, which anchors the P/S multiple to AXT's own growth profile, margins, scale and risk, points to a lower level than where the shares trade today. On this lens, the stock looks overvalued because the current P/S stands meaningfully above what the tailored benchmark suggests investors might usually pay for this type of financial profile. To close that gap, you would either need a stronger sales base than implied by the model or be comfortable paying a premium for exposure to AXT's specific semiconductor niche. Explore the numbers behind AXT's P/S valuation.
The AXT Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for AXT leaves off by spelling out what would need to happen to AXT's growth, margins and earnings for the current price to look meaningfully higher or lower in hindsight, all housed on the Community page. Rather than relying on a single multiple, each scenario lays out its own set of fair value assumptions so you can compare those expectations with the financial results as they come through.
Community views on AXT are now split between investors who see AI driven upside and others who focus on export risk and customer concentration.
Bull case: 25% undervalued
"Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier…"
Discover why this Narrative puts AXT at 25% undervalued.
Bear case: 24% overvalued
"Persistent and unpredictable export permit delays and government-imposed trade restrictions in China are likely to restrict AXT's access to key international markets…"
Explore why this Narrative puts AXT at 24% overvalued.
One more AXT factor that could change the story
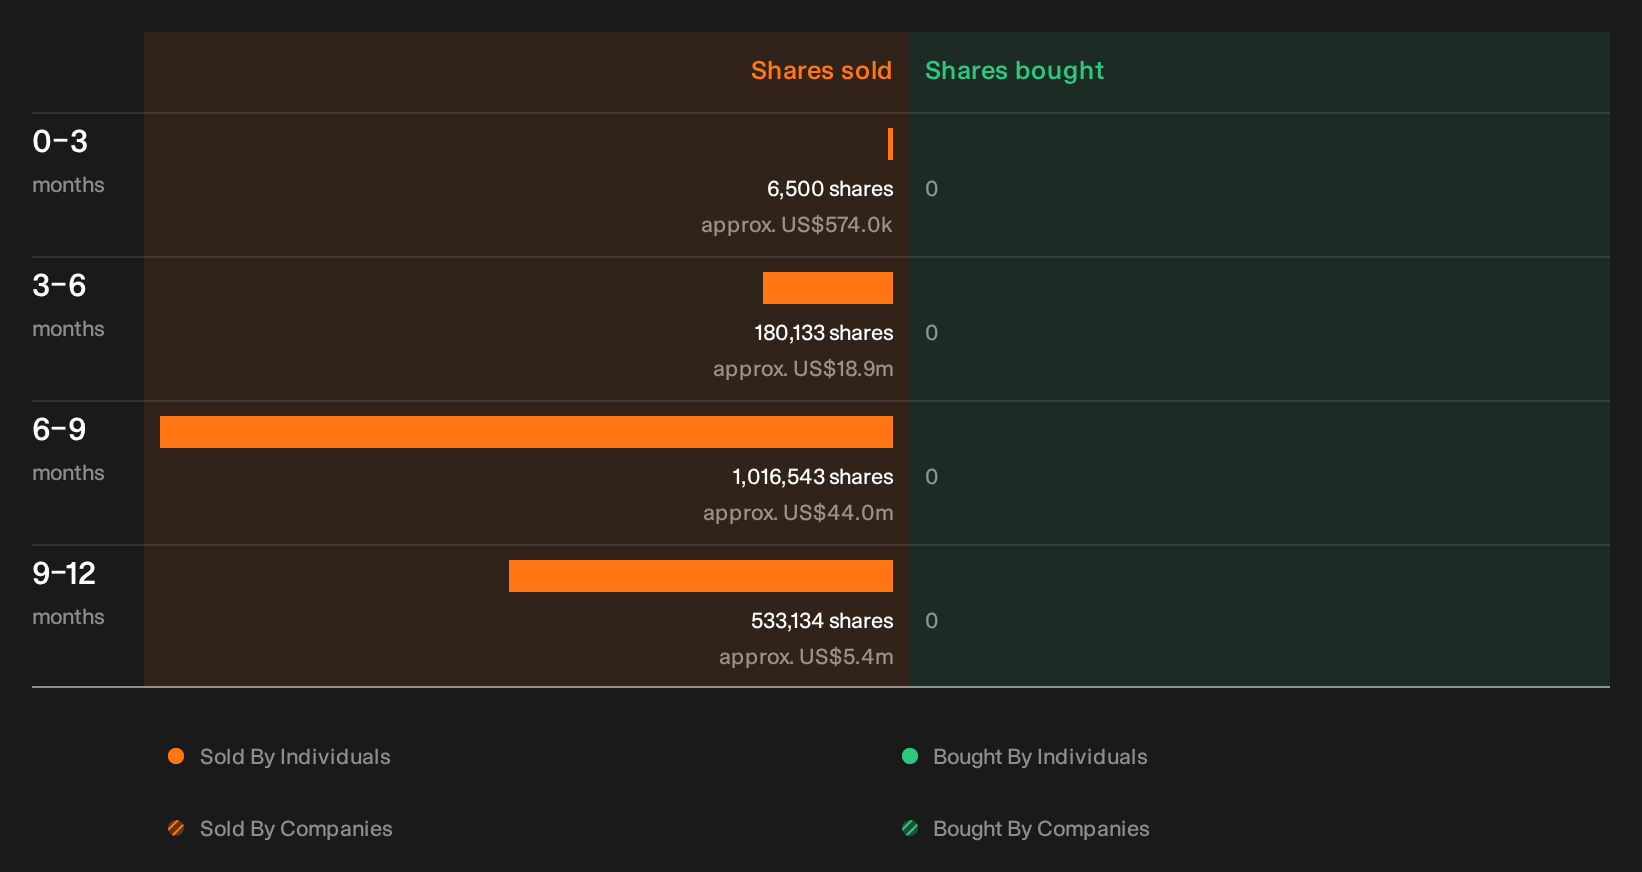
Before you move on from AXT, there is one loose thread that matters for any valuation view: the recent trading activity by people inside the business. See the recent insider selling flagged for AXT.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com