
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASICS And 2 Other Japanese Defensive Stocks
Rising U.S. government borrowing costs are putting balance sheet strength back in the spotlight. When global bond yields move higher, investors often pay closer attention to companies that rely less on cheap debt. For Japanese low risk leaders with solid finances, that focus can be an opening. This article highlights three stocks from our low risk screener that aim to offer a steadier base for your portfolio.
The three stocks in this article are just a starting sample, and the full Low Risk Leaders screen surfaced 20 more companies with equally compelling narratives that are not covered here. To identify and analyze those additional low risk candidates, head straight into the Low Risk Leaders screener.
ASICS (TSE:7936)
Overview: ASICS is a Japanese sportswear group that earns steady cash flow from running shoes and performance footwear sold worldwide.
Operations: ASICS generates most of its revenue from Europe at ¥278,636 million and Japan at ¥211,067 million, with meaningful contributions from North America and Greater China.
Market Cap: ¥3.1t
ASICS ties neatly into the Low Risk Leaders theme through its cash-generating running shoe franchise and globally recognised brands. Earnings grew 69.3% year over year, with net profit margins at 13.5%, supported by disciplined share buybacks and rising dividends. For investors seeking a sturdy anchor holding, an important question is what happens if one unseen pressure changes that earnings quality story.
If that unseen pressure worries you, review the 4 key rewards and 1 important warning sign to see how ASICS’ strengths compare with the key earnings question investors are circling.

Sansan (TSE:4443)
Overview: Sansan runs cloud-based platforms in Japan that help businesses manage contacts, invoices, contracts, and data quality so everyday operations run cleaner.
Operations: Sansan generates ¥46,847 million from Sansan/Bill One, ¥6,720 million from Eight, and ¥415 million from Others, almost entirely in Japan at ¥53,761 million.
Market Cap: ¥278.3b
Sansan fits into the Low Risk Leaders theme because its contact, invoice, and contract platforms help clients tighten working capital, formalize data flows, and build recurring, system-based processes. The company reports rising revenue and net income in the latest fiscal year, which supports that balance-sheet-focused profile. However, the low-risk case ultimately depends on how one key source of recurring demand behaves over time.
That recurring engine is exactly what the analysis report for Sansan unpacks, including where Sansan’s demand story could quietly accelerate or stall next.

PAL GROUP Holdings (TSE:2726)
Overview: PAL GROUP Holdings is a Japan based retailer that designs, manufactures, and sells apparel and daily goods through its store network.
Market Cap: ¥246.6b
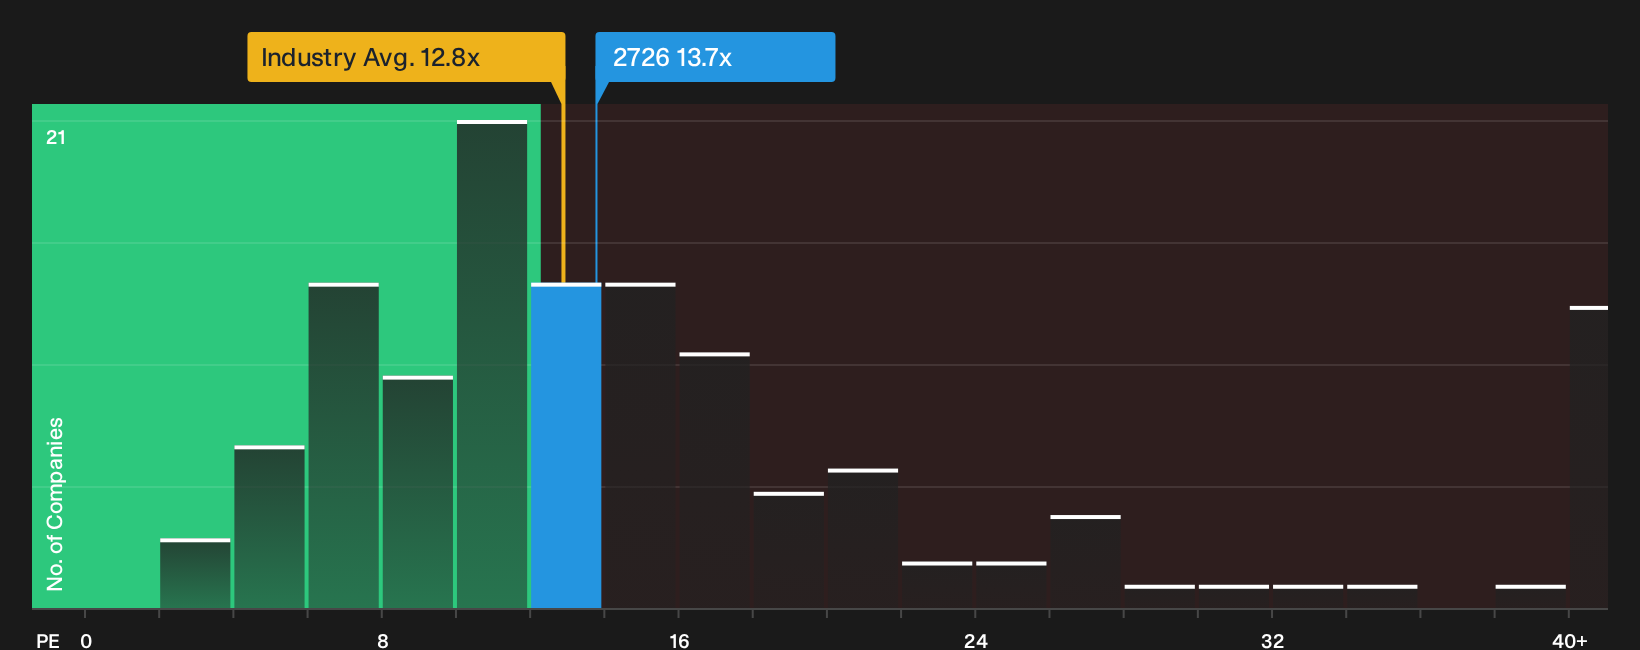
PAL GROUP Holdings fits the Low Risk Leaders theme through its apparel business, where steady clothing demand, 7.5% net margins, and roughly 20.6% ROE combine with a P/E of 13.7x against higher sector multiples. This creates a balance sheet focused story that looks appealing if one future shift in consumer driven cash flow holds steady.
If that cash flow holds, the next step is the 4 key rewards and 1 important warning sign, which breaks down where PAL GROUP Holdings’ resilience could quietly stretch further or start to fray.
Curious About What You Might Be Missing?
Fresh opportunities can move quickly. Some may be building quiet breakout momentum, and others could be flying under the radar for now. Review these ideas before the data goes stale.
- Identify income workhorses that aim to keep paying when markets wobble by scanning our curated 28 dividend fortresses before the crowd locks in those yields.
- Track fast movers tied to the build out of AI infrastructure by reviewing a hand picked set of 92 AI infrastructure stocks while the story is still forming.
- Explore potential upside from the next leg of electrification using our focused 16 top copper producer stocks while these producers remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com