
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 British Penny Stocks With Up To 19% Revenue Growth
Battery storage, now cheaper than many natural gas turbines, gives energy and data centre projects a fresh cost edge, and that ripple effect matters for UK small caps. Cheaper, more flexible power can help growth-focused businesses stretch every pound. This article looks at three low priced UK shares with strong balance sheets and limited dilution that have already moved up over the past year and remain on analysts’ high growth lists.
The three stocks covered below are just a sample, and the full screen highlights 8 more low priced UK companies with similar balance sheets, ownership structures and recent share price strength that are not included in this article.
If you want to identify and analyze the wider field of elite penny stocks with these traits, head straight to the Elite Penny Stocks screener.
Big Technologies (AIM:BIG)
Overview: Big Technologies develops Buddi, a web-based software and GPS hardware system that remotely monitors criminal justice offenders for governments worldwide.
Operations: Big Technologies generates about £51.9 million from electronic tracking devices and monitoring services, with revenue concentrated in Asia-Pacific, the Americas and Europe.
Market Cap: £271 million
Big Technologies links tightly to the Elite Penny Stocks theme because Buddi is a concrete remote monitoring product with government contracts and positive earnings. Recent H1 2026 results show revenue of £26.92 million and net income of £7.7 million, plus a new two year extension with New Zealand Corrections. The appeal now depends on how one quiet contracting trend shapes pricing power and long term margins.
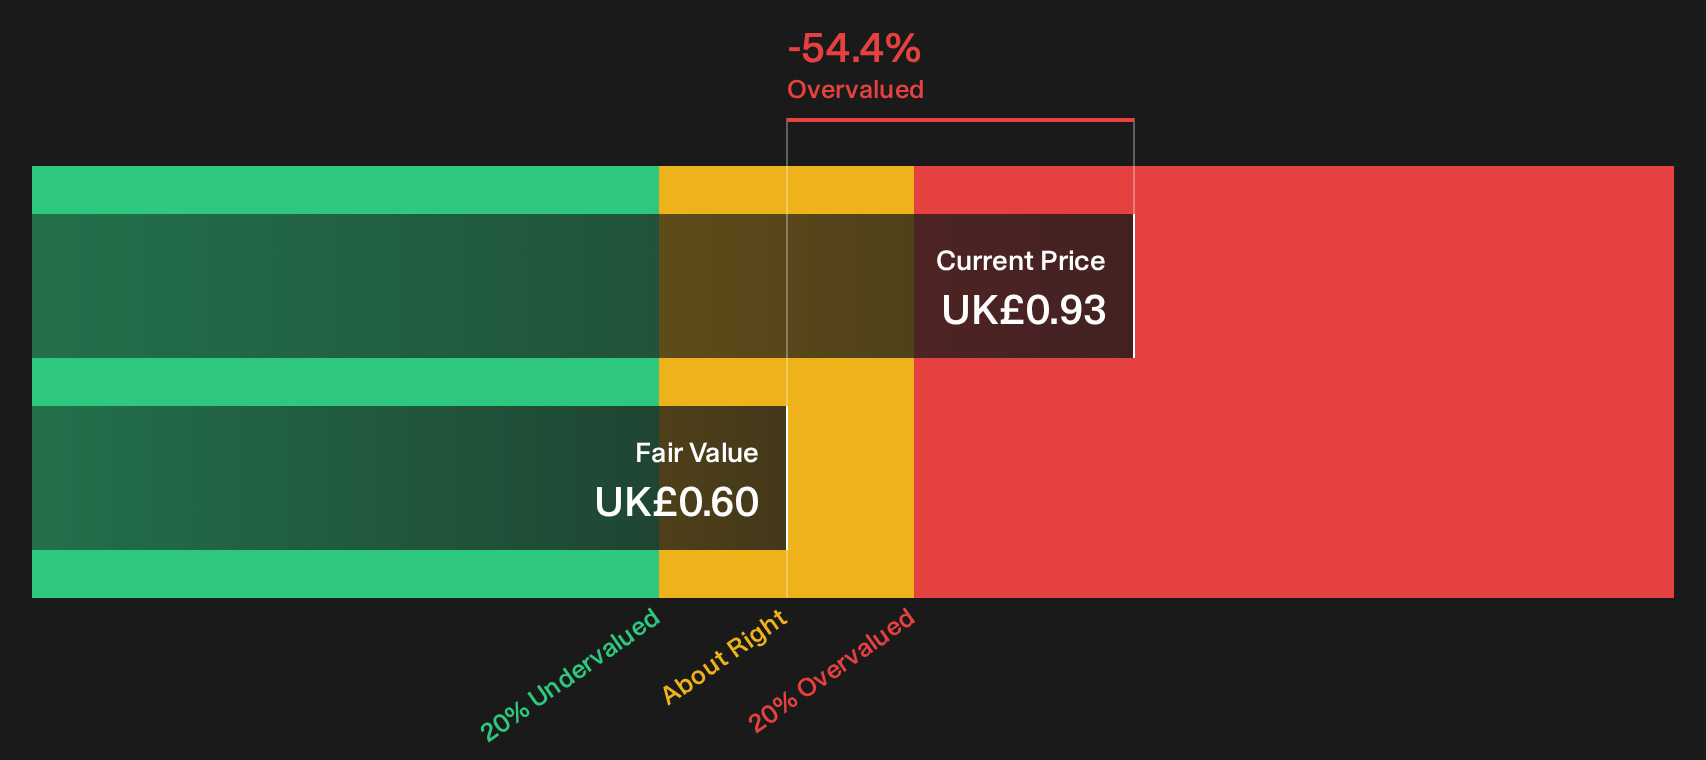
That contracting trend is the real hinge for Big Technologies, so it is worth going straight to the DCF valuation analysis for Big Technologies to see how pricing power is modeled.
Franchise Brands (AIM:FRAN)
Overview: Franchise Brands runs a portfolio of franchise-led service businesses, with Pirtek hydraulic services and Filta fryer management driving recurring franchise and service income.
Operations: Franchise Brands generates about £64 million from Pirtek, £36.5 million from Filta International, £44.6 million from Water & Waste Services and £5 million from B2C.
Market Cap: £298 million
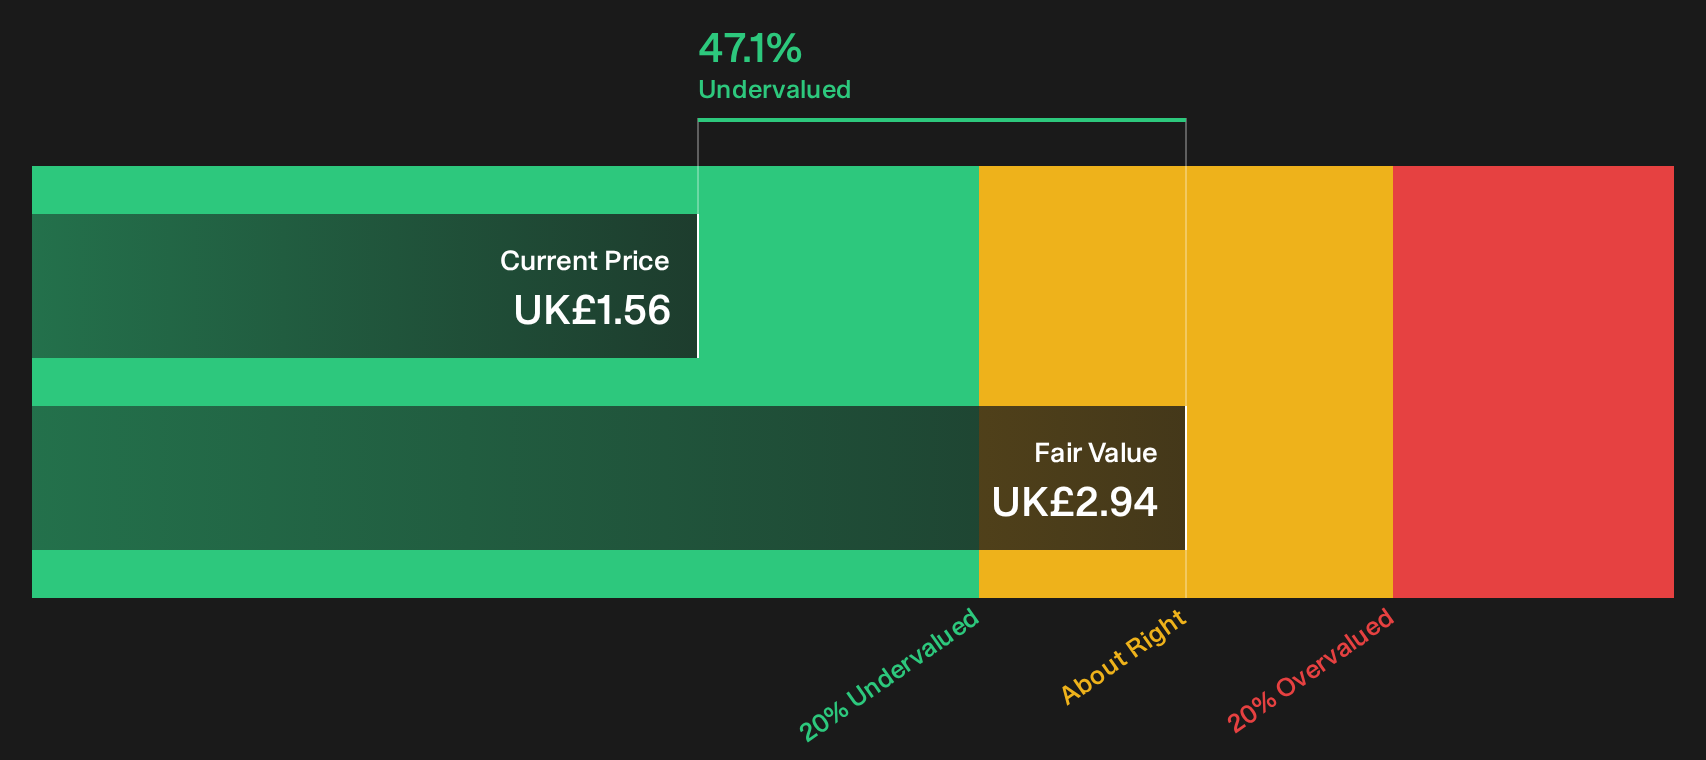
Franchise Brands ties closely to the Elite Penny Stocks theme because its Pirtek and Filta franchises convert repeat industrial and commercial maintenance work into recurring, high margin fees. In H1 2026 the company reported £75.6 million in sales and £6.13 million in net income, with a P/E of 27.4x and a share price below some estimated fair value models. The franchise system’s future pricing power is a key factor for investors to monitor.
That pricing question is exactly what the DCF valuation analysis for Franchise Brands explores, explaining where Franchise Brands’ current P/E could be masking potential upside or downside.
Diaceutics (AIM:DXRX)
Overview: Diaceutics runs the DXRX platform and data services that help pharma and biotech firms turn diagnostic lab data into precision-medicine decisions.
Operations: Diaceutics generates about £41.3 million from Medical Labs & Research, with roughly £38.8 million of that coming from North America.
Market Cap: £172.3 million
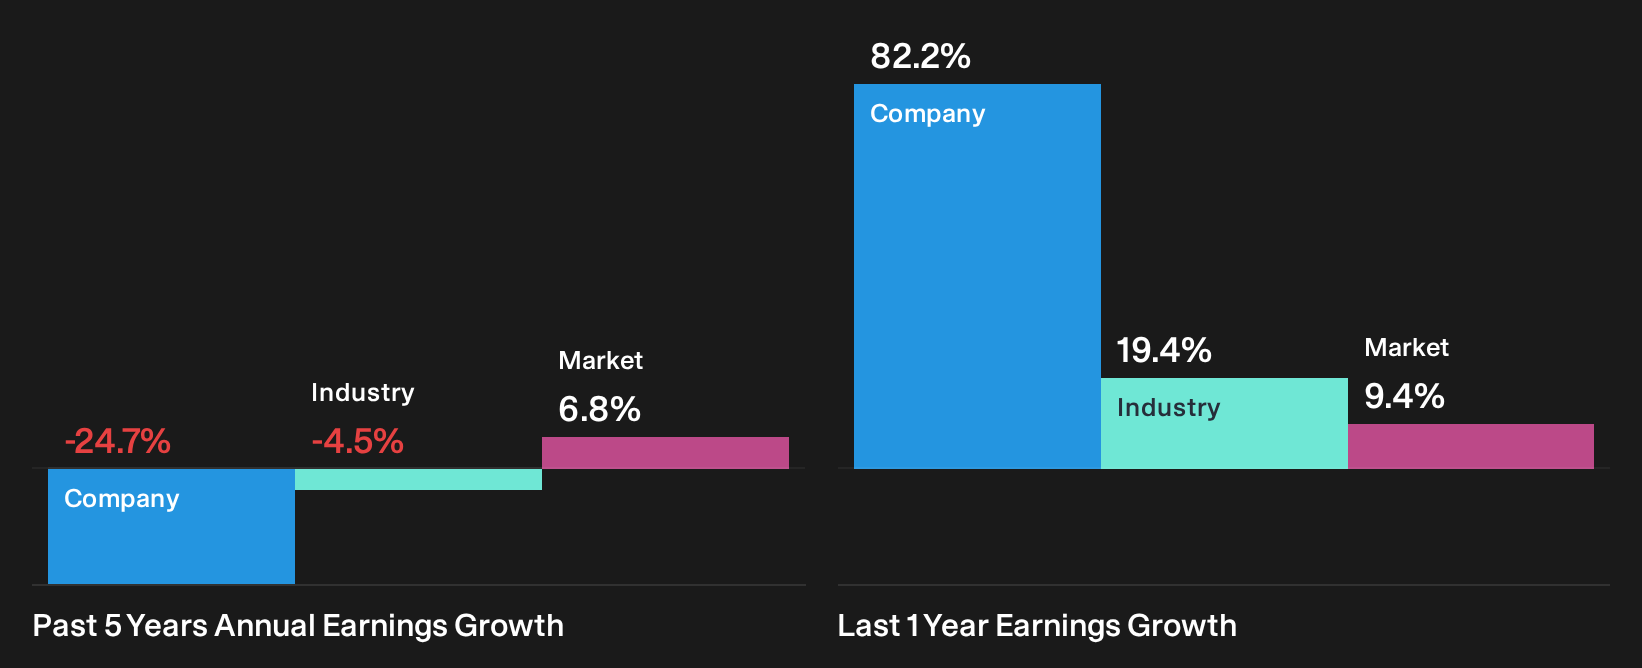
Diaceutics fits into the Elite Penny Stocks theme because DXRX diagnostic data products target high growth potential, while the share price trades about 22.3% below some fair value estimates. The catch is how a still loss-making model funded by external borrowing might cope if pressures on funding costs change.
That funding question makes Diaceutics especially sensitive to execution, so go straight to the analysis report for Diaceutics to see where the model could decouple from expectations.
Seeking Fresh Alternatives Before They Fly
Some shares start to break out quietly, then momentum builds and the most attractive entry points can be taken by others first. These ideas are still relatively under the radar for now.
- Consider potential income opportunities from companies screened for payouts through a curated set of 1 dividend fortresses before yields change and attention increases.
- Look for early movers in key infrastructure as power demand influences markets by scanning the hand picked 43 power grid technology and infrastructure stocks while these stories may still be overlooked.
- Review hardware suppliers connected to AI demand with a focused group of 92 AI infrastructure stocks before more investors examine the most widely followed tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com