
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Atlassian (TEAM) Unveils New AI Products, Is The Valuation Already Full?
Atlassian (NasdaqGS:TEAM) is back in focus after unveiling several AI focused product moves, including the Forward Deployed Engineering program and the Agentic Multiplayer Protocol, aimed at enabling deeper customer workflows and broader platform usage.
Recent excitement around Atlassian’s AI push is arriving on top of strong momentum, with a 30 day share price return of 16.34% and a 90 day share price return of 132.71%. The 1 year total shareholder return of 43.05% contrasts with a 5 year total shareholder return that is still down 49.53%.
Spot emerging AI momentum beyond Atlassian by scanning a curated list of 36 AI small caps that are also pushing hard into agentic workflows and enterprise automation.For Atlassian, this surge sits between two readings. Either AI launches are finally catching up with the underlying collaboration engine, or sentiment has sprinted ahead of what the current fundamentals support.
Most Popular Narrative: 1% Overvalued
Atlassian closed at $206.79, slightly above the most followed narrative fair value of about $205.39, so the story hinges on whether current AI and cloud execution can earn that small premium.
Accelerating adoption of AI-powered features and investments in integrating AI deeply into Atlassian's core cloud platform are expanding differentiated use cases, leading to higher user engagement, greater value per customer, and increased opportunities for premium upsells. These dynamics support future revenue growth and margin expansion. Continued digital transformation and enterprise cloud migration, highlighted by a record number of large enterprise deals and ongoing customer consolidation onto Atlassian's platform, are driving robust paid seat expansion and cross-sell opportunities. Together, these trends position the company for sustained top-line growth and improved operating leverage.
See why 119 investors see Atlassian as 1% overvalued.
Result: Fair Value of $205.39 (ABOUT RIGHT)
Still, Atlassian’s reliance on complex cloud migrations and on AI usage eventually turning into clear pricing power could unsettle that balanced, fair value story.
Find out about the key risks to this Atlassian narrative.
Another View On Atlassian’s Valuation
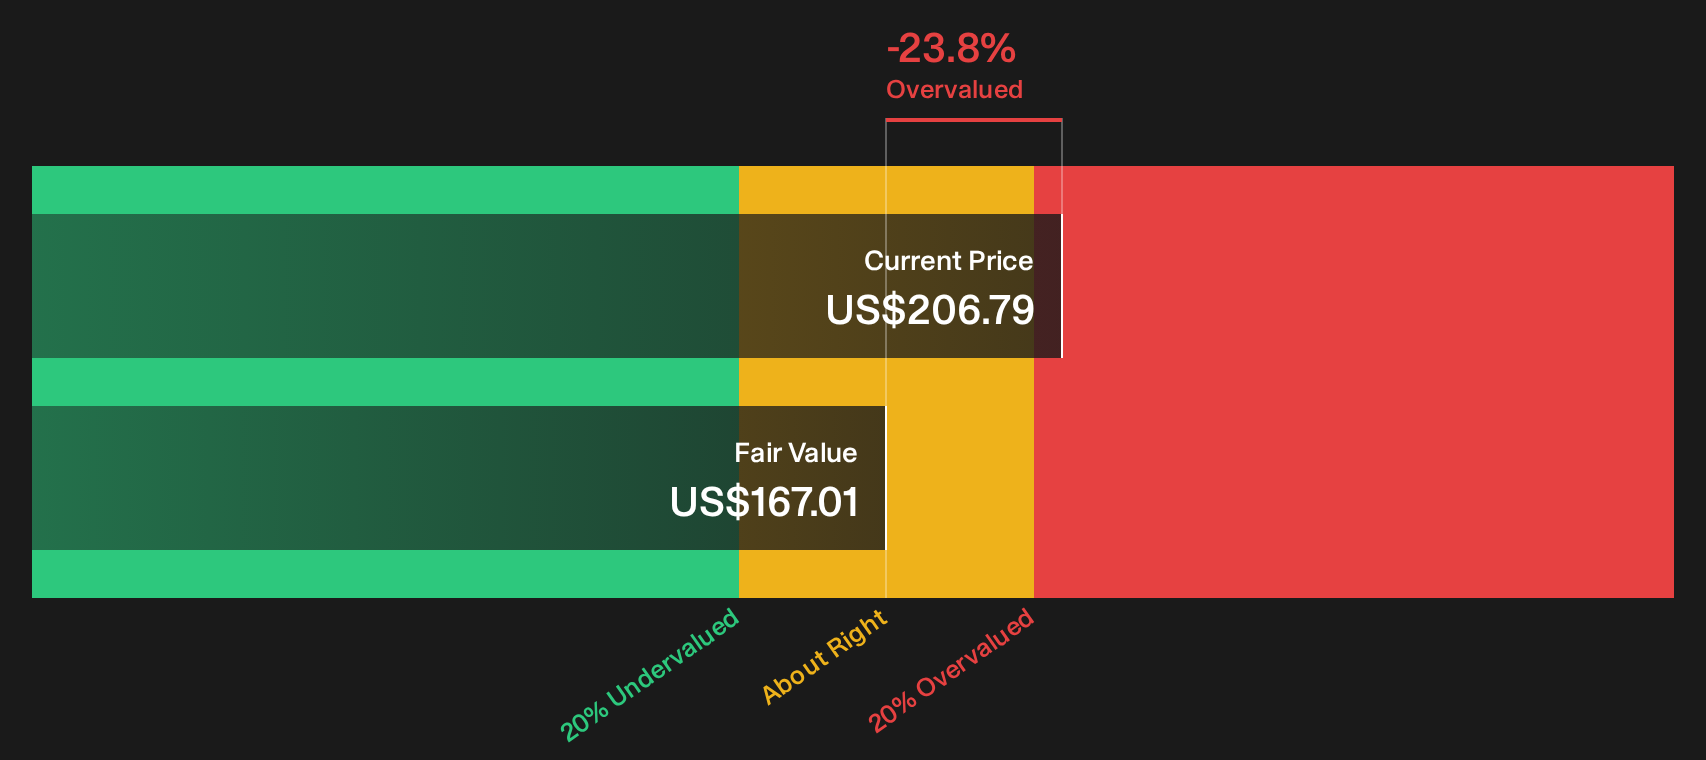
Analysts land near “about right” at a fair value of roughly $205 per share for Atlassian. The SWS DCF model paints a cooler picture, with an estimated future cash flow value of $167.01 while the stock trades at $206.79, which points to an overvalued signal instead.
That kind of gap shifts the question to you. Are the current AI and cloud expectations strong enough to justify paying well above what our DCF model suggests the cash flows alone support, or is patience the better side of caution?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this combination of optimism and caution around Atlassian leaves you uncertain, consider reviewing the numbers and sentiment for yourself using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Atlassian?
Do not stop with Atlassian. Use the Simply Wall Street Screener to quickly surface fresh ideas across quality, value, income, and stability so your watchlist keeps working for you.
- Explore potential long-term compounders by scanning 28 high quality undervalued stocks that pair healthy fundamentals with prices that sit below their assessed worth.
- Review 8 dividend fortresses that combine 5%+ yields with a focus on durability.
- Consider 31 resilient stocks with low risk scores that score well on financial robustness and volatility measures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com